LinkedIn thought leader ad examples
400 thought leader ads are live on LinkedIn right now, from 335 companies. Browse real ones, filtered by industry.
- BuckarooSince 23 Oct 2026
De winkelmand is gevuld, het betaalscherm laadt, en daar stopt het. Dat is de duurste plek van je hele webshop. De klant heeft gezocht, vergeleken en zijn mandje gevuld. Precies op het moment dat hij zijn portemonnee trekt, haakt hij af. In een eerste gesprek vraag ik daarom altijd wanneer de checkout voor het laatst is aangeraakt. Bij veel e-commerce teams is het antwoord: sinds de livegang van de site. De betaalmethoden staan er nog zoals ze toen zijn ingericht en mobiel is er later bijgekomen als afgeleide van desktop. Het gedrag van de klant is ondertussen wel veranderd. Hij rekent af op zijn telefoon en verwacht de methode die hij thuis gewend is. Elke extra stap in dat scherm kost je klanten die je al binnen had. De checkout is het enige deel van je webshop waar iemand daadwerkelijk geld overmaakt. Dat verdient vaker dan één keer per jaar aandacht.
- AccountsIQSince 21 Oct 2026
Ask a finance leader if they trust their numbers, and the room doesn't hesitate. Ask about if they trust AI with those numbers, and it goes silent. Today, our third CFO Mindset Report goes live. It sets out to explain that hesitation around AI. Finance leaders aren't skeptical about their data. 96% trust its accuracy. They don't have doubts about the technology either. 81% trust what AI produces. Yet 82% feel pushed to adopt AI faster than they're comfortable with. What's missing is clarity. On how to use it, where to start, and when to rely on it. Inside the report: → Where finance teams really stand on trust today → What they're still deciding without the full picture (68% say big decisions are made without enough data) → What they told us would give them the confidence to go further and faster with AI Huge thanks to every finance leader who took part, and to the team who brought this together. If you lead a finance function, I'd love to know: what would give you more confidence to move faster with AI? Read more here: https://lnkd.in/eTJU57GT
- AccountsIQSince 22 Oct 2026
My signature goes on the number whether a person calculated it or an algorithm did. That’s the part of the AI conversation I think gets missed. We surveyed over 1,000 finance leaders across the UK and Ireland for our CFO AI Paradox research. 82% feel pushed to adopt AI faster than they’re comfortable with. But the technology isn’t the problem: 81% already trust AI-driven outputs, and 96% trust their financial data. The hesitation is about accountability. 76% worry about becoming too reliant on AI for decisions that used to be theirs. Before I’d trust AI with my team’s work, I’d want to see three things: → A person approving entries before anything posts → Decisions I can explain → A clear trail from any figure back to its source None of that asks for less AI. It asks to see the workings. If you’re weighing up where AI fits in your finance team, the full finding in the report is worth a read: https://lnkd.in/ePTMtsnb
- BeCLMSince 22 Oct 2026
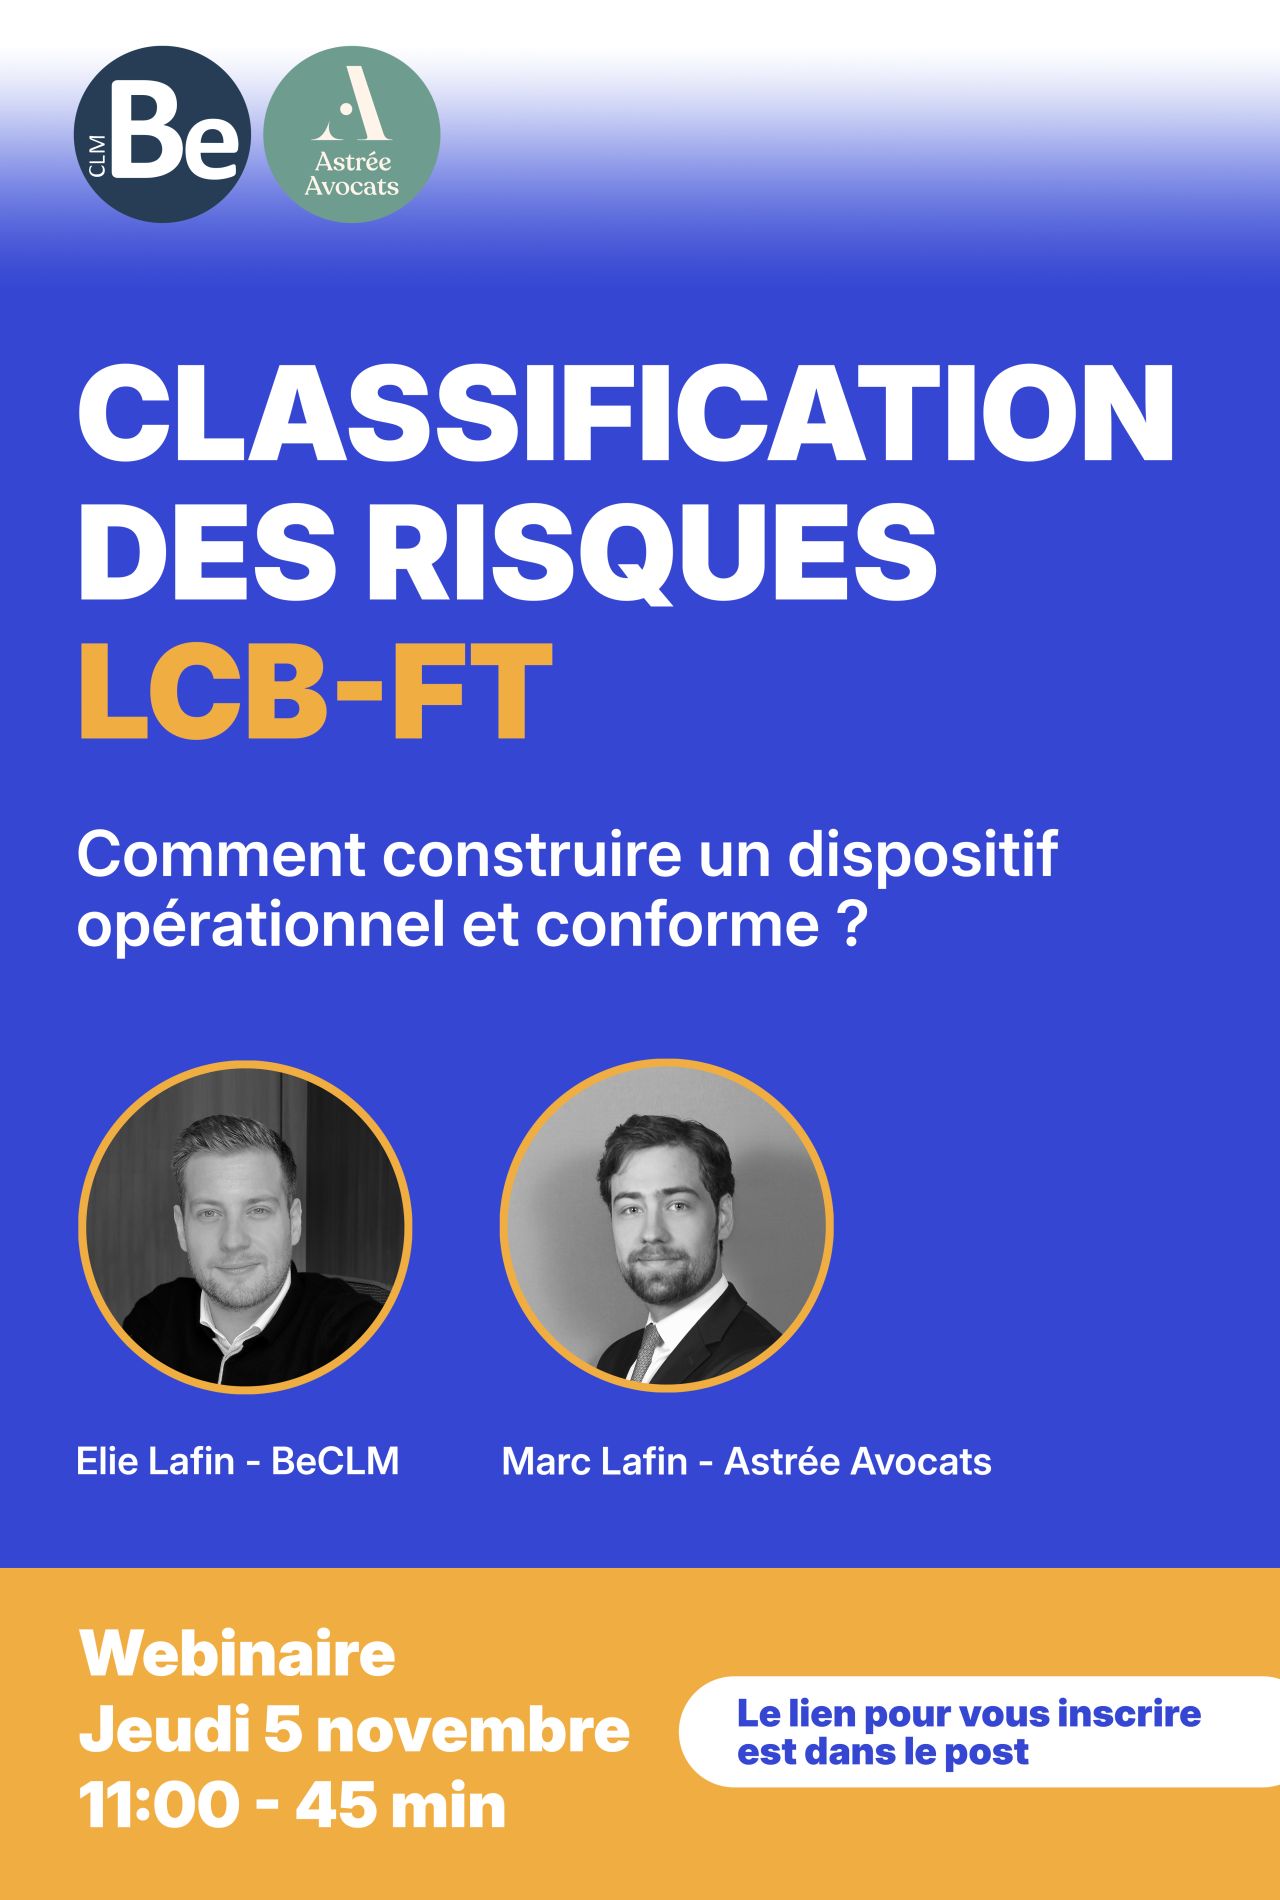
Le 5 novembre à 11h, on parle classification des risques LCB-FT. Inscription : https://lnkd.in/e_ymi7wc Si vous ne pouvez pas assister au direct, l’inscription vous donne accès au replay. On partage beaucoup de ressources sur notre site avec les responsables conformité : modèle de cartographie, listes de sanctions et de PPE par pays, niveau de risque de blanchiment par secteur d’activité, évaluation des tiers… Un sujet se détache, et de loin : la classification des risques. Dans les sanctions des autorités, idem : sur les 26 dernières sanctions de l’ACPR que nous avons analysées, 54 % des entreprises sanctionnées avaient une classification des risques jugée inadaptée. Or maîtriser le profil de risque de chaque client est une obligation, et ce profil repose précisément sur la classification. Sur le terrain même topo, les questions qu’on me pose le plus souvent : quels indicateurs ? quels critères ? avec quel poids ? d’où viennent les seuils ? On y répondra concrètement, avec Marc Lafin ( Astrée Avocats ) : → choisir les indicateurs à partir de vos axes de risque : clientèle, produits, canaux de distribution, pays ; → calculer les seuils d’opération à partir de la distribution réelle du portefeuille ; → articuler les critères bloquants, planchers et débloquants avec le scoring du reste du portefeuille ; → définir le profil d’un client standard pour repérer les comportements atypiques ; → dérouler des scénarios de blanchiment et identifier ceux que votre classification fait remonter. Le programme est dense : on tient à ce que vous repartiez avec du concret. Ceux qui seront là en direct recevront en plus plusieurs contenus exclusifs. Que vous partiez d’une page blanche ou d’une classification à faire évoluer, ce webinaire vous concerne. Au plaisir de vous y retrouver, avec vos questions.
- AlphaSenseSince 22 Oct 2026
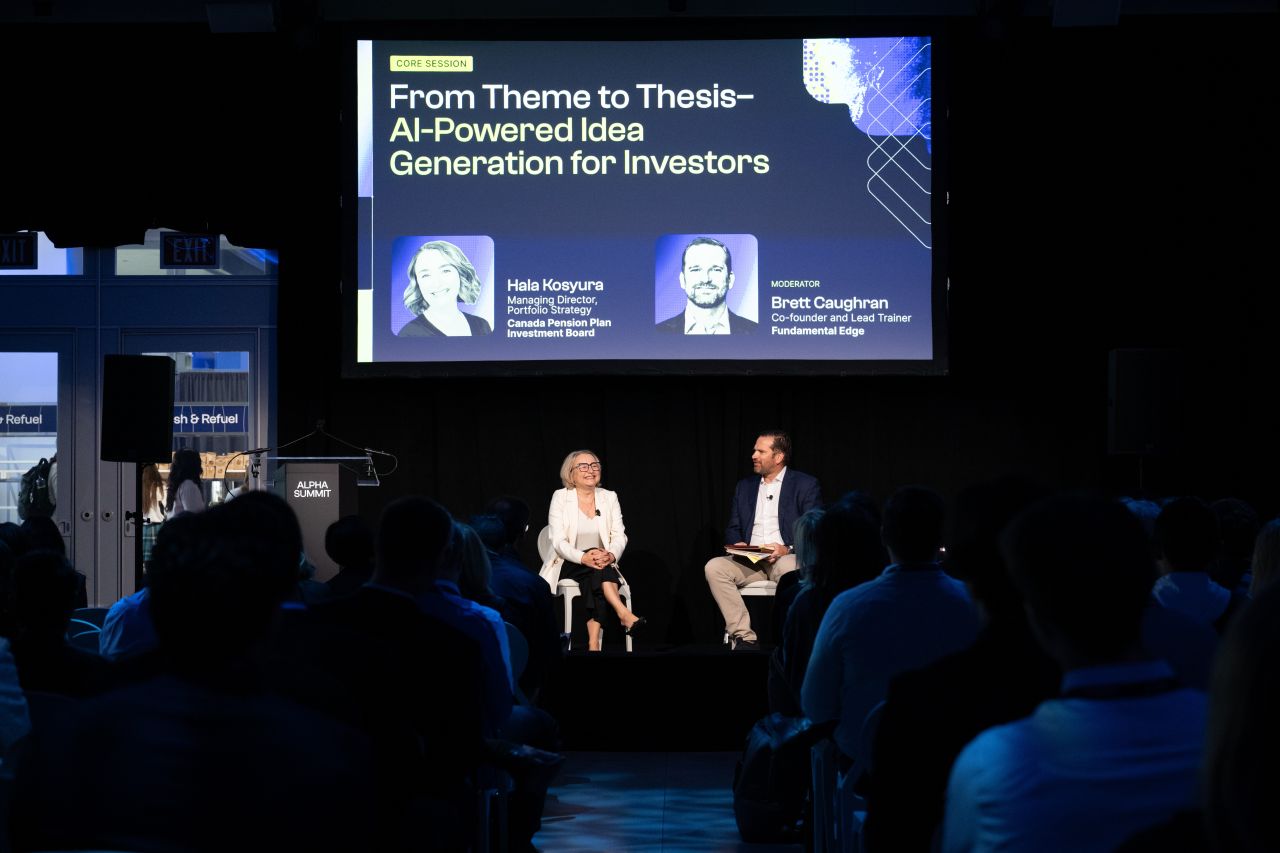
Speed and depth used to be a trade-off in research. At #AlphaSummit this year, our customers showed they no longer have to choose. A few moments that stuck with me: → At CPP Investments, Hala Kosyura shared how the new AlphaSense screening tools surface companies following patterns like “sustainable margin expansion”, near-instant completion of work that used to take days or weeks of brute force. → Jazmin Medina at D.E. Shaw Ventures walked us through a system tracking signals across nearly 5,000 private companies, work that used to take an enormous amount of time each time it was run. → At Jefferies, Michael Eastwood described an analyst who covered 26 complex small caps and three sector primers in a single month. AI handled the first 48 hours, then human judgment took it from there. Alanna Crank shared how an analyst compressed a coverage workflow from six months to four weeks. → Ian Lieberman at Talos Asset Management used SuperAnalyst to prep for a semiconductor tour in Asia, a job that normally takes 12 to 18 hours. His take: “I consumed two movies on the flight instead.” Every session came back to the same idea. The firms leading the charge are pairing agentic workflows with sharp human judgment enabled by traceable data. AI makes great investors even more valuable, and conviction is the edge. That’s just a few examples of what decision-grade AI looks like in practice. Thank you to everyone who shared their journey on stage at AlphaSummit. See full recap here: https://lnkd.in/gMWmi5Kr
- Advanced Time Segmentation™Recorded 24 Oct 2026
Rich finds ATS to be particularly impactful for clients approaching retirement, especially those with disorganized assets or incomplete planning. 💡
- Advanced Time Segmentation™Recorded 24 Oct 2026
Ask an advisor with 200 clients how they explain retirement income, and you'll get 1 answer. Sit in on 10 of their meetings and you'll see 10 versions of it. I wouldn’t call this carelessness, but improvisation. After 25 years you have a good version in your head — and that's the only place it is. What that costs: 👎 Prep time. Every plan built from scratch. 👎 Consistency. Your Thursday afternoon explanation isn't your Tuesday morning one, and the Thursday client doesn't know. 👎 Delegation. You can't hand it to an associate. There's nothing to hand them. 👎 Valuation. A practice that lives in one person's head sells for less. Every buyer knows it. Advisors usually brush this off as “being busy”. What ATS changed for a lot of them wasn't the client conversation but the fact that there was finally one conversation. Same structure, same sequence, whether the client has $400,000 or $4 million. An associate can learn it, meetings get shorter, and what you built stops depending on you being in the room.
- TDK VenturesSince 21 Oct 2026
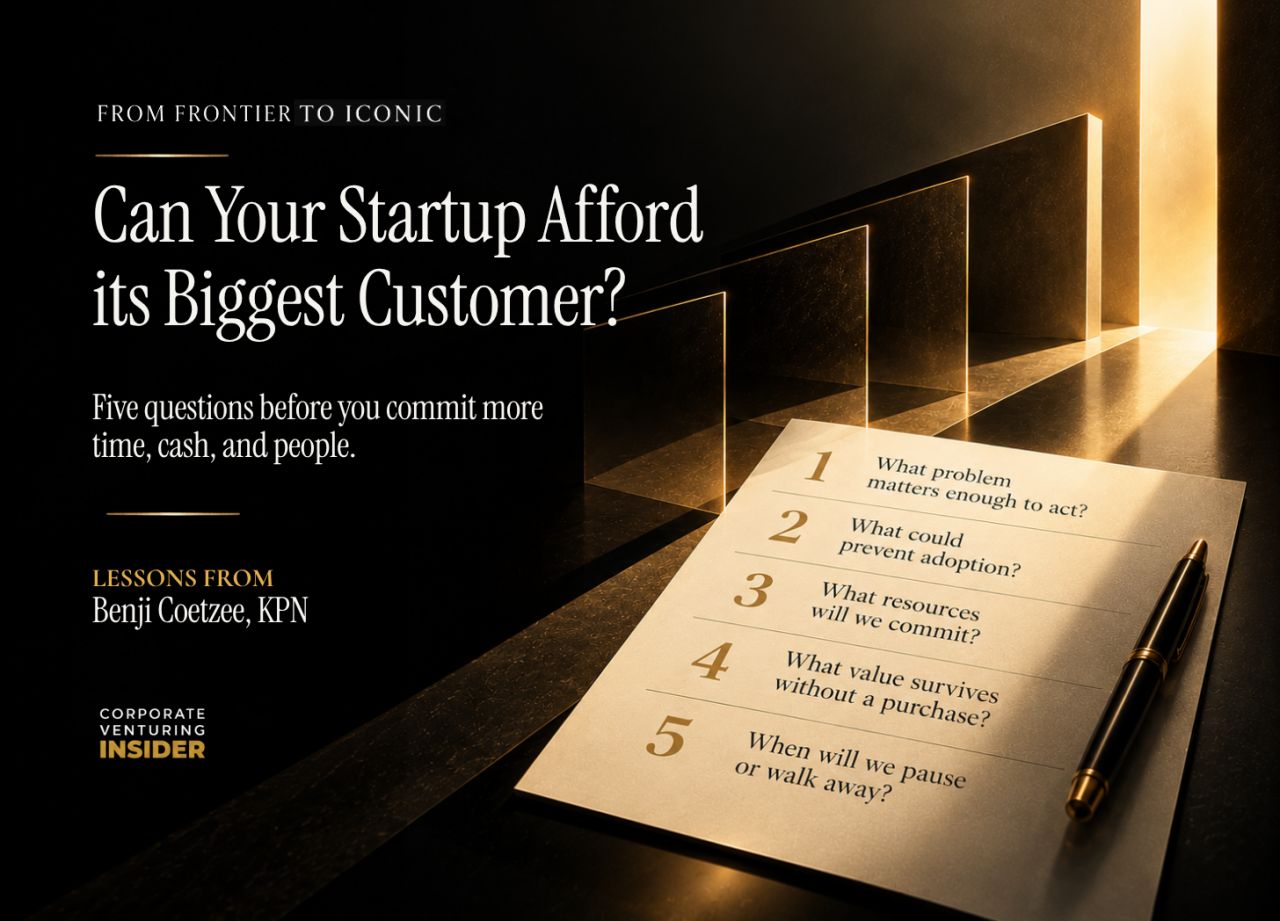
🔎 Can your startup afford its biggest prospective customer? When a prospective corporate customer suggested meeting again in six weeks, Benji Coetzee counted two payroll runs. A CFO then offered to pay for the proof of concept. She described it as a saving grace. In our Corporate Venturing Insider conversation, Benji, KPN's Chief Strategy and Growth Officer, explained how that founder experience shaped her approach to corporate partnerships. 💡 Before committing more resources, ask what value the startup would retain if the pilot succeeded but no larger contract followed. Payment may be part of the answer. Useful learning, access to data, or evidence that opens a new market may also justify the work. The answer should be specific enough to guide how much time, cash, and team attention you commit. In the article, I bring her observations into five questions founders can use to assess a corporate opportunity, identify barriers to adoption, and set a limit on the resources they put at risk. I also explore how corporate sponsors can make the relationship more viable. 📖 Read "Can Your Startup Afford Its Biggest Customer?" in From Frontier to Iconic. Subscribe there for practical reflections on how frontier technologies become global companies. https://lnkd.in/g9NuFBhm
- BillinkSince 22 Oct 2026
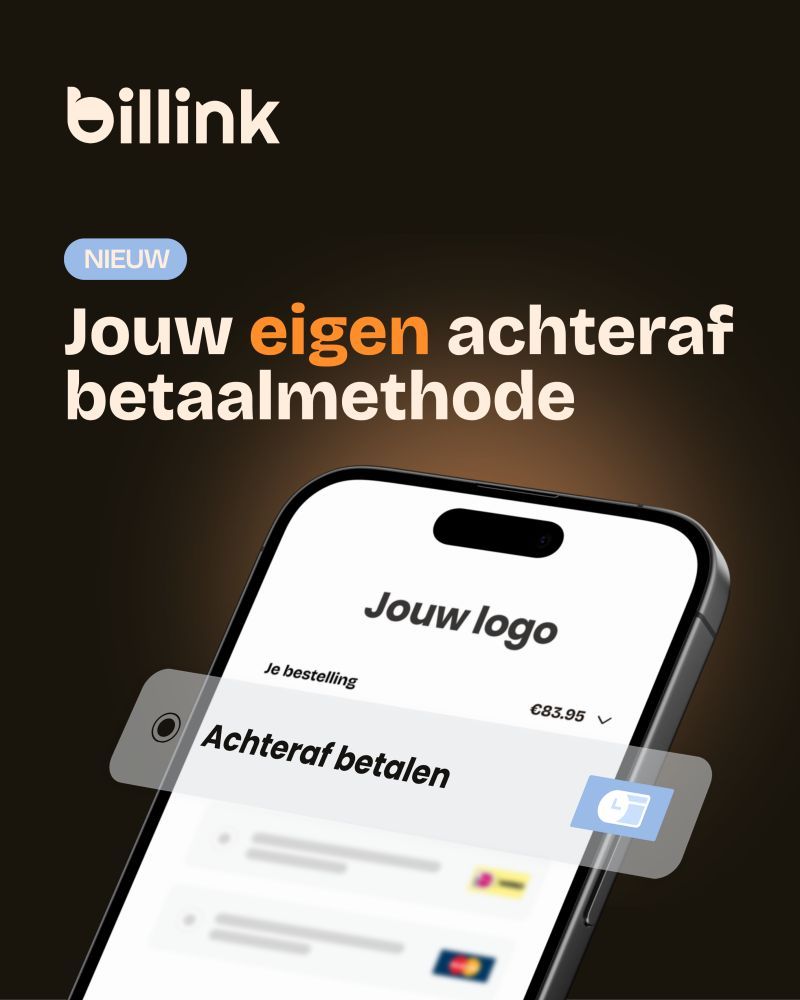
𝗡𝗜𝗘𝗨𝗪! 𝗔𝗹𝘀 𝘄𝗲𝗯𝘀𝗵𝗼𝗽 𝗸𝗹𝗮𝗻𝘁𝗲𝗻 𝗹𝗮𝘁𝗲𝗻 𝗯𝗲𝘁𝗮𝗹𝗲𝗻 𝘃𝗶𝗮 𝗷𝗲 𝗲𝗶𝗴𝗲𝗻 𝗮𝗰𝗵𝘁𝗲𝗿𝗮𝗳 𝗯𝗲𝘁𝗮𝗮𝗹𝗺𝗲𝘁𝗵𝗼𝗱𝗲! Trots en vooral heel enthousiast dat we dit eindelijk kunnen delen. De afgelopen maanden hebben we achter de schermen hard gewerkt aan een nieuw product: Billink Factoring. Hiermee kunnen webshops klanten achteraf laten betalen via hun eigen betaalmethode. Rechtstreeks vanuit de eigen checkout, volledig in de vertrouwde look & feel van de webshop. Een oplossing waar veel klanten al langer om vragen én die aansluit op de nieuwe wet- en regelgeving die eind dit jaar ingaat. Een stap waarmee we ons verder onderscheiden en relevanter maken dan ooit. Hiermee helpen we Nederlandse e-commerce ondernemers verder te groeien en hun klanten te blijven bedienen zoals ze gewend zijn. Heel trots op het team dat hier de afgelopen maanden keihard aan heeft gewerkt. Vooral ontzettend veel zin om dit verder naar de markt te brengen en in steeds meer checkouts te zien verschijnen. Billink Factoring is live. Let’s go! 🚀🧡
- TDK VenturesSince 22 Oct 2026
The ambition behind 100X is to help founders deliver two orders of magnitude improvements for society and our planet. 🌍 Louis Lehot captured that spirit beautifully in his reflections on 100X 2026. Thank you, Louis and the Foley & Lardner LLP team, for joining our 100X partnership program and for sharing the golden nuggets with a wider community. I'm grateful for both your support and the care you took to explain what we are working toward. Two insights from Louis's article stayed with me: ⚡ AI's progress depends on the energy infrastructure supporting it. Power availability, grid capacity, and deployment realities increasingly shape what becomes possible. 🤝 Breakthroughs reach scale through relationships built over time. His account of Chuck Mattera's session highlights the patience and discipline behind decades of company building. For a founder, these ideas belong together. The path to a much larger impact often runs through a constraint that another organization understands deeply. That leaves me with a practical question: which partner could help a founder overcome the next barrier to deploying their technology? This is what we want 100X to make possible: founders, investors, industry leaders, and partners learning from one another and finding ways to build together. Louis, thank you for helping those conversations reach beyond the room. Sharing what we learn gives more people a chance to build on it. For those building or backing companies where energy and AI meet, his article connects the infrastructure challenges with lessons from experienced company builders. Well worth reading. 👇 https://lnkd.in/gFSJcB5J
- FinastraSince 20 Oct 2026
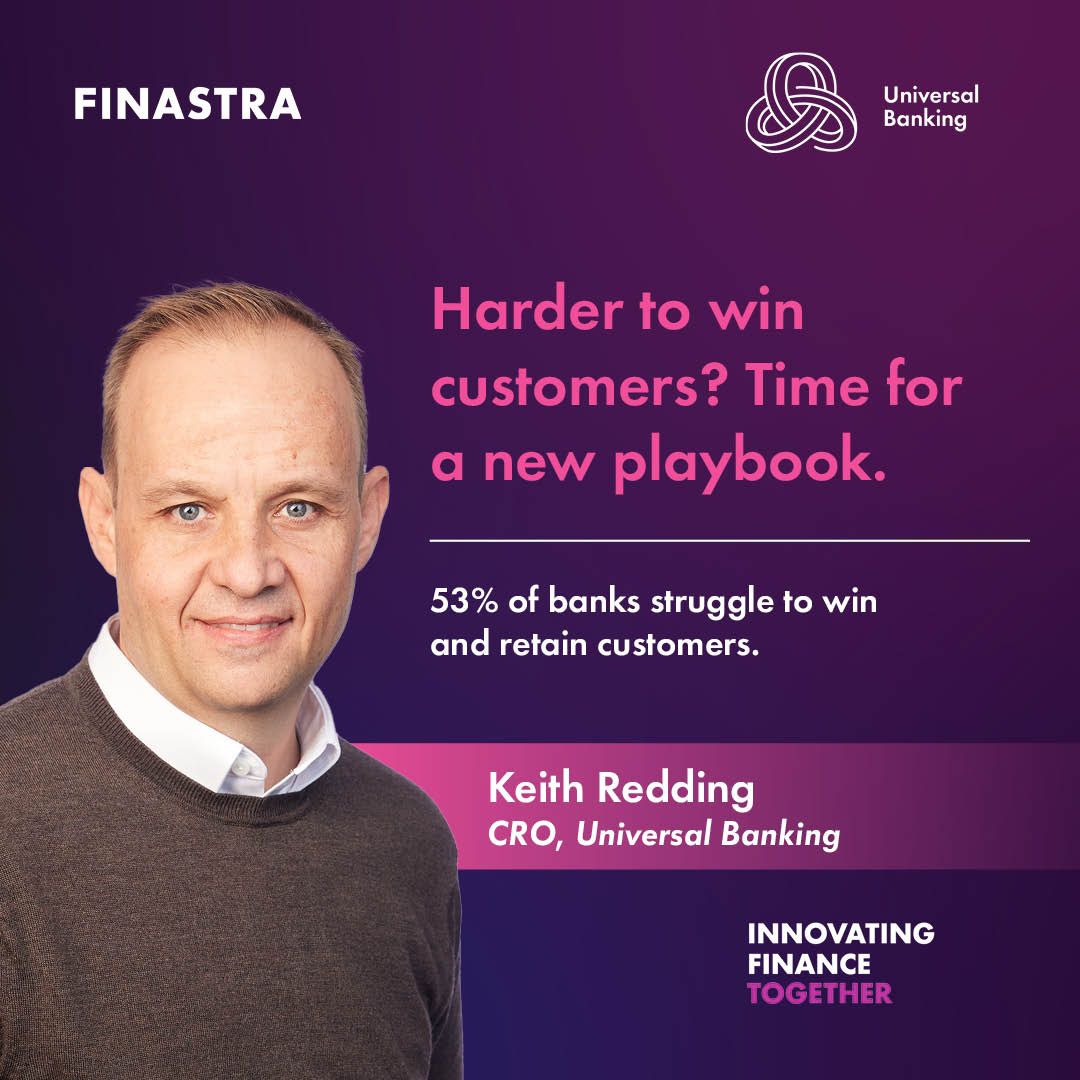
Over 53% of banks today say it’s harder to win and retain customers than a year ago. What if I tell you that this is actually an opportunity? As customer expectations shift and margins tighten, banks need a new playbook for growth. From embedded finance to ecosystem partnerships, the future belongs to those who innovate beyond traditional models. Discover how to reimagine revenue strategies for sustainable growth. Read the full article: https://lnkd.in/dB99bmpE #ReimagineBanking #BankingInnovation #RevenueGrowth #FutureOfFinance #CRO
- FinastraSince 20 Oct 2026
Customers want mobile convenience, but are banks delivering? Between 65 - 73% of customers prefer to complete financial tasks on mobile, yet fewer than half receive offers that truly match their needs, often because legacy systems can’t deliver relevant experiences across channels. If personalized offers aren’t reaching customers where they are (on mobile), banks risk losing engagement and trust. The solution is to design products around real expectations. When banks listen and act on what matters most, they build stronger relationships and accelerate growth. Read how product strategy can drive real differentiation: https://lnkd.in/ezhNC-zP #ReimagineBanking #BankingInnovation #Fintech #ModernizingCore #FinastraEssence #BankingPlatform
- DNB CarnegieSince 20 Oct 2026
🤖 📉 📈 NORDENS BÄSTA PLATTFORM | Roligt att FinansWatch och Teresa A. uppmärksammar vårt arbete att bygga Nordens bästa plattform för privata investerare och entreprenörer. Precis som artikeln beskriver handlar det mycket om HUR man jobbar för att nå EFFEKT och skapa nåt som faktiskt är ledande. Länk till artikeln i kommentarerna.
- frootsSince 20 Oct 2026
In den 60er-Jahren hat man eine Aktie im Schnitt acht Jahre gehalten. Heute sind es ein paar Monate. Jede Nachricht und jeder Tweet ist Sekunden später im Preis. Der Markt reagiert schneller als je zuvor. Aber ob eine Veränderung oder eine unternehmerische Entscheidung positiv war, zeigt sich oft erst nach vielen Jahren. Nicht nach Quartalen und schon gar nicht nach Stunden. Der Markt macht also kurzfristige Wetten auf langfristige Ergebnisse. Jeff Bezos hat das einmal sehr schön auf den Punkt gebracht. Wenn ihm jemand zu starken Quartalszahlen gratuliert hat, hat er sich bedankt und sich gedacht: Dieses Quartal war schon vor Jahren entschieden. Er selbst arbeitete längst an Ergebnissen, die erst Jahre später sichtbar werden. Das gilt in beide Richtungen. Ein gutes Quartal ist selten der Verdienst des aktuellen Quartals. Und ein schlechtes selten dessen Schuld. Bei froots sehen wir genau darin unseren Vorteil. Ein langfristiger Zeithorizont und das Wissen, dass auf der Welt alles zyklisch ist, sind heute ein echter Wettbewerbsvorteil. Gerade in einer Welt, die immer schneller wird und in Daten ertrinkt. Während alle auf die nächste Headline reagieren, fragen wir: Welche Zukunftserwartungen kaufen wir heute schon mit? Wo ist der Markt euphorisch, wo pessimistisch? Denn die Zukunft muss gar nicht großartig sein. Sie muss nur besser sein als das, was heute schon eingepreist ist. Tune out the noise. Das klingt einfach. Ist es nicht. Weil sich Geduld oft wie Nichtstun anfühlt. ℹ️ Dies ist eine Marketingmitteilung. Bitte beachte, dass Kapitalanlagen mit Risiken verbunden sind. Weitere Informationen und Risikohinweise findest du auf froots.io.
- FinoboSince 21 Oct 2026
Hvis der lå 200.000 kr. gravet ned i din have, ville du nok leje en minigraver. Men et kig på boliglånet? Det må lige vente. Kan du se det lidt skæve i det? I tankeeksperimentet ville vi grave græsplænen op efter en mulig skat. Men når jeg taler med folk om mulighederne i deres boligøkonomi, oplever jeg ofte, at det bliver udskudt. Og jeg forstår det godt. En spade er sgu til at forstå, og langt nemmere at forholde sig til En bidragssats, renter, kurser er sgu bare ikke særlig sexet.. Og når jeg samtidig fortæller dig, at der er mere en 50 forskellige banker i Danmark, ja så taber du nok pusten... Min pointe er enklere: Du behøver ikke vide, om der er noget at hente, før du undersøger det. Og du behøver ikke selv blive ekspert for at tage første skridt. Hos Finobo kan du starte med vores gratis omlægningsberegner. Den giver dig et vejledende estimat på din mulige besparelse: Klik på linket i kommentarsporet, og start din guldjagt nu! ⤵️ #tagskridtet#besparelse#NoCureNoPay#
- DepaySince 20 Oct 2026
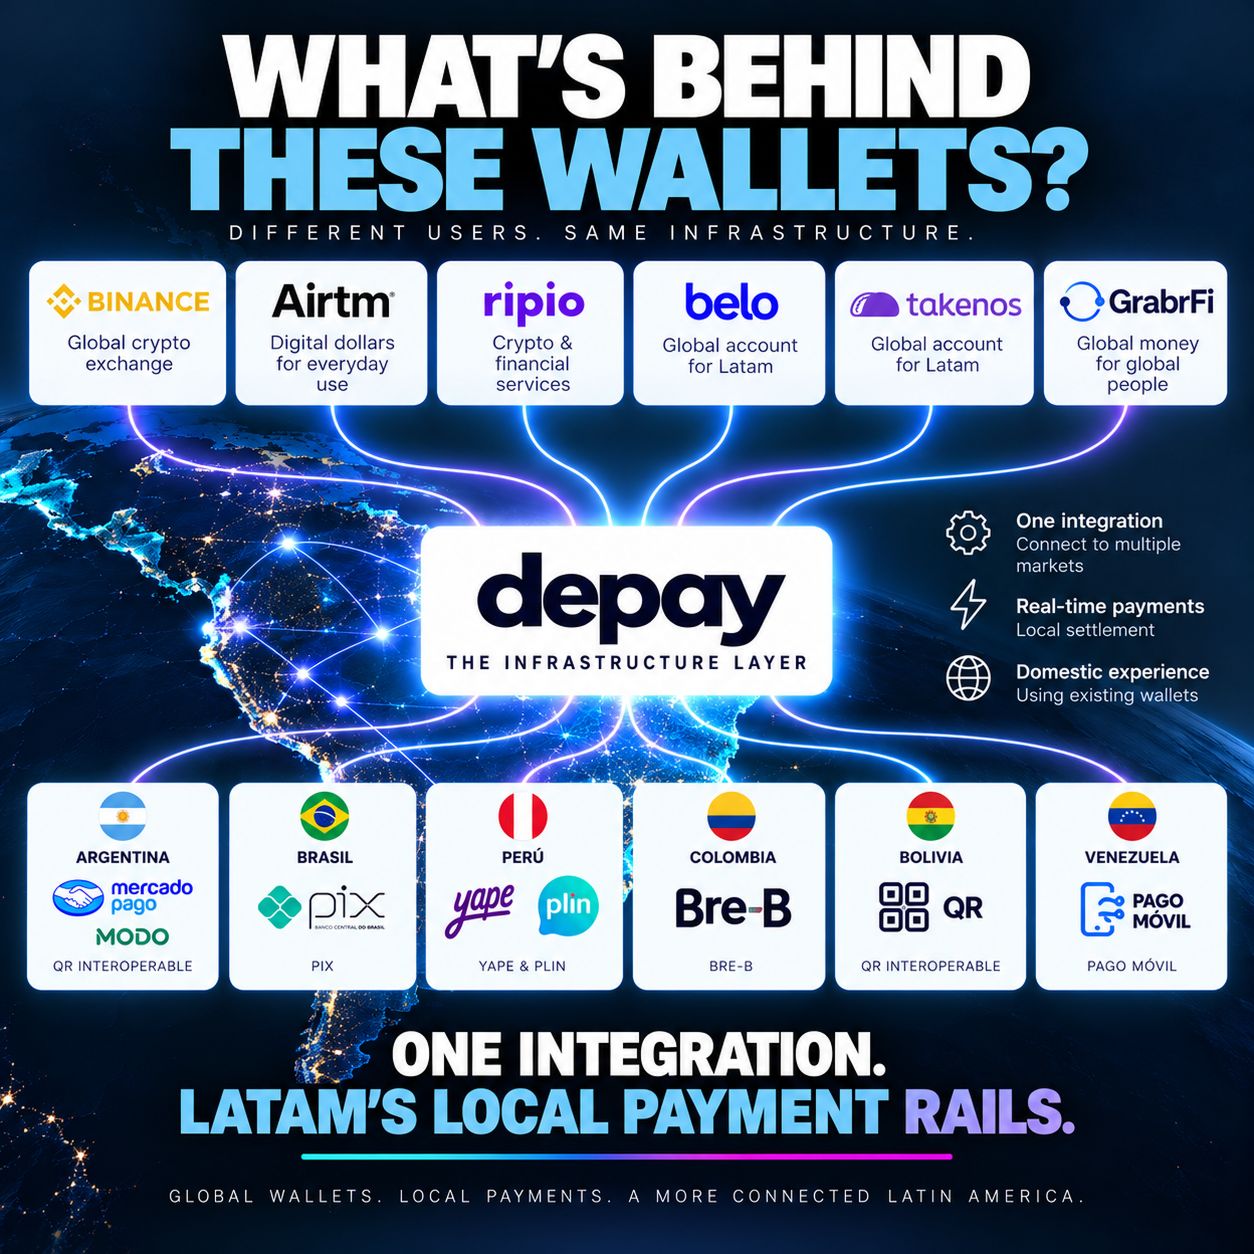
What’s behind these wallets? Millions of people know Binance, Airtm, Ripio, belo, Takenos and GrabrFiFi. But what happens when someone wants to use their money across Latin America? That's where things get complicated. Brazil has Pix. Argentina has interoperable QR payments. Colombia has Bre-B. Peru has Yape and Plin. Each market has its own payment habits and infrastructure, and a wallet that works well in one country doesn't automatically work in another. For companies trying to expand across the region, connecting to every local payment system separately can quickly become a headache. Depay is working on the part most users never think about: connecting these wallets to the payment systems people already use in each country. Take Pix in Brazil or Bre-B in Colombia. People don't want to learn a new payment method just because they're using a wallet from another market. They want to pay the way they normally do. That's the interesting part of this model. The wallet doesn't have to replace local payment apps or convince merchants to adopt something new. It needs to work with the systems already in place. I've been following the development of payments in #LATAM, and it's interesting to see how quickly the region is evolving. Local instant payment systems are becoming part of everyday life, while more fintech companies are serving customers across borders. The next big opportunity won't be building yet another wallet. It'll be connecting the wallets we already have to more markets. Because a payment that crosses a border doesn't necessarily need to feel like one. For the customer, it should just work. #fintech #payment
- frootsSince 20 Oct 2026
Langfristiges Investieren für Kinder war bis dato einer der blindesten Flecken in Österreich. Wer im Namen des Kindes vorsorgen wollte, konnte das nur mündelsicher tun. Und wer es im eigenen Namen macht, stand schnell vor ganz praktischen Fragen: Auf wessen Namen läuft das Depot? Wer hat Zugriff auf das Geld? Und wer entscheidet eigentlich über die Veranlagung? Mit so vielen Eltern habe ich in den letzten Jahren diese Punkte besprochen und diskutiert. Das geplante Zukunftsdepot ist für mich deshalb ein echter Meilenstein. Zum ersten Mal können Eltern im Namen ihres Kindes langfristig veranlagen, und zwar so, dass 👉 Risiken gemanagt statt vermieden werden, 👉 Entscheidungen mit einem langen Horizont getroffen werden und direkt dem Kind zugutekommen, 👉 Finanzbildung erlebbar wird, für das Kind und für die Eltern selbst. Gerade dieser letzte Punkt ist meines Erachtens enorm wichtig: Learning by Doing. Um zu verstehen, wie viel Zeit es braucht, bis Geld sinnvoll für einen arbeiten kann, muss man es selbst erleben. Ein Kind, das mit seinem eigenen Depot aufwächst, erlebt Zinseszins, Schwankungen und Geduld nicht als Theorie, sondern als Teil seines Erwachsenwerdens. Ich freue mich sehr, dass Österreich hier endlich aufholt. https://lnkd.in/d_9xWW3K #Finanzbildung #Vorsorge #Zukunftsdepot #Investieren #froots ℹ️ Dies ist eine Marketingmitteilung. Bitte beachte, dass Kapitalanlagen mit Risiken verbunden sind. Weitere Informationen und Risikohinweise findest du auf froots.io.
- FuseRecorded 23 Oct 2026
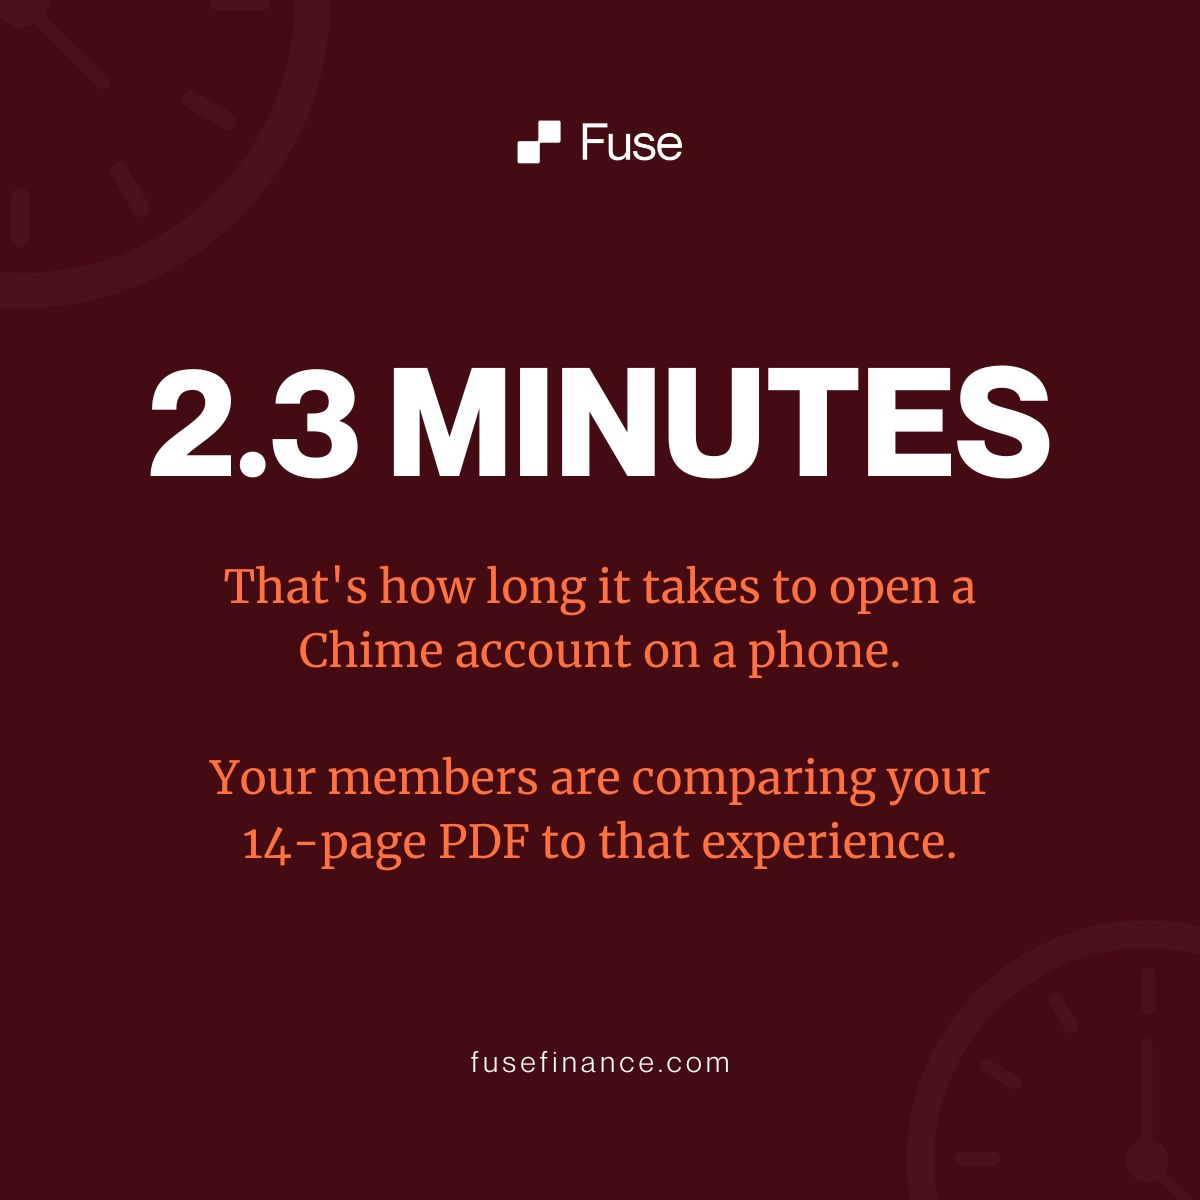
Your members opened a Chime account on their phone in four minutes last year. They remember exactly what that felt like. Then they hit your 14-page PDF on a Tuesday night to apply for an auto loan. The decision happens before they finish the first page. Most of them never finish it. They start somewhere else. PricewaterhouseCoopers ran a study years ago on how consumers actually make lending decisions. Rate matters. The thing that decides is convenience. That study has only gotten more true. A lot of Credit Union leaders I talk to lean on member loyalty to fill the gap. The data says loyalty only goes so far. A slightly worse rate paired with a dramatically faster experience wins every time. What this means changes the strategy. The structural advantages are still there. Member-first culture. Local roots that go back to a church basement and immigrant neighbors lending each other money when nobody else would. The close rate is dying. Your technology is why. We built Fuse to put a Chime-level application inside a Credit Union. The Credit Union part stays exactly what it was. The application runs online and the decision comes back in minutes. The loan officer is still there for the members who want one. Your application is the reason members are going to Chime. Replace it. Send me a DM if you want to see what a Chime-level application looks like running inside a Credit Union. I'll show you the version we built with our clients.
- EOS GroupSince 21 Oct 2026
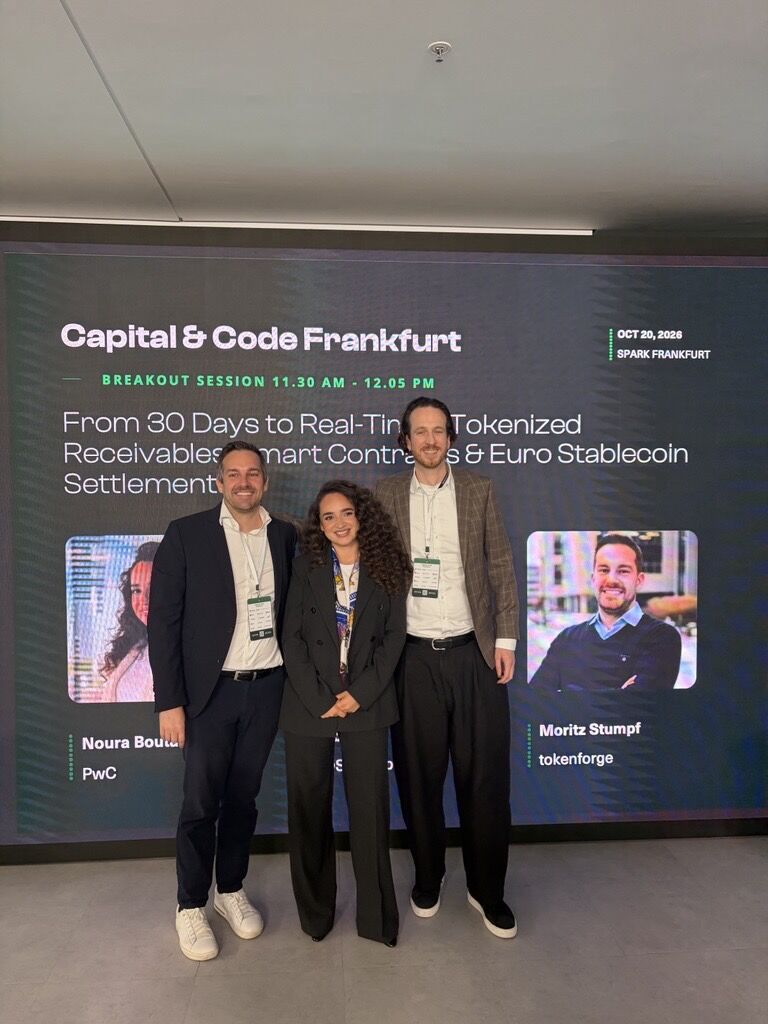
"𝐒𝐞𝐭𝐭𝐥𝐞𝐦𝐞𝐧𝐭 𝐨𝐟 𝐬𝐞𝐜𝐮𝐫𝐢𝐭𝐢𝐬𝐚𝐭𝐢𝐨𝐧 𝐭𝐫𝐚𝐧𝐬𝐚𝐜𝐭𝐢𝐨𝐧𝐬." Sounds rather dry, right? In German, we’d call it "𝐡ö𝐥𝐳𝐞𝐫𝐧." Yet, I was genuinely excited to speak about exactly this topic today at the 𝐂𝐚𝐩𝐢𝐭𝐚𝐥 & 𝐂𝐨𝐝𝐞 conference. Why? Because it brings together two worlds I am deeply passionate about: 𝐒𝐞𝐜𝐮𝐫𝐢𝐭𝐢𝐬𝐚𝐭𝐢𝐨𝐧𝐬: Bundling receivables, structuring them, and channeling them efficiently to investors. 𝐁𝐥𝐨𝐜𝐤𝐜𝐡𝐚𝐢𝐧 𝐓𝐞𝐜𝐡𝐧𝐨𝐥𝐨𝐠𝐲: A secure, tamper-proof ledger that provides trust and transparency. Together with Noura Boutaskiouine and Moritz Stumpf, I had the privilege of presenting our solution. What makes this approach truly exciting is the angle: 𝐖𝐞 𝐚𝐫𝐞𝐧’𝐭 𝐟𝐨𝐜𝐮𝐬𝐢𝐧𝐠 𝐨𝐧 𝐭𝐨𝐤𝐞𝐧𝐢𝐳𝐚𝐭𝐢𝐨𝐧 𝐟𝐨𝐫 𝐭𝐡𝐞 𝐬𝐚𝐤𝐞 𝐨𝐟 𝐢𝐭. Instead, the real breakthrough lies in solving practical challenges: driving efficiency, enabling scalability, and radically simplifying what has traditionally been a manual, paper-based process. A big thank you to the organizers (especially AllUnity) and everyone who joined the session and engaged in the discussion! How do you see the future of post-trade settlement: is distributed ledger technology the missing piece to modernise these processes?
- BackbaseSince 21 Oct 2026
For those who couldn't make it to Backbase ENGAGE in London, I thought I'd share a few of the demos we showcased over the next couple of posts. I'm starting with the Banking OS, because it really ties everything else together. One thing I've noticed from conversations with banks across the region is that technology itself isn't necessarily the problem. Most banks already have plenty of it. The challenge is getting all those systems to work together without adding more complexity every time they want to introduce something new. That's where the Banking OS comes in. It connects customer and employee experiences, banking journeys, workflows, AI agents, and the systems banks already have in place. And to me, that's what makes it interesting. It's not just about improving one journey or launching another digital feature. It's about having the foundation to keep improving and building on what you already have. Here's the Banking OS demo from ENGAGE. Next up, I'll share one of my favorite demos from the event: how banking looks when the experience starts with a conversation rather than navigating through menus.
- BackbaseSince 21 Oct 2026
Imagine opening your banking app and simply telling it what you want to do, instead of going through multiple menus trying to find the right option. That's what caught my attention about the Conversational Banking demo at Backbase ENGAGE in London. And it's the second demo I wanted to share from the event. We've all seen AI chatbots in banking, but most of them are still focused on answering questions or directing customers somewhere else. What's interesting here is that the AI goes a step further. It understands what the customer is trying to achieve, connects them to the right banking journey, and helps them actually get it done. I think that's where things start to get exciting. Because at the end of the day, customers don't really care how many features their banking app has. They just want to get things done quickly and easily. Here's the Conversational Banking demo from ENGAGE. Next, I'll share how this same approach can make a difference in one of the more complex areas of retail banking: investing.
- EOS GroupSince 21 Oct 2026
𝗢𝘃𝗲𝗿 𝘁𝗵𝗲 𝘆𝗲𝗮𝗿𝘀, 𝗜 𝗵𝗮𝘃𝗲 𝗵𝗮𝗱 𝘀𝗲𝘃𝗲𝗿𝗮𝗹 𝗺𝗲𝗻𝘁𝗼𝗿𝘀. And each of them taught me something different. What I valued most was having someone who would challenge me and, when it mattered, speak up for me in rooms I was not in. Having benefited from the generosity of others, I know how much a single conversation can change the course of a career. That is why, when someone asks me for advice, I try to make time. I am glad to pass on my own experiences and perspectives. The best part of being a mentor is that I learn from my mentees just as much as they learn from me. Their questions often give me a new way of looking at things. One in particular has stayed with me: “What did you have to stop doing when you became a manager?” For me, that meant learning to step back: trusting others with work I once did myself and accepting that they may do it differently. I particularly enjoy conversations with colleagues earlier in their careers. Their fresh perspectives on work, technology and leadership are valuable for any leader to hear. #EOSGroup #Mentoring #Networking #Leadership
- FabricAISince 20 Oct 2026
🚀 Mitä pienempi yritys, sitä suuremmalta yksikin vapautunut työpäivä tuntuu. 🚀 Silti kuulen yllättävän usein tämän tyyppisiä kommentteja: 💬Meidän tilitoimisto on niin pieni, ettei teitä varmaan kiinnosta.... 💬On jo tarpeeksi automaatiota… 💬Ei meillä nyt niin paljon ole ostolaskuja… 💬Katsotaan sitten ensi vuonna… Tässä kohtaa otan laskimen esiin. Sillä jo 200 ostolaskun kuukausimäärällä itseohjautuva automaatio voi säästää noin yhdeksän tuntia työtä kuukaudessa. Siis enemmän kuin kokonaisen työpäivän! Olen huomannut, että pienten toimistojen työpöydältä voi hyvinkin löytyä joka kuukausi jopa 700 ostolaskua. Siinä automaatio toisi jo melkoisia mahdollisuuksia merkittäviin ajallisiin ja rahallisiin säästöihin. Entä milloin on oikea hetki lähteä tehostamaan toimintaa automaatiolla? Kun yritys kasvaa? Kun työntekijöillä on kädet täynnä hommaa? Kun kiire alkaa tuntua mahdottomalta? Minusta oikea hetki on juuri ennen. Itseohjautuva ostolaskuautomaatio ei ole vain suurten toimistojen etuoikeus. Pienelle toimijalle yksi vapautunut työpäivä kuukaudessa voi olla suhteessa vielä arvokkaampi kuin suurelle yritykselle. Kun automaation kustannukset skaalautuvat laskumäärien mukaan, ei myöskään tarvitse odottaa sitä, että oma toimisto kasvaisi riittävän suureksi. Siksi sanonkin nyt jokaiselle suomalaiselle tili- ja isännöintitoimistolle: älä vähättele omaa tekemistäsi. Sinullakin on oikeus antoisampaan työpäivään automaation avulla. Jos vielä epäilet, ettei teillä ole tarpeeksi ostolaskuja automatisoitavaksi, niin lasketaanpa ajansäästö yhdessä! Kuvassa Seinäjoen Yrittäjä-Jussin kanssa otettu selfie muutaman viikon takaiselta asiakaskäynniltä. Patsas muistuttaa, että ollaan ylpeästi yrittäjiä, eikä vähätellä itseämme 💪
- Gradient LabsSince 21 Oct 2026
Gradient Labs is a finalist for the Money20/20 banking awards! The Banking Category celebrates the most innovative and impactful products, services, and initiatives leveraging technology, creativity, and strategic vision to solve critical challenges, enhance customer experiences, and drive meaningful change in the banking and financial services sector. Join us in Vegas on October 18th to hear the winners announced!
Other LinkedIn formats
Watch the companies you care about.
Filter every ad by industry, country, format and network, and get alerts when a company you watch starts running new ads.