On air · 2 of 3 networks
Fuse
- fusefinance.com
- Fintech & Financial Services
- US
- 75 employees
Fuse’s ads on LinkedIn, Meta and Google, recorded by adsrunning. Browse the latest here for free. Sign up free to see all 263. Watch Fuse with Starter to get each new one in your feed.
Watchlist with Starter · $49/mo
| Network | Status | Live ads | Nov 2025LinkedIn activity · 52 weeksOct 2026 | Checked | Next step |
|---|---|---|---|---|---|
| Running | 263 | Checked 28 Oct 2026 | See all 263 ads → | ||
| Meta | Not checked | — | |||
| Running | 200+ | Ads on the Google Ads Transparency Center | Checked 30 Oct 2026 | Collect them with the API → |
Fuse has 263 live LinkedIn ads. We recorded 200+ Google ads on 30 Oct 2026.
Latest ads
- LINKEDIN · IMAGERecorded 31 Oct 2026
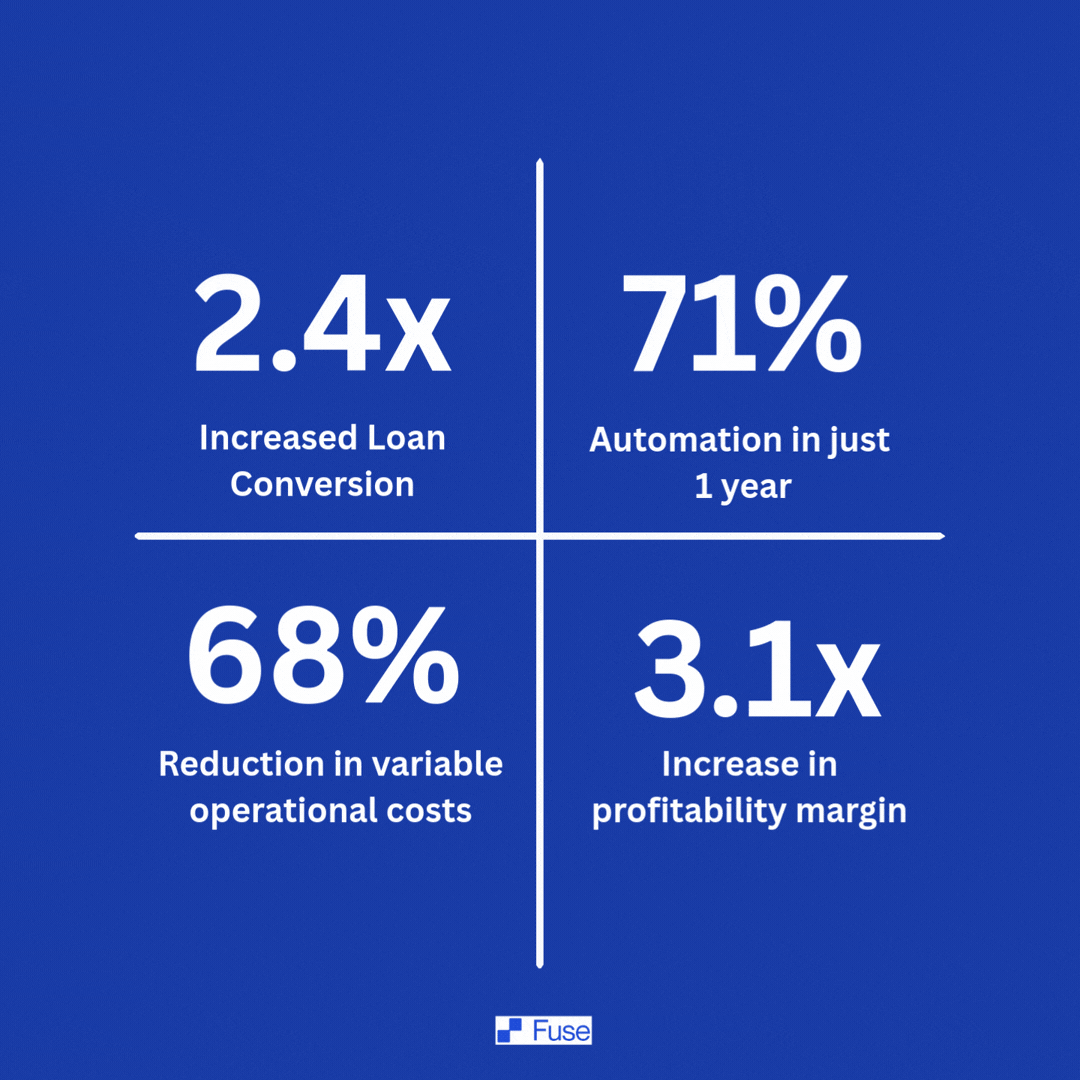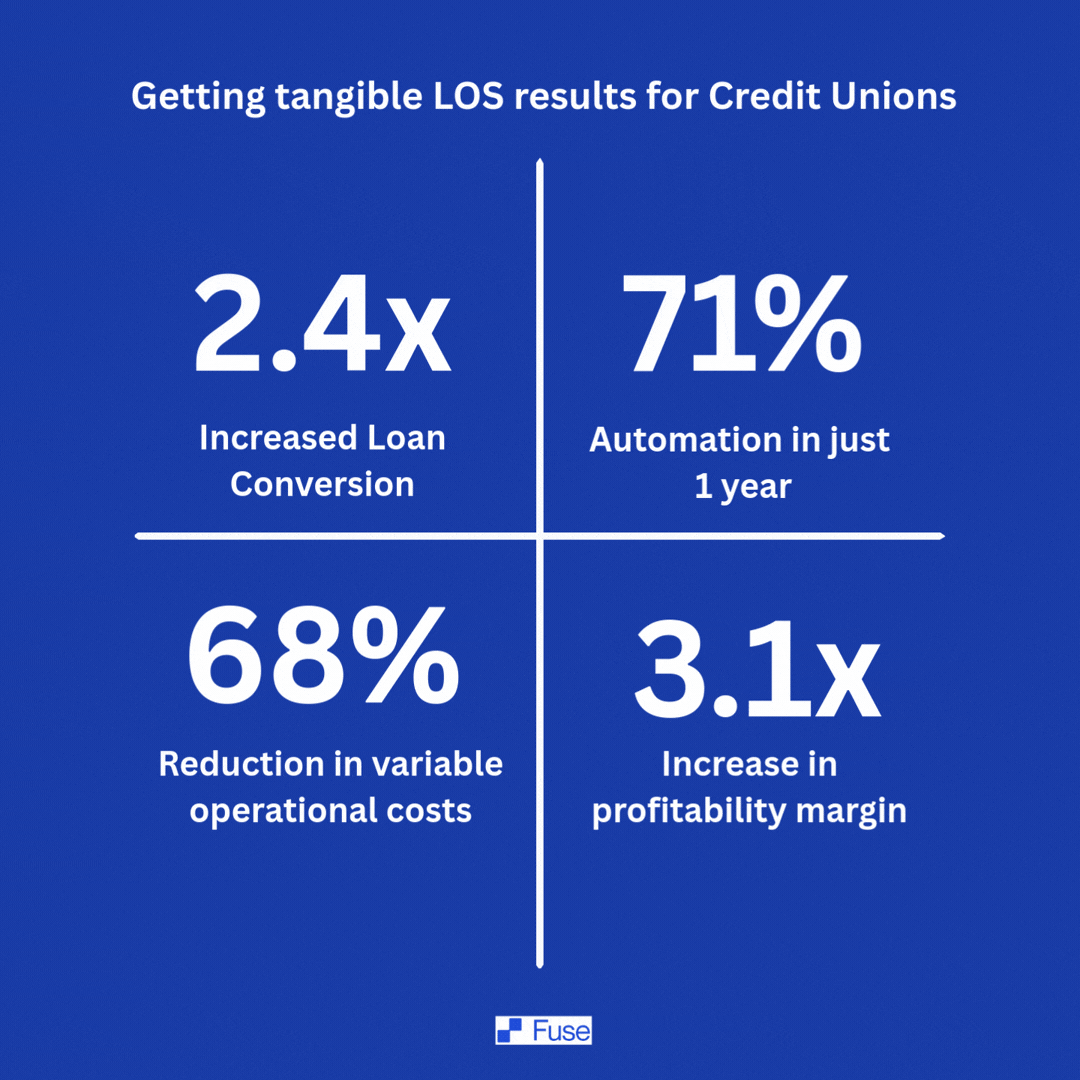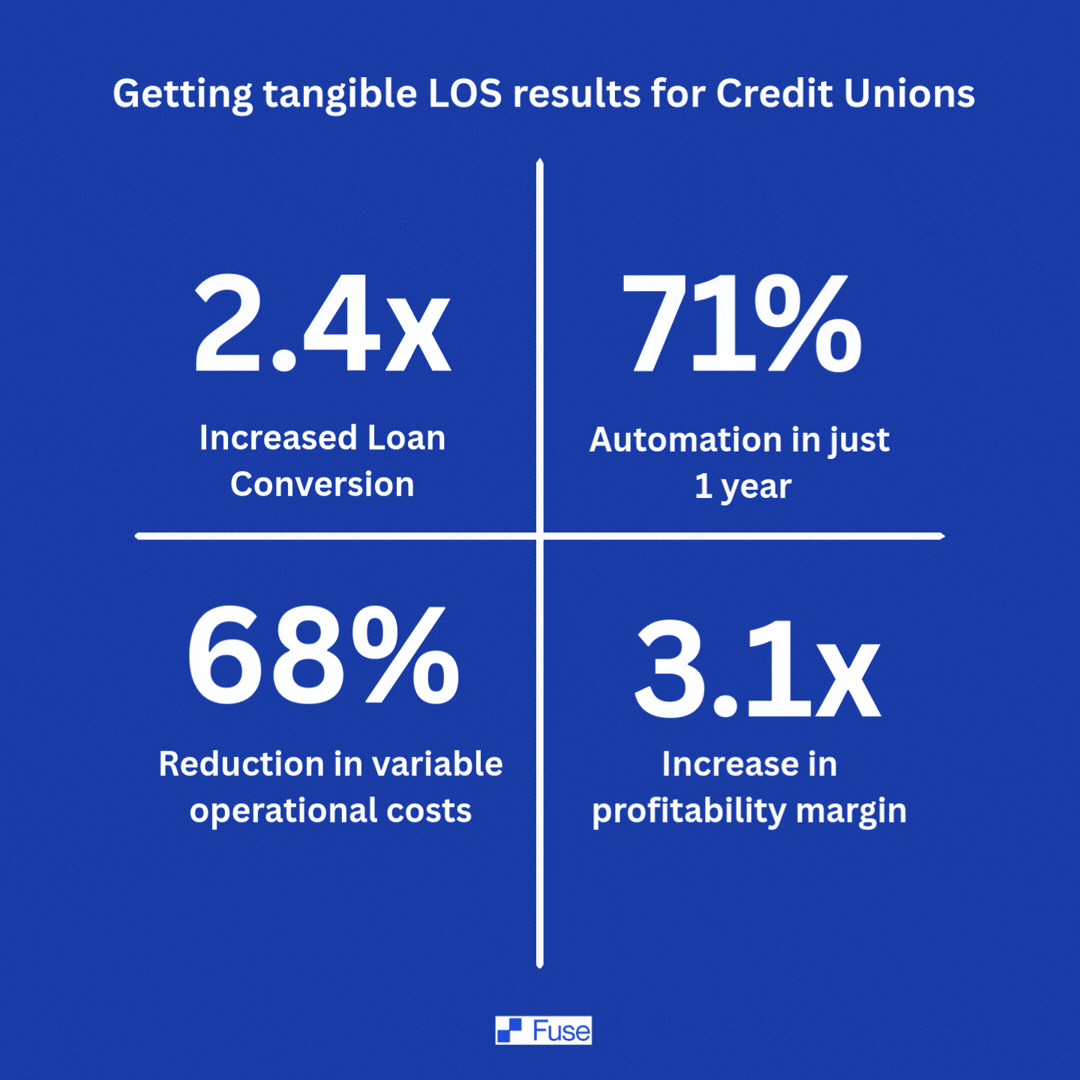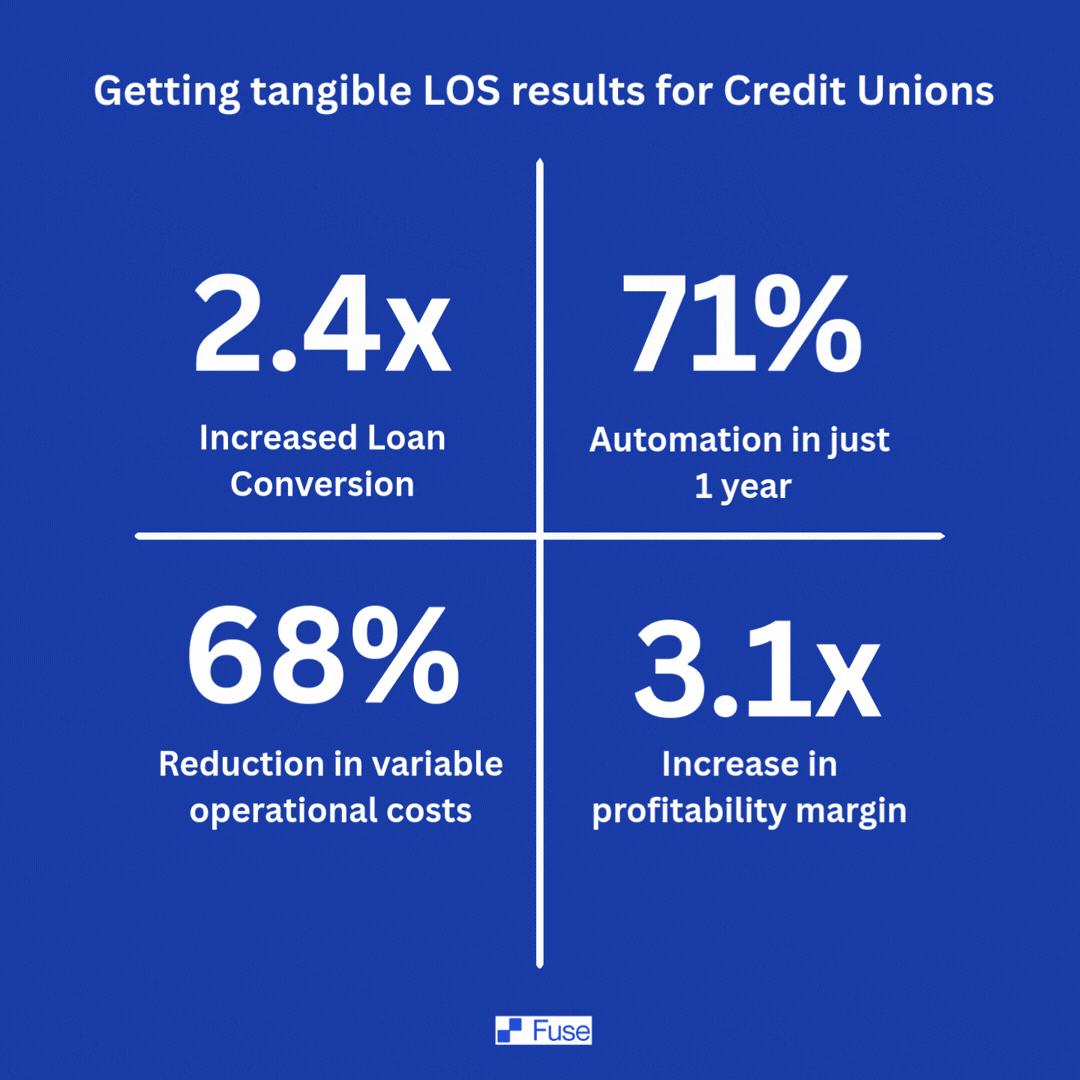
The "Sunk Cost Fallacy" is the most expensive mistake a Chief Lending Officer can make. It’s the quiet killer of Credit Union margins. You sit in those board meetings, feeling the heat of the CEO’s "death glare" while you explain, for the third quarter in a row, why loan volume is flat. You talk about "market conditions," but in the back of your mind, you know the truth. It’s the tech. You’re tethered to a legacy LOS that was sold to you as an "All-in-One" miracle. They promised it would do everything. They lied. What you actually got was a "Blackberry" experience in a Tesla world. A system that requires your team to spend their Saturday mornings performing manual overrides just to get a simple application through the pipes. You’re losing your best loan officers to the fintech down the street because they’re tired of fighting the software. You’re watching members abandon lending pages because a 30-day closing cycle feels like an eternity in 2026. And yet, you stay. You stay because you already cut the check. You stay because you don’t want to admit to the board that the "Innovation Partner" you picked two years ago is actually a boat anchor. But "staying" is costing you more than the contract is worth. You don't need to do this. You can get these results that Fuse is driving: 2.4x Increased Loan Conversion: - Stop letting qualified members slip through the cracks of a clunky UI. 71% Automation in just 1 year: - Imagine 7 out of 10 loans moving through your system without a human being having to touch a single "manual override" button. 68% Reduction in variable operational costs: - This is how you fix the efficiency ratio that keeps you up at 3 AM. 3.1x Increase in profitability margin: - This isn't just a "software upgrade." It’s a fundamental shift in your Credit Union’s math. Fuse gets the pickle you are in. We know you’re locked in. We know you have months—maybe years—left on that legacy contract that’s currently suffocating your growth. We decided to help. We put together the most insane offer ever. We have created a Rescue fund of $5,000,000. Here's how it works: Fuse handles the buyout so you can focus on growth. That's right, we cover the remainder of your contract payments. Stop throwing good money after bad tech. Stop letting a vendor’s failure to innovate become your Credit Union’s ceiling. The $5,000,000 LOS Rescue Fund is specifically designed to pay for your "divorce" from legacy tech. Check your eligibility for the Rescue Fund here: 👉 https://lnkd.in/eSYEM62x
- LINKEDIN · VIDEORecorded 31 Oct 2026
A member applies for an auto loan at 9pm on a Saturday. At most Credit Unions the answer comes Monday. By then the member has taken the offer that arrived first. Fintech lenders went from 5% to nearly 40% of loan market share in 5 years. They answer in minutes, at any hour. Credit Unions answer when the team is in. Hiring for nights and weekends means paying for idle hours, so most don't. That is the Weekend Gap: the loan goes to whoever answered. Today we launched a third option. Experienced U.S. underwriters, on call for nights, weekends and peak volume. Your policy. Your systems. Paid per loan. No platform migration. AI makes our underwriters more productive, so it costs about 50% less than an in house underwriter. If a decision falls outside your policy, the risk is ours, not yours. Live in 3 weeks. Free one month pilot to judge it on your own files. We built Fuse to automate the LOS. The next step is the work around it. With thanks to American Banker for publishing the announcement. Press release in the comments.
- LINKEDIN · VIDEORecorded 31 Oct 2026
The exception nobody tested in the demo doesn't disappear. It waits for the first real file after go-live. Someone on the team finds it, usually because a member calls asking why their file has been sitting for four days. That exception turns into a workaround. The workaround becomes the way one processor quietly handles it, because nobody planned for it to exist in the first place. A year later, three people know the workaround exists. The vendor never hears about it. The Credit Union just built a shadow process around the one thing the demo never showed. What's the last exception your team built a workaround for instead of reporting it?
- LINKEDIN · VIDEORecorded 27 Oct 2026
Every vendor promises results on the call. Ask which ones are in the contract. Fuse writes its commitments into the contract: any integration you need, built free within a month, and every custom field carried over to your core. Every commitment, not just the easy ones.
- LINKEDIN · VIDEORecorded 27 Oct 2026
A credit union already had AI automation. Auto-processing was still stuck at 4%. Six weeks later: 82%. Same team, zero new hires. The AI was doing its job, but processors kept checking its work just in case. The fix: give the AI the same rules your underwriters follow, then take those tasks out of the regular queue. See how Fuse helps credit unions get there.
- LINKEDIN · IMAGERecorded 23 Oct 2026
Your members opened a Chime account on their phone in four minutes last year. They remember exactly what that felt like. Then they hit your 14-page PDF on a Tuesday night to apply for an auto loan. The decision happens before they finish the first page. Most of them never finish it. They start somewhere else. PricewaterhouseCoopers ran a study years ago on how consumers actually make lending decisions. Rate matters. The thing that decides is convenience. That study has only gotten more true. A lot of Credit Union leaders I talk to lean on member loyalty to fill the gap. The data says loyalty only goes so far. A slightly worse rate paired with a dramatically faster experience wins every time. What this means changes the strategy. The structural advantages are still there. Member-first culture. Local roots that go back to a church basement and immigrant neighbors lending each other money when nobody else would. The close rate is dying. Your technology is why. We built Fuse to put a Chime-level application inside a Credit Union. The Credit Union part stays exactly what it was. The application runs online and the decision comes back in minutes. The loan officer is still there for the members who want one. Your application is the reason members are going to Chime. Replace it. Send me a DM if you want to see what a Chime-level application looks like running inside a Credit Union. I'll show you the version we built with our clients.
6 of 263 adsSign up to see every Fuse ad, filter by format and date, and get alerts on new ones.
See all 263 adsWatch the companies you care about.
Filter every ad by industry, country, format and network, and get alerts when a company you watch starts running new ads.