LinkedIn thought leader ad examples
404 thought leader ads are live on LinkedIn right now, from 337 companies. Browse real ones, filtered by industry.
- LucySince 1 Sept 2026
De kans is groot dat je de 120% aftrekbaarheid voor e-facturatie ondertussen al kent. Maar wist je dat die regeling nog loopt tot en met 2027? De meeste ondernemers en accountants hebben ondertussen natuurlijk al lang een Peppol-oplossing gekozen (hoop ik). 😉 Maar misschien ben je vandaag niet 100% tevreden met die keuze. Te veel werk? Te weinig overzicht? Een oplossing die niet helemaal aansluit bij je noden? Of gewoon niet de meest ideale flow voor (al) je klanten? Dan is het goed om te weten dat je nog steeds kan overstappen én gebruikmaken van de verhoogde aftrekbaarheid, zolang je aan de voorwaarden voldoet. In mijn laatste video leg ik uit waarom dit interessant kan zijn en waar je rekening mee moet houden. 💬 Ben jij vandaag 100% tevreden met je Peppol-oplossing, of zijn er nog dingen die beter kunnen? #Peppol #efacturatie #accountancy #fiscaliteit #digitalisering #Lucy
- LucySince 8 Sept 2026
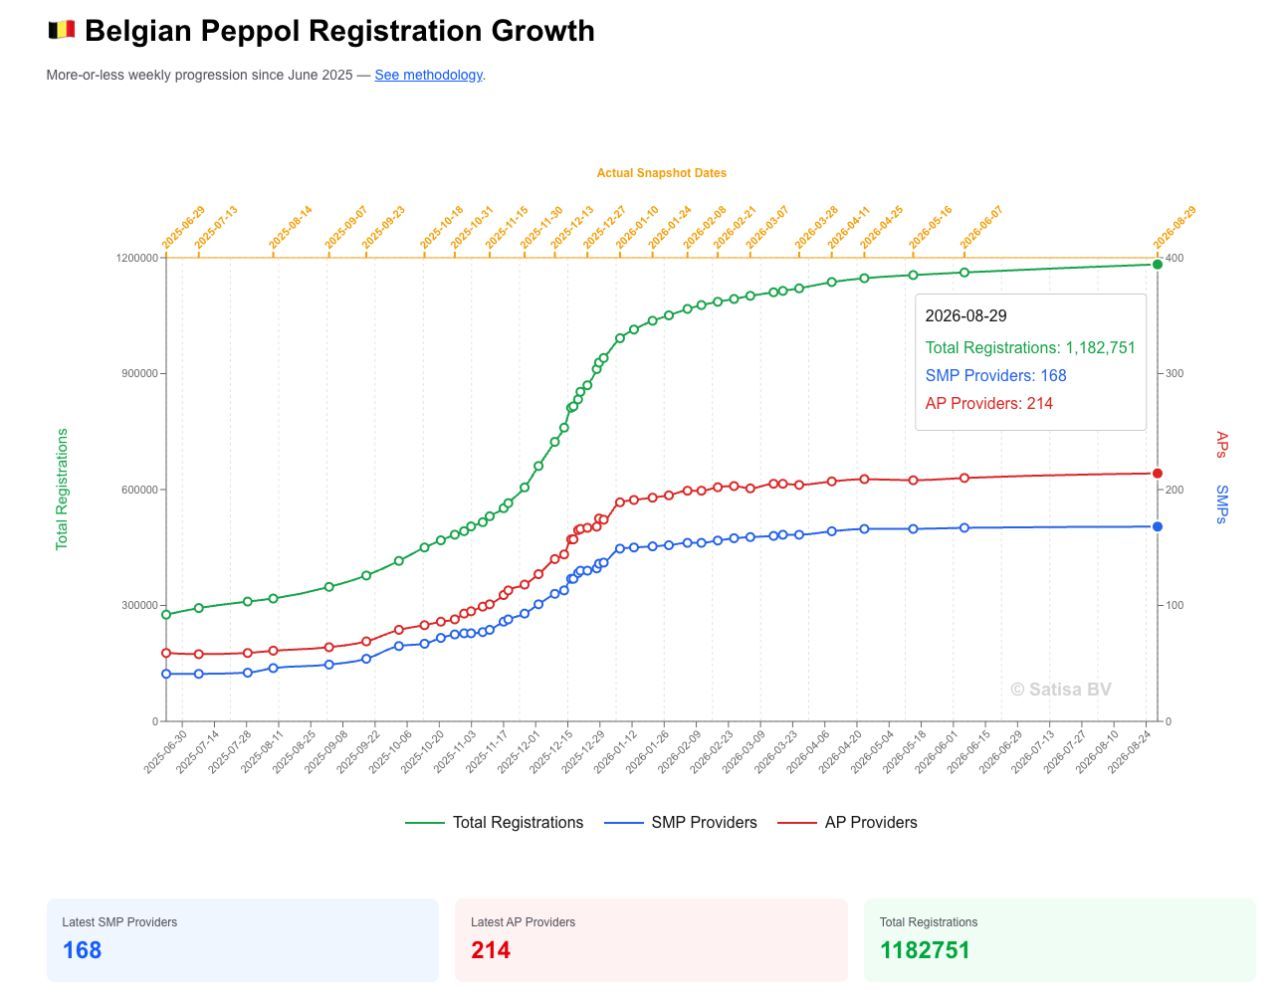
86,8%. 🤯 Dat is volgens de meest recente cijfers van Steven Noels (Mastermind achter peppolcheck.be) het aandeel Belgische ondernemingen dat intussen geconnecteerd is met Peppol. De grote rush is duidelijk voorbij. De golf van eind 2025 en begin 2026 is gaan liggen, en wat we vandaag zien is vooral een veel rustigere, stabiele groei. Best straf als je bedenkt waar we een jaar geleden nog stonden. 🇧🇪 Dankjewel Steven om deze cijfers al die tijd te verzamelen en beschikbaar te maken via PeppolCheck.be. 🙌 De grote Peppol-vraag is ondertussen dus stilaan beantwoord: België is massaal mee. De volgende vraag wordt misschien nog interessanter: wat kunnen we nu écht doen met al die digitale factuurdata? 👀 #Peppol #efacturatie #accountancy #digitalisering #eInvoicing
- EaglSince 14 Sept 2026
Second video in the series: Knowledge. Every finance team has rules about how their books should look. Most of them live in someone's head. "Knowledge" is where they go instead, and how our agents learn them from the way you work.
- EaglSince 14 Sept 2026
A few weeks ago, we put finance professionals in a room with today's AI tools and watched them build. Some of it was prototype-grade, some was genuinely production-worthy. But that's not the point. Finance teams can build now, and I'd push anyone to just start! The ones who do will understand this shift faster than anyone waiting on the sidelines.
- ClairRecorded 20 Sept 2026
At Clair, our product philosophy is built on "fairness." But that principle is truly tested not just when things go right, but also when they go wrong. So we built two features: - For when things go right, we launched a feature that automatically refunds instant transfer fees if an advance is repaid within 12 hours. If you don't get the value, you shouldn't pay the fee. It's that simple. - For when things don't, we built a new Repayment Portal for users who miss a payday. Instead of just locking them out, we give them a flexible, clear path back to financial health. In my new video, I break down both features and how they're key to building a financial system that's on the user's side.
- ClairRecorded 20 Sept 2026
Does adding a financial benefit make your app stickier? The data says yes. When a partner embeds Clair into their app, users trust and like those brands more. We tracked the sentiment, and the results are clear: Over 80% of users say having On-Demand Pay makes their Payroll or WFM app better. It drives engagement (users check the app more often) and loyalty (they feel supported during stressful moments). In this video, I dive into the concept of the "halo effect" of On-Demand Pay - which not only provides a valuable financial tool for people who need it, ODP also enables a better, stickier product for our partners.
- FuelfinanceRecorded 20 Sept 2026
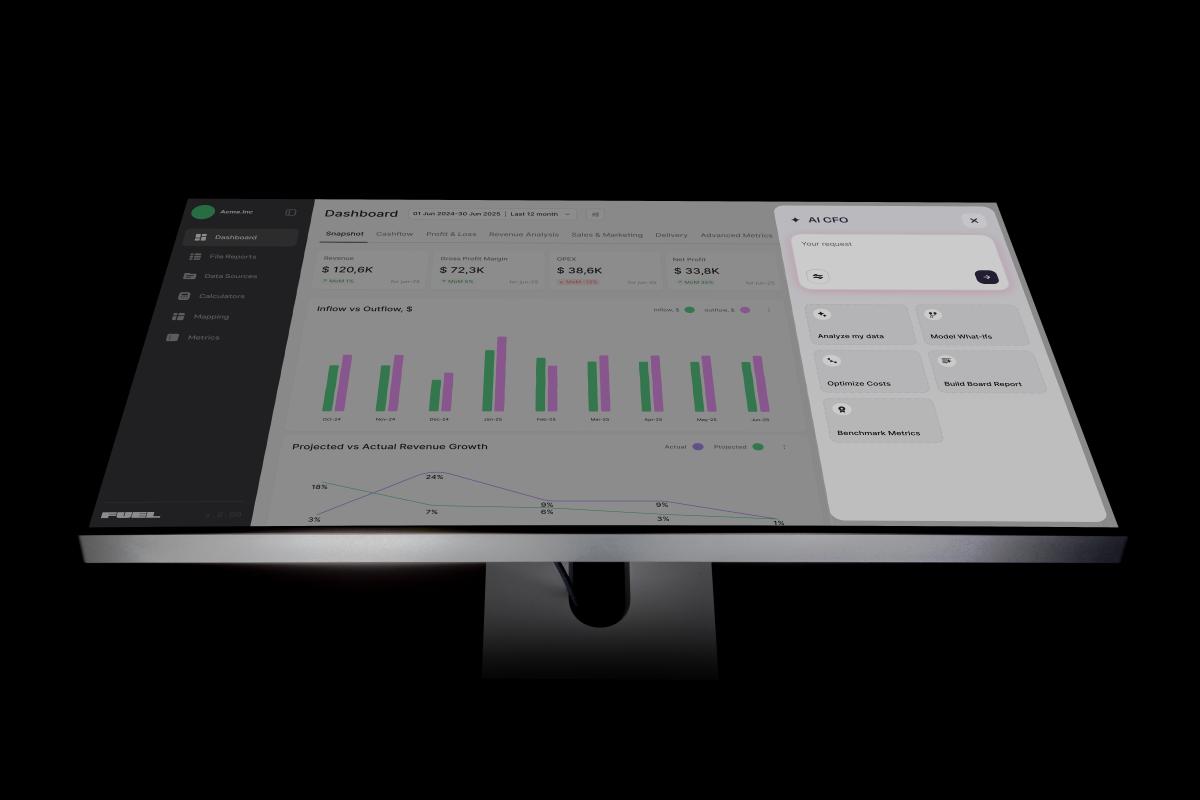
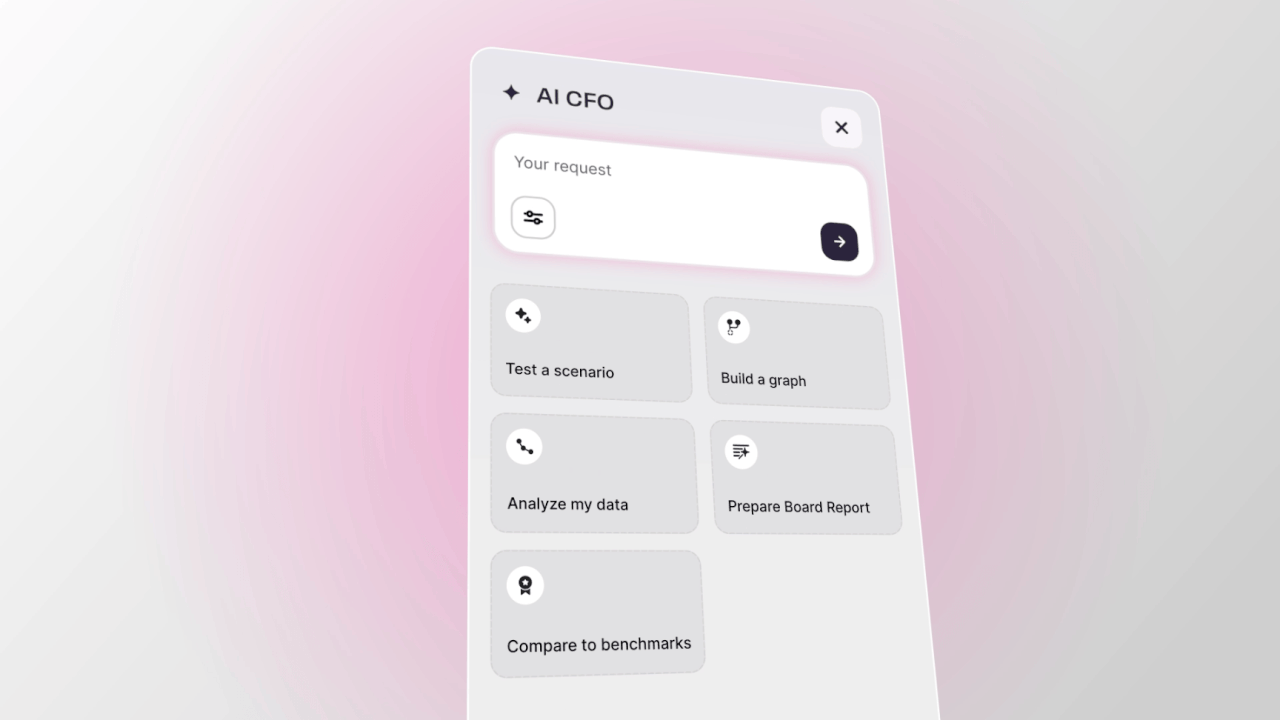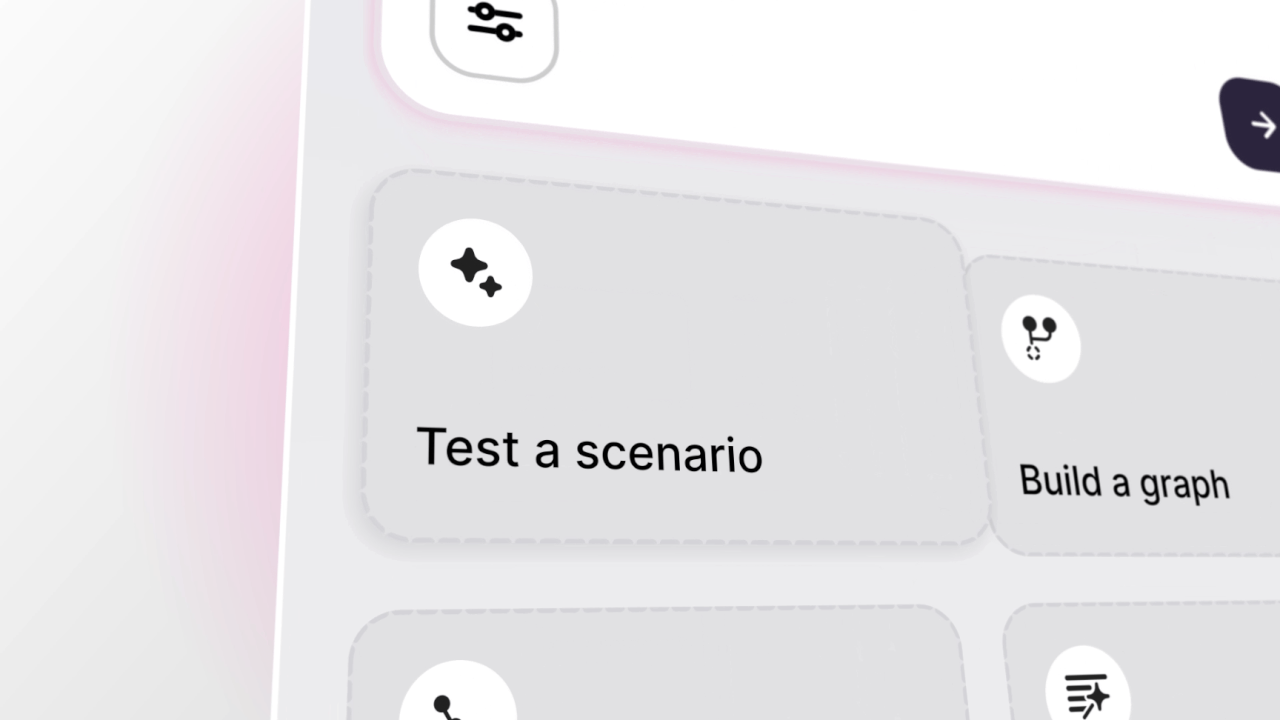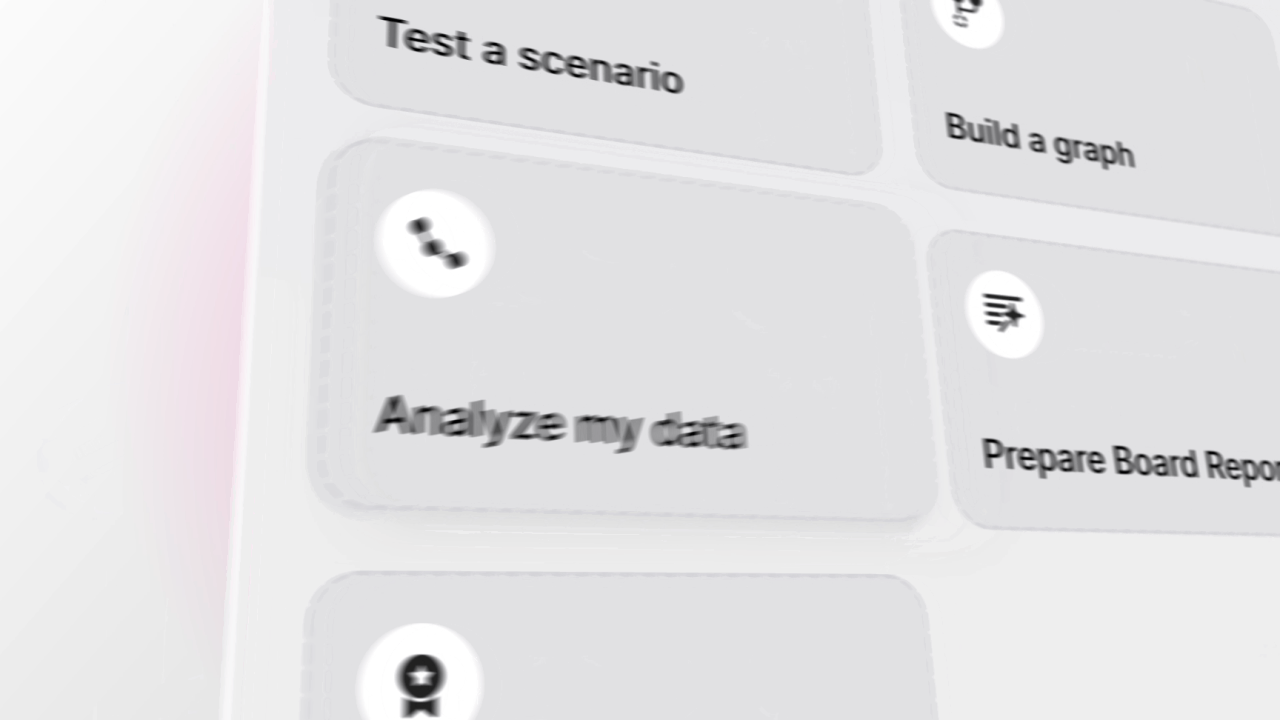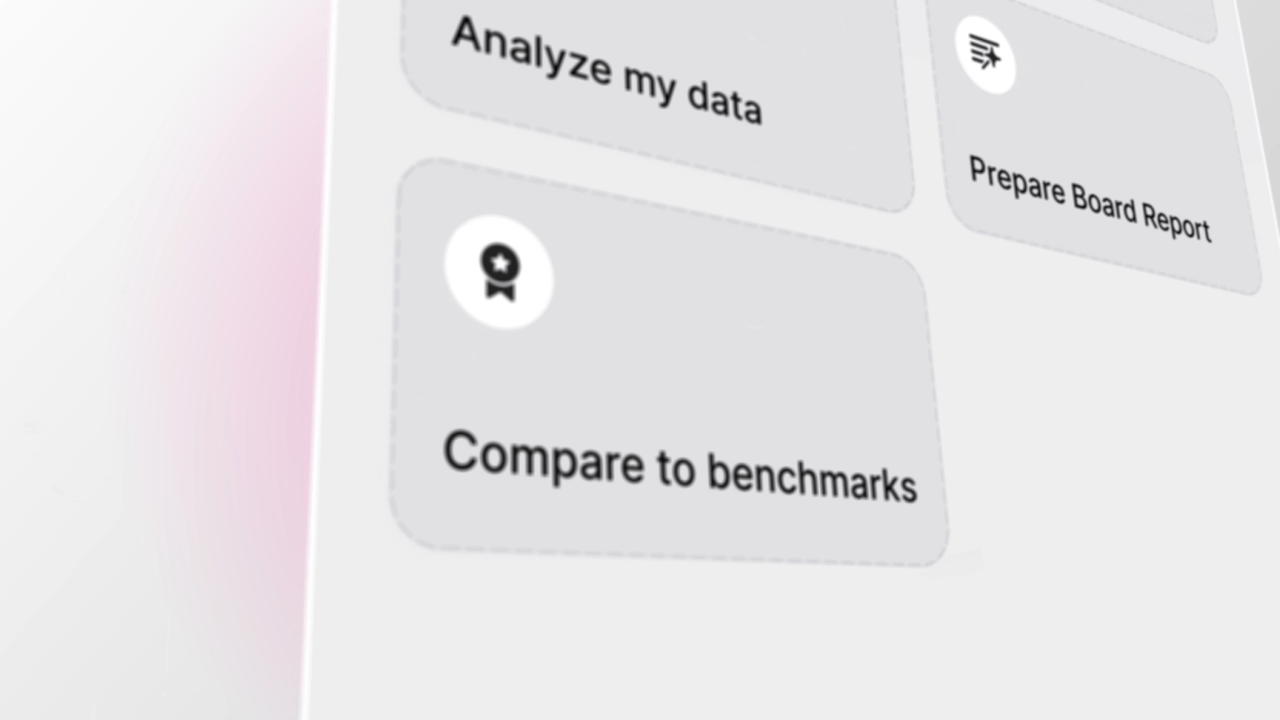
just introduced: FUEL AI CFO the lovable/cursor for midsize businesses’ finances. get early access at https://lnkd.in/gx95mJzt
- FuelfinanceRecorded 20 Sept 2026
💚 10 principles we use to build reliable AI CFO 💚 1. All the data in one warehouse — clean and ready for AI. We take all your data from 300+ sources like QuickBooks, Stripe, HubSpot, banks, payroll, etc. 2. Accuracy > 1-click. Training agents using your data, not just general data. In finance AI to have the highest accuracy — less is more. 3. Human-backed. Trained on thousands of founder↔CFO questions and continuously validated by our in-house finance team. 4. Full transparency. Data Limitation Disclaimer shows the quality score (e.g., 40/100) and marks insights as directional until validated. 5. Proactive anomaly checks. Fuel flags issues the moment they appear (missing dates, mismatched invoices, odd entries) — before they become bad answers. 6. Root-cause + actions tips. When something drifts off target, Copilot explains why it happened and gives a clear fix-it playbook you can follow. 7. Built for your industry. SaaS, agencies, ecommerce, consulting — knows the metrics and benchmarks that matter. 8. Decision safeguards. When data is thin, Copilot widens confidence bands, de-scopes risky analyses, and prompts data-fix steps before action. 9. Auditability, always. Every conclusion is tied to the exact sources, time range, and transformations used — so finance can double-check. 10. One platform. Built into the Fuel FP&A stack (what-ifs, dashboards, alerts) so your planning, analysis, and actions stay consistent. Get early access at https://lnkd.in/gx95mJzt
- FynancialRecorded 20 Sept 2026
How many passwords have you reset this year? "C'mon, man!" - Joe Biden It's 2025, and you should know that in 2026 and beyond, you can tell your clients... "Just go to the app for everything." It's simple. It's easy, and it might be exactly what your clients are looking for.
- fincrm GmbHSince 9 Jan 2026
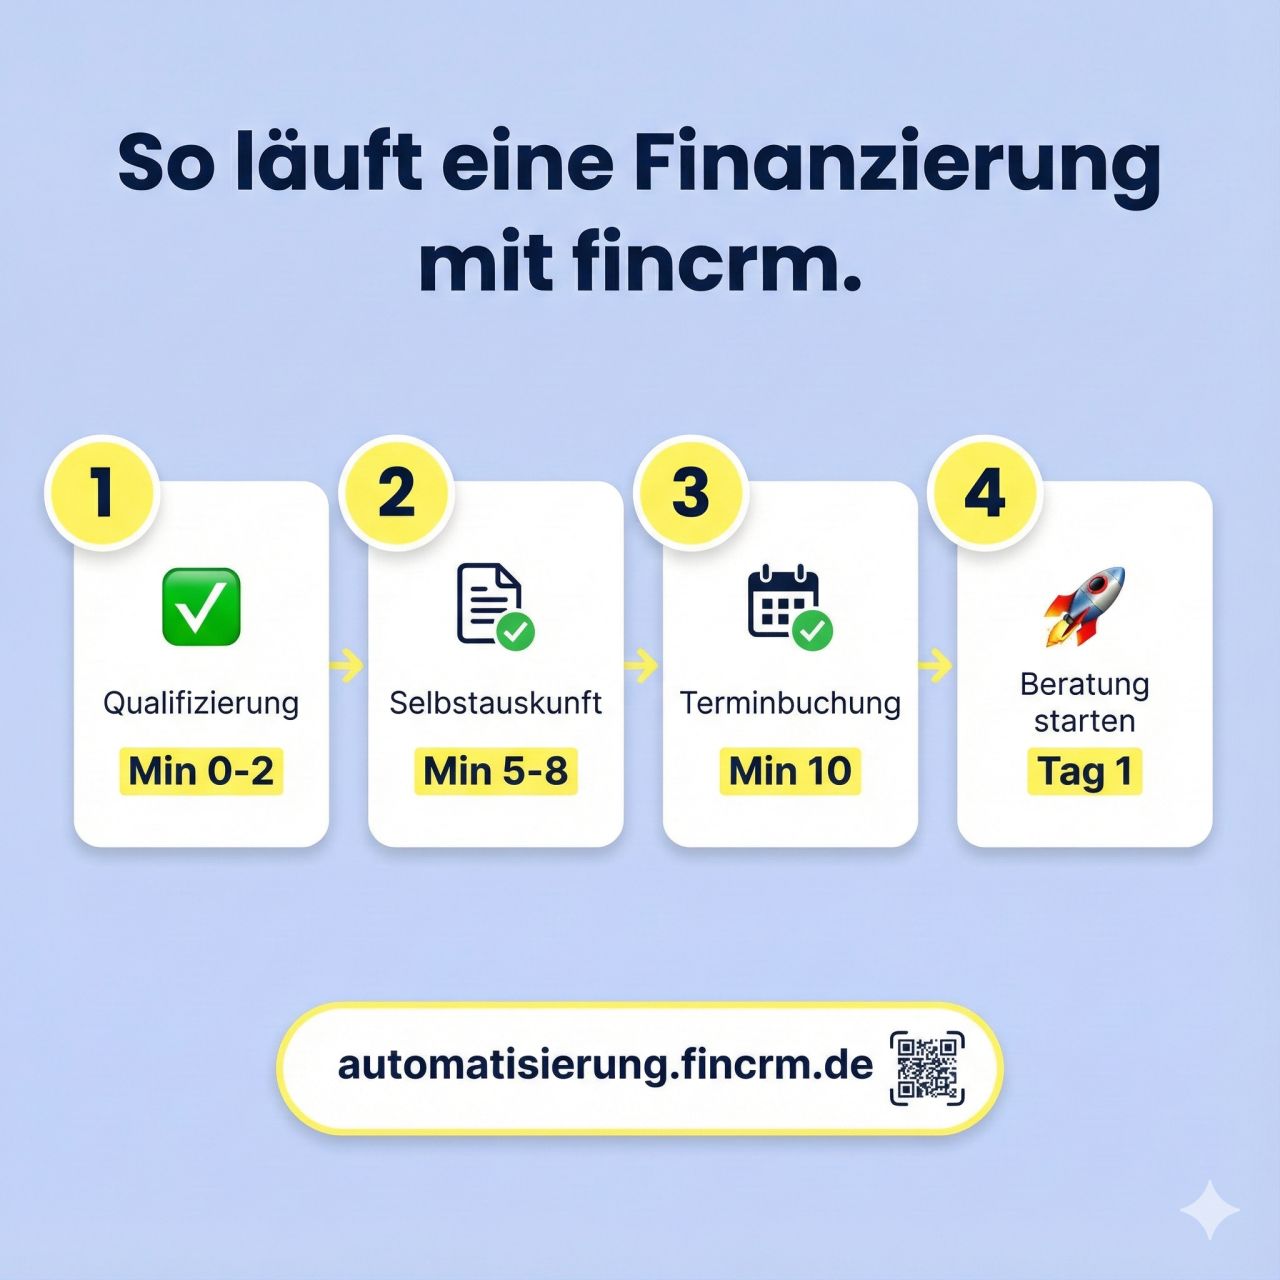
🎯 Freitag, 19:30 Uhr – kennst du das? Ich saß noch im Büro und tippte handschriftliche Selbstauskünfte ab, während meine Familie schon wartete. Als Baufinanzierungsberater war das Alltag: Erstkontakt, E‑Mail‑Ping‑Pong, Tage warten, unvollständige Daten, endloses Nachfassen. Ergebnis: 7–12 Tage bis zum ersten Termin und 35–40 % Leads sprangen ab. Heute helfe ich bei fincrm, damit du nie wieder so arbeiten musst. 🔁 Der alte Prozess vs. der neue Flow Minute 0–2: Automatisierter Chatbot qualifiziert den Interessenten. Minute 5–8: Der Kunde füllt selbst die digitale Selbstauskunft aus – keine Papierformulare mehr. FinCRM bietet einen sicheren Datenaustausch, eine digitale Selbstauskunft und eine einfache Terminvereinbarung . Minute 10: Termin landet automatisch in deinem Kalender. FinCRM bündelt alle Kundenanfragen und die komplette Kommunikation an einem Ort und synchronisiert Daten über deine Systeme . Tag 1: Du startest die Beratung – mit vollständigen, strukturierten Daten im CRM. 🚀 Die Ergebnisse sprechen für sich Von 7–12 Tagen auf < 24 Stunden Bearbeitungszeit. Die Conversion steigt von 60 % auf > 85 %. Du sparst 45–60 Minuten pro Lead. 🧭 Warum ich gewechselt habe Ich wollte genau das System, das ich mir damals gewünscht hätte: Keine manuellen Eingaben mehr. Keine unvollständigen Auskünfte. Keine abgesprungenen Leads. Mit FinCRM erhältst du ein smartes CRM für Baufinanzierungs‑ und Kreditvermittlungsteams. Alle Leads, Dokumente und Termine werden zentral verwaltet . Die Kunden können sicher Dokumente hochladen, digitale Selbstauskünfte ausfüllen und Termine buchen . Dadurch verbringst du deine Zeit wieder mit dem, wofür du Berater geworden bist: Beraten und Abschlüsse machen. 💡 Möchtest du wissen, wie das in deinem Unternehmen funktioniert? 👉 automatisierung.fincrm.de – vereinbare deine kostenlose Automatisierungs‑Analyse. Wir schauen uns gemeinsam deinen Prozess an und zeigen dir konkrete Schritte, wie du ihn optimierst. 👉 Wo verlierst du aktuell am meisten Zeit? Teile es gerne in den Kommentaren! Lukas HarterDavid Neukirchen
- fincrm GmbHSince 23 Feb 2026
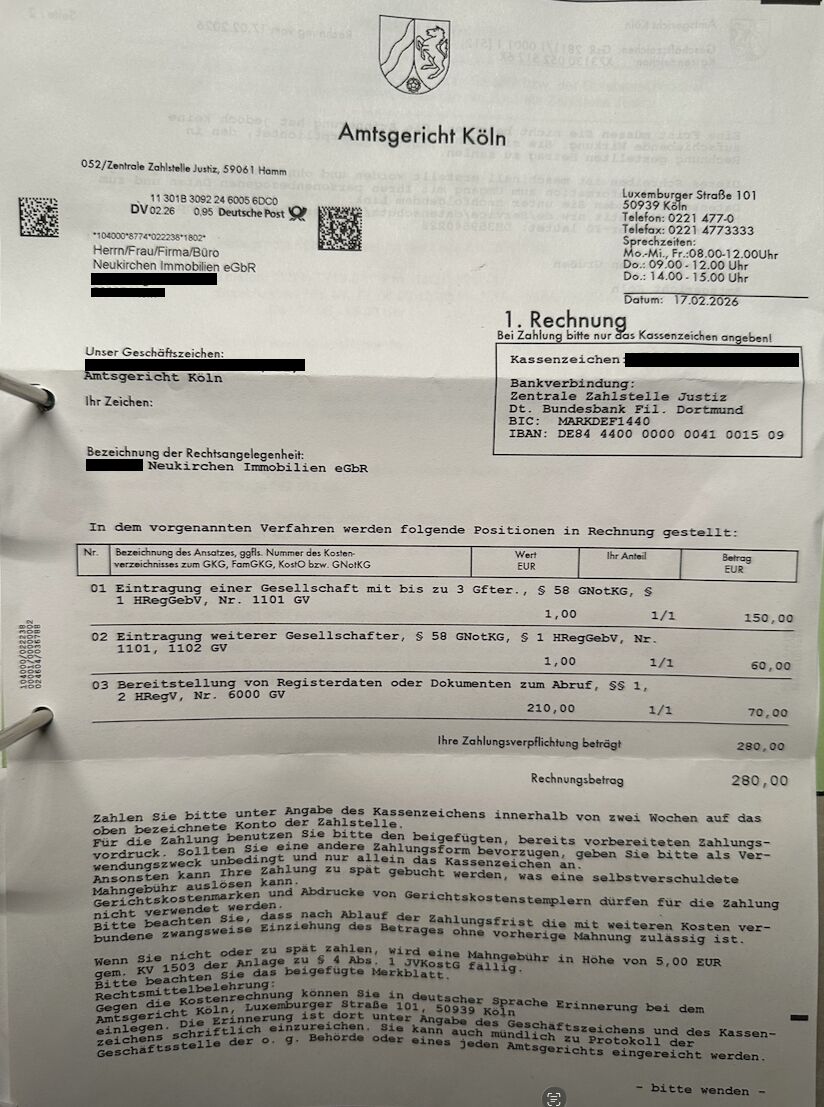
Ist das wirklich der richtige Weg? Ich habe kürzlich eine Immobilien eGbR eintragen lassen. Jetzt kam die Rechnung vom Amtsgericht – ein paar hundert Euro. Und mein erster Gedanke war nicht: „Okay, überweisen.“ Sondern: „Ist die echt?“ Also werde ich anrufen und mich absichern. Nicht weil ich übervorsichtig bin, sondern weil es inzwischen gängige Masche ist, Registereinträge auszunutzen und täuschend echte Rechnungen zu verschicken. 🤔 Und genau das hat mich nachdenklich gemacht. Wir sprechen täglich über #Digitalisierung, #KI und #Effizienz. Banken bauen massiv Filialen ab. Prozesse werden vollständig digitalisiert. Aber gleichzeitig steigen die Betrugsfälle. Und sie werden professioneller und perfider. Weder technische Schutzmaßnahmen noch das Bewusstsein der Verbraucher können bei der Geschwindigkeit mithalten. DER SPIEGEL Podcast Firewall deckte kürzlich eine besonders krasse Masche auf: 1️⃣ Fake-Werbung lockt die Opfer in Chatgruppen 2️⃣ Dutzende Bot-Accounts diskutieren dort mit den Opfern über Aktien, Trading-Tipps, aber auch Privates und Alltägliches. 3️⃣ Digital geklonte „Experten“ geben plausible Tipps & Workshops. 4️⃣ Das Ganze läuft über Wochen und Monate. 5️⃣ Erst entsteht Vertrauen, dann verschwindet das Geld. Und am Ende: Boom. 80.000 € weg. 🧨 Enormer technischer und zeitlicher Aufwand – perfekt inszeniert. Aber zurück zur eigentlichen Frage: Ich arbeite täglich digital. Ich atme Digitalisierung. Und trotzdem habe ich gezögert eine einfache Rechnung zu begleichen. Ist dann der konsequente Rückzug aus der persönlichen Beratung wirklich die richtige Strategie? Vielleicht wird in einer Welt mit perfekter digitaler Täuschung genau das wieder wertvoller, was wir gerade massiv abbauen: 🙋 Ein Ansprechpartner, der Verantwortung übernimmt. 🏦 Lokale Präsenz. 🤝 Persönliche Vertrauensverhältnisse. Digitalisierung ist richtig und wichtig. Aber Vertrauen bleibt die gemeinsame Basis. Ich lehne mich aus dem Fenster und sage: Persönliche Beratung wird nicht ersetzt. Sie wird wichtiger als je zuvor. Je einfacher und besser die digitale Täuschung wird, desto wertvoller wird die echte menschliche Interaktion. Genau deshalb glauben wir bei fincrm GmbH nicht daran Beratende zu ersetzen, sondern fokussieren uns darauf sie digital zu stärken. 👉 Wie siehst du das? Wird die persönliche Beratung in Zukunft überflüssig oder dürfen wir diejenigen Menschen, die im Stande sind, Kunden vertrauensvoll zu begleiten nicht verlieren?
- FinampSince 27 Mar 2026
The UK stablecoin moment is no longer theoretical. The harder question now is execution. A year ago, many founders still treated stablecoins as a future option for UK fintech. That is changing. HM Treasury has published draft legislation for a broader UK cryptoasset regime that includes stablecoin issuance as a regulated activity. The FCA has opened a dedicated stablecoin sandbox cohort and set stablecoin payments as a 2026 priority. The Bank of England has also consulted on the regime for systemic sterling stablecoins. That does not make launch easy. It makes product discipline more important. Stablecoins only become commercially useful when they solve a real payment problem: cross-border movement, treasury flows, B2B settlement, platform payouts. And once a team moves from concept to launch planning, the same questions show up very quickly: Where is the money now? What state is the transaction in? What can still fail or reverse? How is redemption handled? What exactly will support say if the customer asks what happened? This is where many teams underestimate the work. A stablecoin product still needs payment-grade clarity. The customer has to understand balances, state changes, fees, conversion points, and what “completed” actually means. Support and operations need the same transaction story the user sees. Partner architecture also gets more complex fast, because most teams will rely on several providers across wallet infrastructure, compliance, fiat rails, custody, and reporting. The strongest UK stablecoin products will probably feel less like crypto products and more like very well-designed payment products. That usually means: clear state models, visible transition points, strong internal event trails, and product flows that hold up under real operational scrutiny. The opportunity is real. The execution bar is rising just as fast. 👉Book a Call with Finamp: https://lnkd.in/eqXZuzSS Read more here 👇https://lnkd.in/essQgUcn #UKFintech #Stablecoins #Neobank #Payments #FintechMVP #DigitalBanking #ProductStrategy #CryptoRegulation
- FinampSince 13 Apr 2026
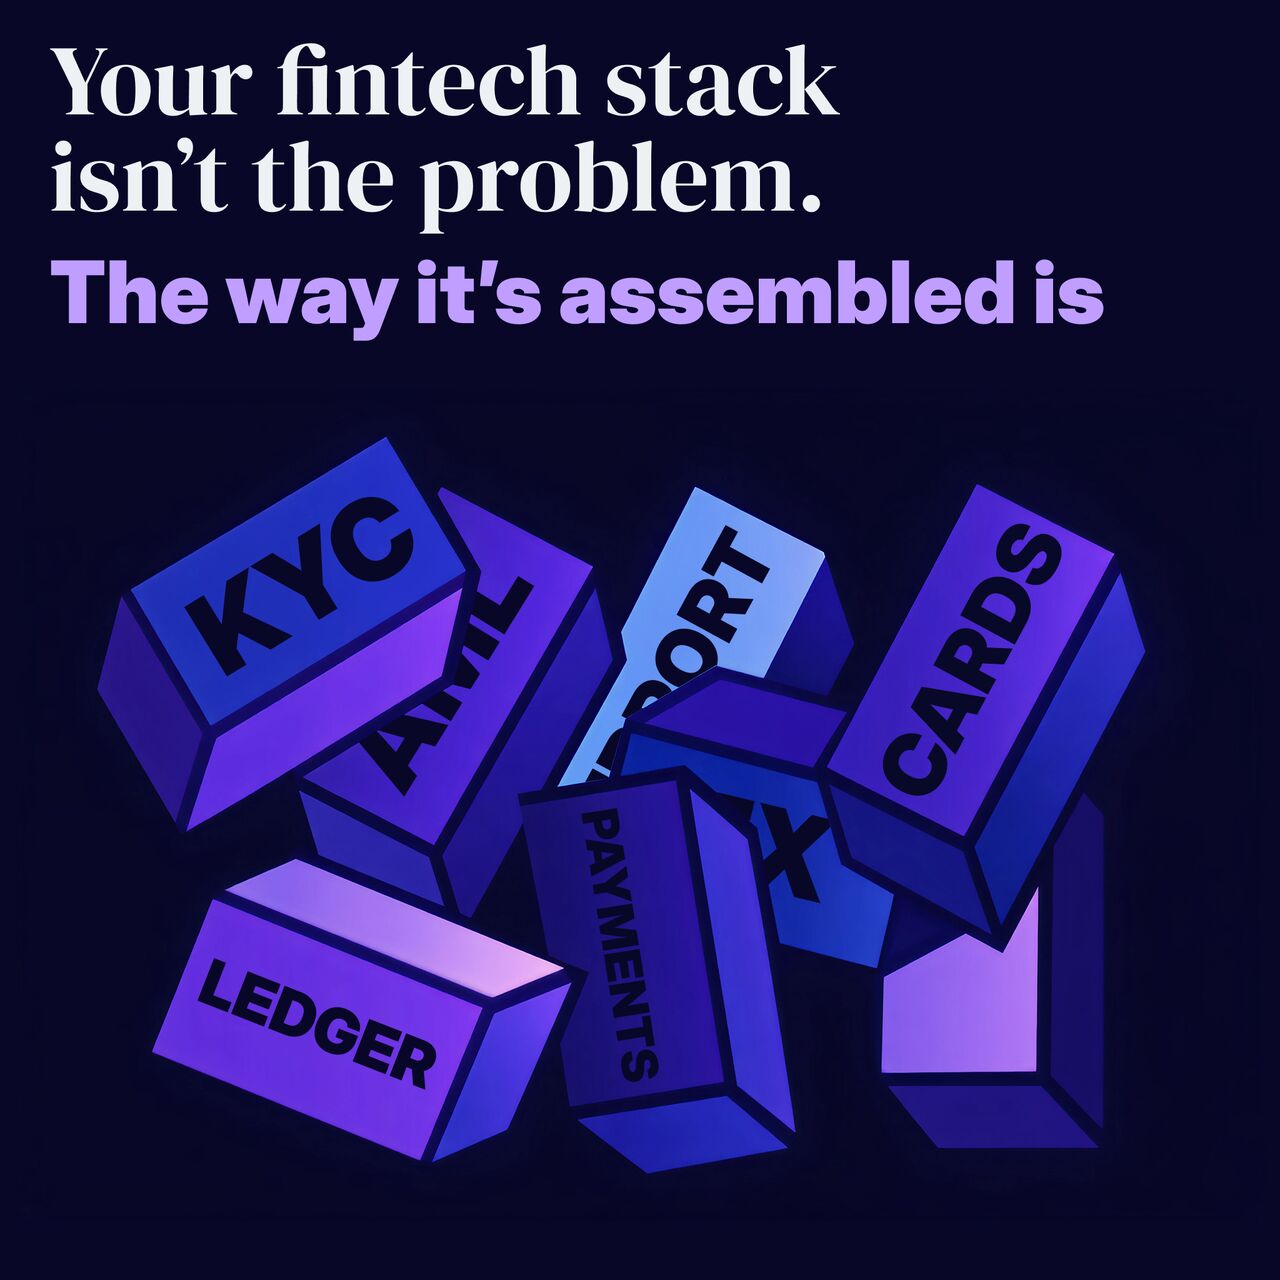
Most fintech products are assembled long before they feel unified. Cards, KYC, payments, ledgers, notifications, support tooling. The real question is whether those pieces were assembled into a platform that can survive change. A modular approach matters because fintech rarely stands still. Providers change. Markets expand. Regulations shift. New corridors and workflows appear. When the product is tightly fused to one provider or one early setup, every change starts looking like a rewrite. When the product layer stays stable above the component layer, teams get a much cleaner upgrade path. That is where modularity becomes more than a technical choice. It gives the business room to replace weak components, add new ones, and scale specific parts of the stack without destabilising the whole product. Customers still see one coherent experience, even while the infrastructure underneath keeps evolving. The strongest fintech platforms are not built as one giant system. They are assembled with clear boundaries, stable product logic, and enough structure to absorb change without losing control. 👉 Book a Call with Finamp: https://lnkd.in/eqXZuzSS #Fintech #Neobank #FintechMVP #ProductStrategy #DigitalBanking #Payments #BaaS #Architecture
- Folks FinanceSince 16 Jul 2026
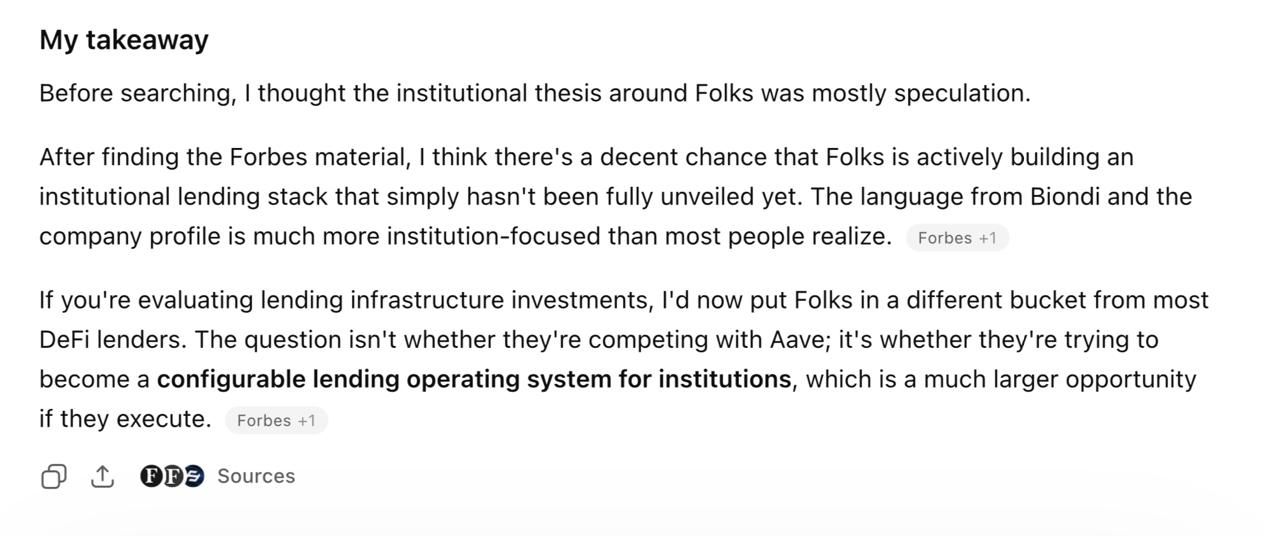
Typed "Folks Finance" into an AI. Wasn't expecting this. We haven't been very loud about what we're building because we've always preferred to build before speaking. But the AI isn't wrong here. So far, DeFi has mostly been about products built for individual crypto users. What we're actually building is infrastructure that also enables institutions to come onchain and power their financial use cases. That's where the biggest opportunity lies for DeFi in the next months and years.
- finperksSince 20 Jul 2026
I talked gift cards with the fashion giant, Zalando 🛒 Dr. Moritz Zoellner is the mastermind behind it. Active across 25 European countries with 62 million active customers and €12.3 billion in revenue in 2025, no other fashion platform in Europe comes close. Zalando's loyalty programme alone reached 16.8 million members. We talked gift cards for an hour. When I, as a distributor, ask partners what matters most, the answer is usually some version of the same mix: reach and not having to manage ten different integrations. 🟣 Not just volume, but the right channels. Banks, HR platforms, insurance companies, payment providers etc. Consumers who are already in a spending mindset. Brands want high-trusted channels where people manage their money. Logging in to check their balance, review their payslip, or manage their account, where a relevant brand offer lands as useful, not intrusive. 🟣 Operational simplicity. The traditional model requires brands to negotiate separately with every gift card distributor, in every market, for every new channel. finperks inverts that. We have the channels, in the pipeline across 30 markets in Europe, with partners already reaching millions of consumers in DACH, Italy, etc. We just need your approval to put you as a brand there. And the Consumer experience follows. On our partner apps, users see 6% platform-subsidized payment at Zalando before they buy a prepaid/gift card. It's an extra something the client offers, while the Brand loses nothing. We, at finperks, want to become the first distributor that support partners in expanding to 30+ markets, putting them in global high-trust, high-growth channels. Always great to meet up with you and chat about the real stuff 🚀 Are you a brand wanting to expand your reach with gift cards in high-growth, unconventional channels? We have something for you 🚀 Let's talk: https://lnkd.in/eqz3N_Gf
- finperksSince 20 Jul 2026
Building my second company finperks right now. The first transaction just hit different. This was a while ago, but I still live on that high 🙂 The first time money moves through infrastructure you built from scratch, it lands differently. Here's what we're solving: Fintechs kept trying to add gift card rewards to their apps and hit the same wall every time: → Minimum 3–5 supplier contracts before you can go live → Brand approvals that take weeks per partner → A different VAT framework for every market you enter → No shared infrastructure, every integration rebuilt from zero The problem was never the gift card itself. The problem was that the distribution layer between Brands and Digital Channels was never built for scale 💪 One integration. Brands go live across multiple digital channels without rebuilding the pipe each time. We just ask for their approval when we have a new client/partner and they need to tell us yes or no. Tap, tap and gift card redeemed inside a payment app. Done. The gift card market is a $300+ billion category. Most of the infrastructure still runs like it's 2005. That's the gap we're filling 💪
- Folks FinanceSince 29 Jul 2026
𝗠𝗼𝗻𝗲𝘆 𝗶𝘀 𝘁𝗵𝗲 𝗼𝗻𝗲 𝘁𝗵𝗶𝗻𝗴 𝗴𝗹𝗼𝗯𝗮𝗹𝗶𝘇𝗮𝘁𝗶𝗼𝗻 𝗹𝗲𝗳𝘁 𝗯𝗲𝗵𝗶𝗻𝗱. 𝗛𝗲𝗿𝗲'𝘀 𝘄𝗵𝘆 𝘁𝗵𝗮𝘁'𝘀 𝗳𝗶𝗻𝗮𝗹𝗹𝘆 𝗰𝗵𝗮𝗻𝗴𝗶𝗻𝗴. The internet is global by default. Send a message to anyone on the planet instantly. Access the same information as everyone else. But 1.3 billion adults still don't have a financial account. International transfers are slow, expensive, or simply inaccessible depending on where you live. Here's how the financial system got here, and what's actually changing it (from my latest Forbes article) 👇 1️⃣ 𝗧𝗵𝗲 𝘀𝘆𝘀𝘁𝗲𝗺 𝘄𝗮𝘀 𝗻𝗲𝘃𝗲𝗿 𝗯𝘂𝗶𝗹𝘁 𝘁𝗼 𝗯𝗲 𝗴𝗹𝗼𝗯𝗮𝗹. Country by country. Bank by bank. Then stitched together through correspondent banking and middleware. The result: a patchwork pretending to be a network. 2️⃣ 𝗜𝗻𝗰𝗿𝗲𝗺𝗲𝗻𝘁𝗮𝗹 𝗶𝗺𝗽𝗿𝗼𝘃𝗲𝗺𝗲𝗻𝘁 𝗰𝗼𝘂𝗹𝗱𝗻'𝘁 𝗳𝗶𝘅 𝗶𝘁. Faster wires. More branches. Better online portals. For decades the industry tried to patch the problem without changing the foundation. The electric light didn't come from the continuous improvement of candles. 3️⃣ 𝗥𝗲𝗮𝗹 𝗰𝗵𝗮𝗻𝗴𝗲 𝗿𝗲𝗾𝘂𝗶𝗿𝗲𝘀 𝗻𝗲𝘄 𝗶𝗻𝗳𝗿𝗮𝘀𝘁𝗿𝘂𝗰𝘁𝘂𝗿𝗲. Onchain financial rails are global from inception, not stitched together afterward. The same properties that made the internet powerful: instant, borderless, accessible to anyone with a phone. 4️⃣ 𝗦𝘁𝗮𝗯𝗹𝗲𝗰𝗼𝗶𝗻𝘀 𝘄𝗲𝗿𝗲 𝘁𝗵𝗲 𝗳𝗶𝗿𝘀𝘁 𝗽𝗿𝗼𝗼𝗳. Last year they processed more transaction volume than Visa and Mastercard combined. Not as a speculative asset. As a financial rail that actually works globally, today. 5️⃣ 𝗡𝗼𝘄 𝘁𝗵𝗲 𝗮𝗽𝗽𝘀 𝗮𝗿𝗲 𝗯𝗲𝗶𝗻𝗴 𝗯𝘂𝗶𝗹𝘁 𝗼𝗻 𝘁𝗼𝗽. Save with yield, spend with a card, send across borders in seconds. The product surface looks familiar. The infrastructure underneath is completely new. 𝗧𝗵𝗲 𝘁𝗮𝗸𝗲𝗮𝘄𝗮𝘆: Most users will never think about blockchain, the same way they don't think about TCP/IP when they send a message. They'll just use financial products that work better. For the first time, that's possible at a global scale. Full breakdown in my latest Forbes article. Link in the comments 👇 Find this useful? ♻️ Repost it. Building in this space? 💬 Drop your take below.
- FNZSince 15 Jul 2026
Das AV-Depot wird nicht am Produkt scheitern – sondern an der Umsetzung. Wir sehen aktuell in vielen Gesprächen mit Banken, Asset Managern und Versicherern: Die größte Herausforderung liegt nicht im Produktdesign, sondern in der operativen Realität. Integration von Regulierung, Administration und IT, die richtige Build-vs.-Plattform-Entscheidung – und für Versicherer zusätzlich die Einbindung von Wertsicherung und Auszahlungsmodellen. Und vor allem: Wie gelingt das alles rechtzeitig bis zum 1. Januar 2027 – ohne spätere Brüche im Betrieb? Wir haben unsere Perspektive dazu in einem kurzen Video zusammengefasst (etwas länger als üblich, dafür mit klarer Einordnung der wichtigsten Stellhebel): - warum das AV-Depot vor allem ein Umsetzungsprojekt ist - wo die größten Risiken entstehen - und wie sich Time-to-Market, Integrationsaufwand und Betriebsrisiko gezielt steuern lassen Wenn Sie das AV-Depot schnell, skalierbar und ohne unnötigen Eigenaufbau einführen wollen: Mehr Informationen: https://lnkd.in/d7f5NT6R Direkter Austausch: Schreiben Sie uns eine Nachricht oder kommentieren Sie unter dem Beitrag. Wie gehen Sie aktuell mit der Umsetzungsfrage beim AV-Depot um – Build oder Plattform?
- FLOASince 18 Jun 2026
FLOA @ VivaTech 2026 Cette année, une évidence : le futur du travel se joue aussi dans le paiement. Plus flexible, plus fluide grâce au BNPL, il devient un déclencheur… et un outil pour bien gérer son budget. Et l’IA ? 👉 Réserver un voyage sera peut-être aussi simple que de discuter avec un assistant ? #VivaTech2026 #Traveltech #Innovation Merci Frederic Vanhoutte pour l'hospitalité !
- FLOASince 19 Jun 2026
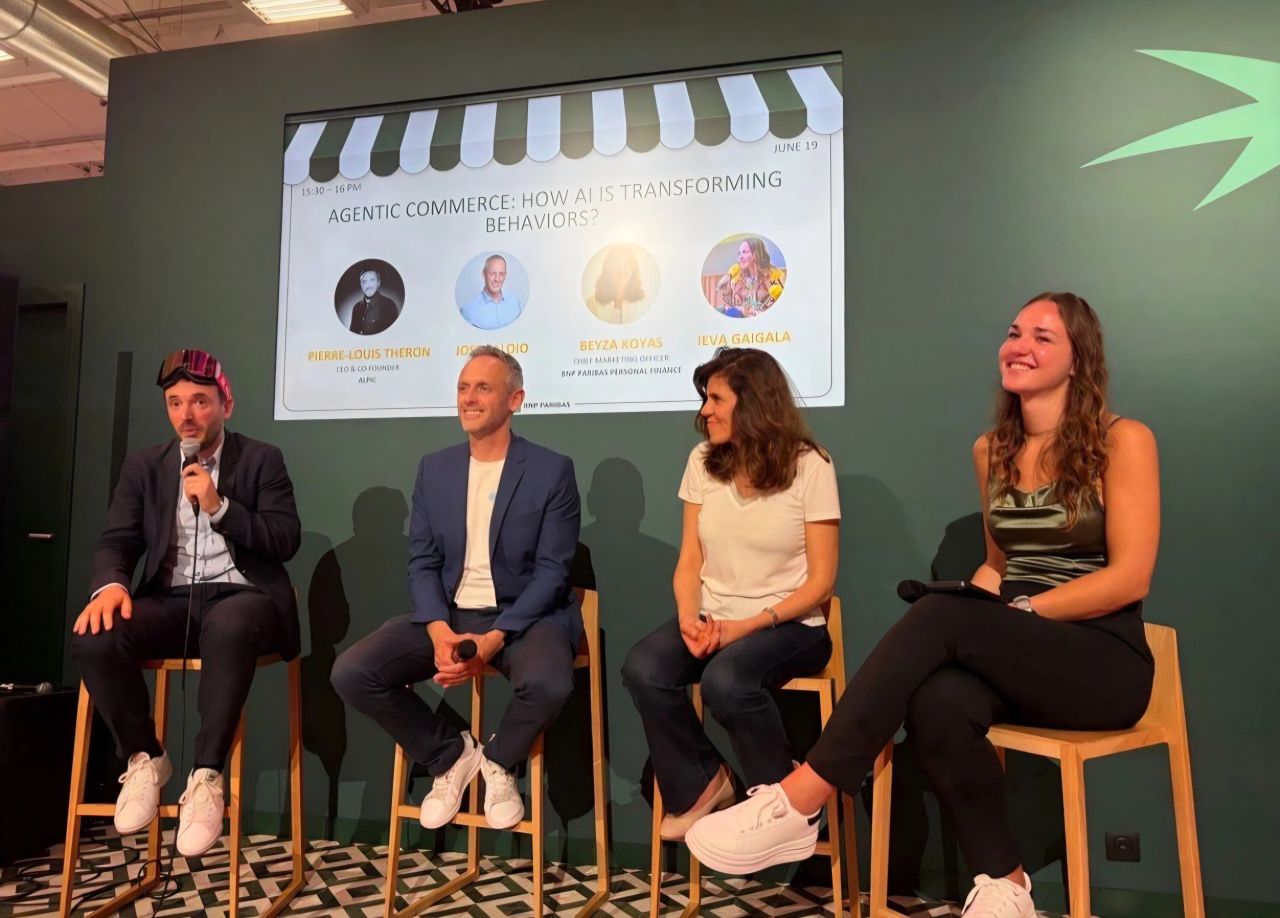
L’enjeu n’est plus de savoir si l’#IA va transformer le commerce. C’est déjà une réalité. À VivaTech, l’IA est partout. Il était donc naturel pour Floa de participer à la table ronde "Agentic Commerce: how AI is transforming behaviors?" pour partager ce que nous observons déjà sur le terrain: 👉 Avant l’achat, les consommateurs utilisent l’IA pour rechercher, comparer et préparer leurs achats. Selon notre étude Kantar, c’est déjà le cas pour 30 % des Français et 40 % des plus jeunes. 👉 Après l’achat, l’IA fait désormais partie de la relation client. Chez FLOA, notre agent IA Eva a déjà traité plus de 2 millions de contacts avec un NPS de 46. Ça y est, l’IA entre dans les habitudes de nos clients lorsqu’elle apporte une expérience simple, utile et personnalisée. 👉 La prochaine étape est l’achat et le paiement lui-même. Quand l’agent ne se contentera plus d’aider à choisir, mais pourra aussi recommander une solution de paiement et initier une transaction. À ce moment-là, le sujet ne sera plus seulement technologique. Il sera avant tout une question de TRUST : identité, consentement, sécurité, fraude et responsabilité. Je suis convaincu que le commerce agentique est une opportunité. Comme le e-commerce ou le smartphone avant lui, il va créer de nouveaux usages et de nouveaux modèles économiques qu’on a encore du mal à imaginer. Chez FLOA, c’est simple, on a décidé de continuer à faire ce qu’on sait savons faire depuis le début : apprendre vite, construire maintenant et avancer avec nos marchands et nos partenaires technologiques. Et ça va être incroyable ! 😉 Merci encore à Ieva Gaigala d’avoir animé cette table ronde avec Beyza Koyas et Pierre-Louis Theron. #VivaTech2026 #AgenticCommerce #AI #Fintech #BNPPShapingInnovation
- Foundation CapitalRecorded 19 Sept 2026
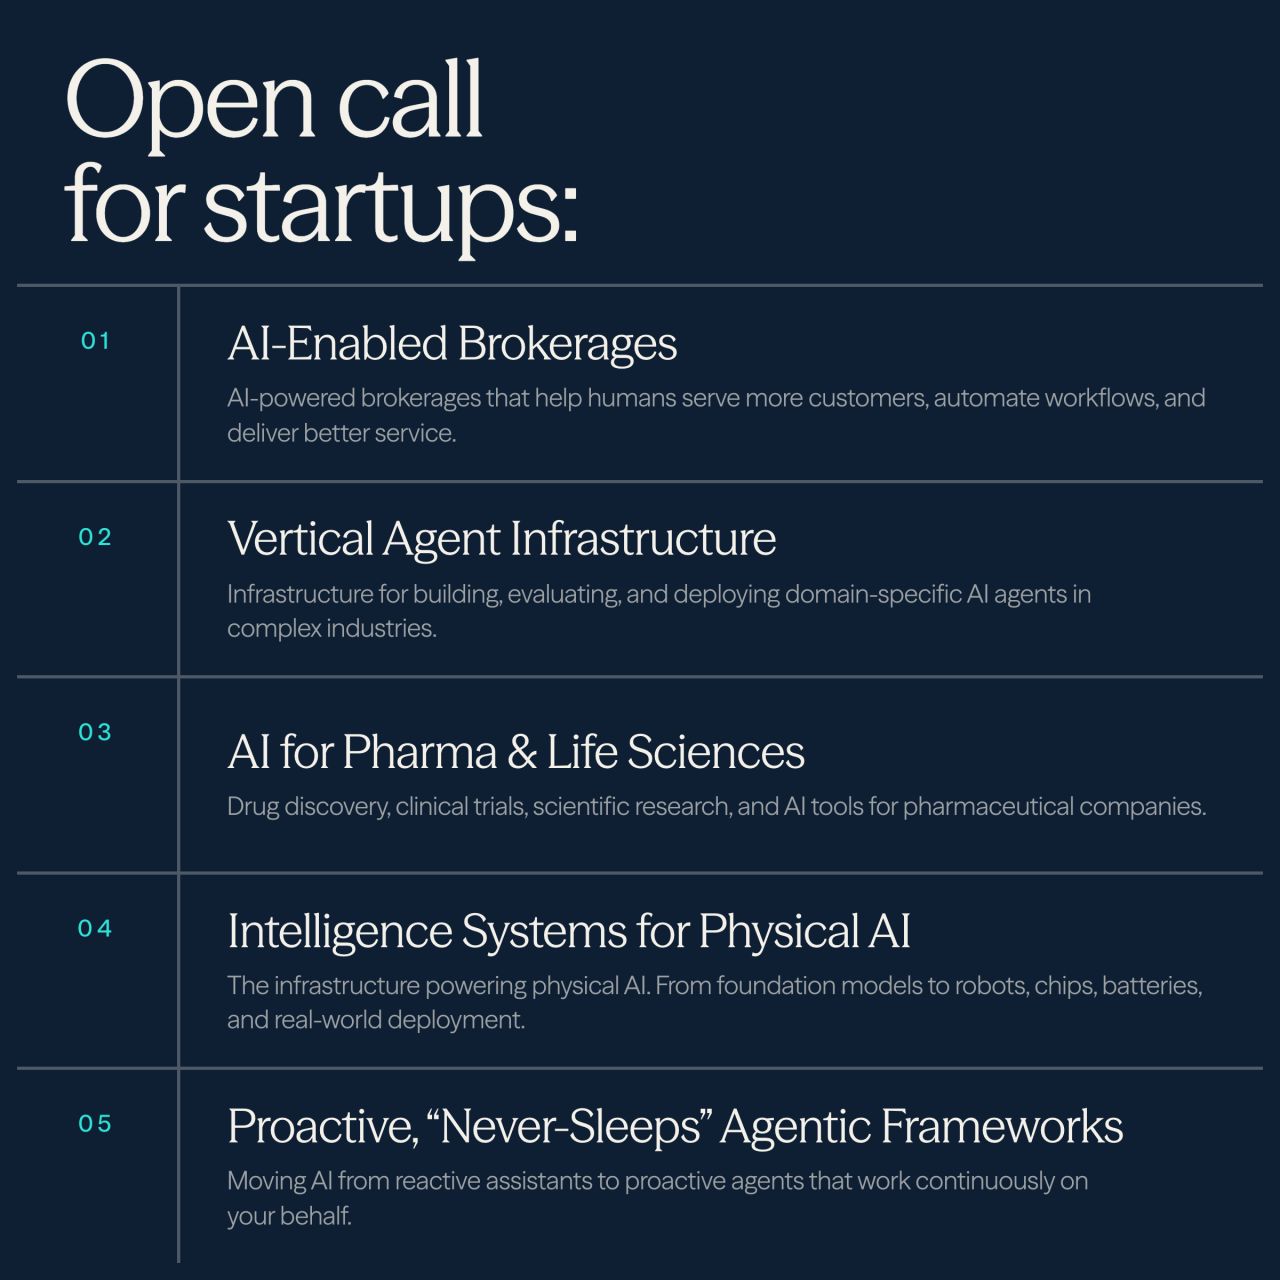
Open call for startups: With less than 10 days to apply for the next FC Build cohort, here are a few areas we're especially excited to see founders building in: • AI-enabled brokerages • Vertical agent infrastructure • AI for pharma & life sciences • Intelligence systems for physical AI • Proactive, "never-sleeps" agentic frameworks Building something else? We'd still love to hear from you. Some of our favorite investments started with founders who saw something the rest of the market didn't. FC Build is Foundation Capital's completely free accelerator for technical founders at day zero. No fees. No equity. $1M+ in startup credits. Applications close August 14th, apply now! https://lnkd.in/gXN9_HQf
- FounderpathSince 8 Jul 2026
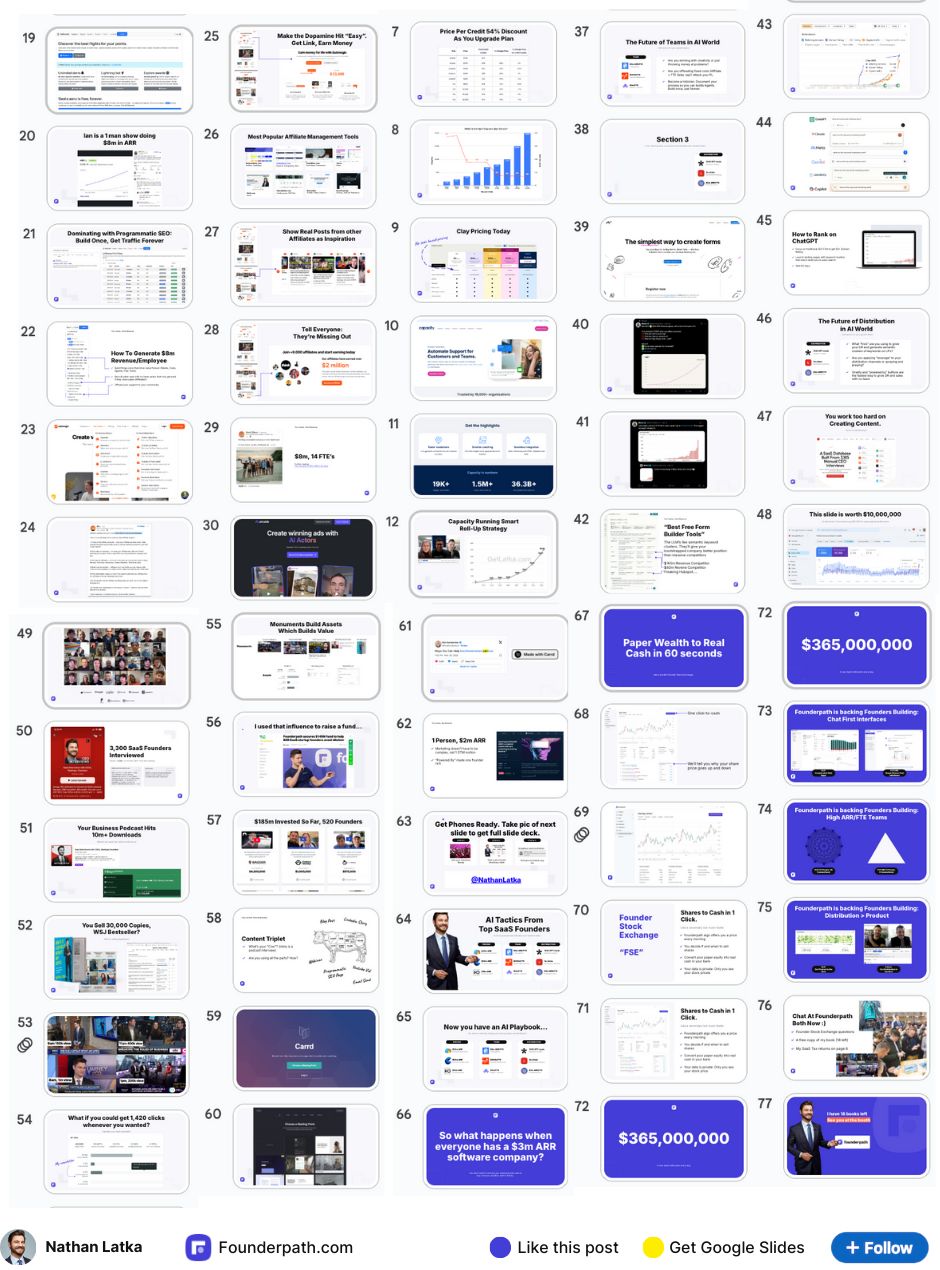
9 AI Growth Tactics: luma.com/fp24?tk=8LuPBI UPDATE Jun 28: 1,346 smart founders asked for the slide deck. I can't keep up with the comments 👉 Get the full deck here: https://bit.ly/4vExXc6 Tiny Teams, Giant Revenue: 9 SaaS Founders using AI to print money. (Each case study added more than $1m in ARR last month) No catch, just one: Sharing it only for the next 24 hours What's covered: > ChatGPT Traffic: How this CEO got 1,200 leads from showing in LLM results > Agents replace humans: CEO hits $12m ARR with just 12 FTE's > 33 growth tactics custom-built for the age of AI and LLM's + BONUS: I added real revenue graphs so you see first-hand how CEO's are using these.... Companies in my deck: Kareem Amin and the pricing tests Clay has run (base fee + credit bundles) David Karandish and Capacity outcome based pricing (now $60m ARR, 8+ acquisitions) Coco Mao and the genius in OpenArt AI's pricing page + discord community Ian Carroll super tactical SEO he used to hit $8m as a 1 person team David and the details of Submagic's affiliate program that led to $1m ARR in 90 days Romain and 4 agents he built to hit $5m+ ARR at Arcads AI with a small team Marie Martens and how Tally drove up its DR, now paying dividends with 1200 ChatGPT signups last week You'll see the kind of founders Founderpath is actively backing with Venture Debt, Team Loans, and revenue based financing. If you want the preview slide deck: 1. Like the post 2. Comment with "slides please" or "sharing is caring" ... aaaand I'll send the slides to you via Linkedin DM (please make sure we're connected) at 6pm EST tomorrow night. !! UPDATE Jun 28: This went viral and I can't keep up. 👉 Get the full deck here: https://bit.ly/4vExXc6
- FounderpathSince 8 Jul 2026
AI Founders, watch revenue grow: luma.com/fp24?tk=8LuPBI This Solo AI Founder exited for $80m... Bootstrapped, $3.5m revenue: Meet Maor. Bootstrapped to $3.5m in 6 months. Exited for $80m: Anti-Trends he dominated: → He raised no VC (bootstrapped) → He built no team (solo founder) → He didn't chase unicorn ($80m works!) PSA: the world is changing. Keep equity. Scale fast. Keep optionality. Create personal wealth. Rinse -> wash -> repeat Congrats to Base44! 👉 To grow your revenue fast, RSVP here for free: luma.com/fp22?tk=HtFAPK
- FinqleSince 21 Aug 2026
Je hebt geen lening nodig. Je hebt 18 dagen nodig. Een onderneming spreekt netjes 30 dagen betaaltermijn af. In de praktijk duurt het 48 dagen voordat het geld er is: - 3 dagen urenstaat versturen - 3 dagen correcties en goedkeuring - 1 dag wachten op de wekelijkse facturatiebatch - 3 dagen inboeken bij de afnemer - 30 dagen betalingstermijn - 8 dagen te laat, want iemand was op vakantie Bij 1 miljoen omzet betekent dat € 49.388 euro extra werkkapitaal dat permanent vaststaat. 60% meer dan afgesproken. De reflex bij zo'n gat is extra krediet aanvragen. Maar de winst zit bij het proces, niet bij de bank. Eerst optimaliseren, dan pas financieren. En moet je daarna toch financieren, dan over een lager bedrag en dus goedkoper. Hoe lang duurt het bij jullie van geleverd werk tot geld op de rekening? #werkkapitaal #cashflow #MKB #debiteurenbeheer #finqle #cashflowgeregeld
Other LinkedIn formats
Watch the companies you care about.
Filter every ad by industry, country, format and network, and get alerts when a company you watch starts running new ads.