On air · 1 of 3 networks
finperks
- finperks.com
- Fintech & Financial Services
- DE
- 20 employees
finperks’s ads on LinkedIn, Meta and Google, recorded by adsrunning. Browse the latest here for free. Sign up free to see all 39. Watch finperks with Starter to get each new one in your feed.
Watchlist with Starter · $49/mo
| Network | Status | Live ads | Nov 2025LinkedIn activity · 52 weeksOct 2026 | Checked | Next step |
|---|---|---|---|---|---|
| None recorded | 0 | Checked 28 Oct 2026 | See all 39 ads → | ||
| Meta | None recorded | 0 | No active ads recorded on the Meta Ad Library | Checked 20 Oct 2026 | Collect them with the API → |
| Running | 22 | Ads on the Google Ads Transparency Center | Checked 29 Oct 2026 | Collect them with the API → |
finperks has no live LinkedIn ads. Its Facebook page had no active ads on 20 Oct 2026, and we recorded 22 Google ads on 29 Oct 2026.
Latest ads
- LINKEDIN · VIDEOSince 29 Jul 2026
BIG news: Finanzguru went live with 𝗦𝗽𝗮𝗿𝗯𝗼𝗼𝘀𝘁𝗲𝗿, powered by finperks. By us! We are the rewards engine behind it, reaching their 3+ million users 🤯🚀 I have wanted this one on the board for a while. What a ride it's been really, I have no words Finanzguru is one of Germany's biggest finance super apps. When Benjamin Michel and Alexander Michel told me they wanted to turn everyday spending into loyalty points, we knew where to hit the target on the nail. A user opens Finanzguru, picks a brand, buys a voucher, and the points build up on top till cash out. Easy, No codes, No searching. And the catalogue isn't filler, its the places people already spend every week on groceries, fashion, travel, entertainment. Points clear in real time the second someone crosses €5, and Finanzguru Plus doubles them on every voucher. Groceries, travel, fashion are things people buy every week without thinking twice. Tie points to that, pay out building up on the spot, and the app becomes part of how you already spend. The Plus doubling gives regular buyers a reason to upgrade, and a reason to spend more once they have. That's what we mean by building a rewards engine, and not a coupon 💜 For the 2026 World Cup, Finanzguru ran a prediction game with €250,000 in prizes, and dropped the rewards engine straight into it. Sparbooster points sat in the prize pool next to cash and signed Toni Kroos merch, with boosted double-digit cashback on selected brands for the tournament. That is what you get when rewards are infrastructure and not a fixed feature. A big moment lands, you build the campaign on top, and the engine bends to fit it. No brand-by-brand negotiation and approvals. No supplier contracts to juggle. They plugged into finperks and had a full catalogue they can push to their users from day 1 👌 A huge thank you to the founders, I've been a fan of what you've built for years, and working closely with you on this launch only confirmed why: I rarely see a team this customer-first and recognize exactly what their customers are missing out. Of course, a massive thank you to the growing finperks team. Launches like this happen because you go the extra mile every single day, quietly and consistently. Proud to build this with you. Sebastian Seifert Andreas Veller Tobias Schoknecht Philipp Zelmer Alexey Ryabichev Trung Han Nguyen Corneel De Baere Isabella Becker Carla Escobar Valdés Jan-Robert Stange Kristin Reiß Chinonso Ashimole, and our hard-working interns 💪💪
- LINKEDIN · IMAGESince 22 Jul 2026
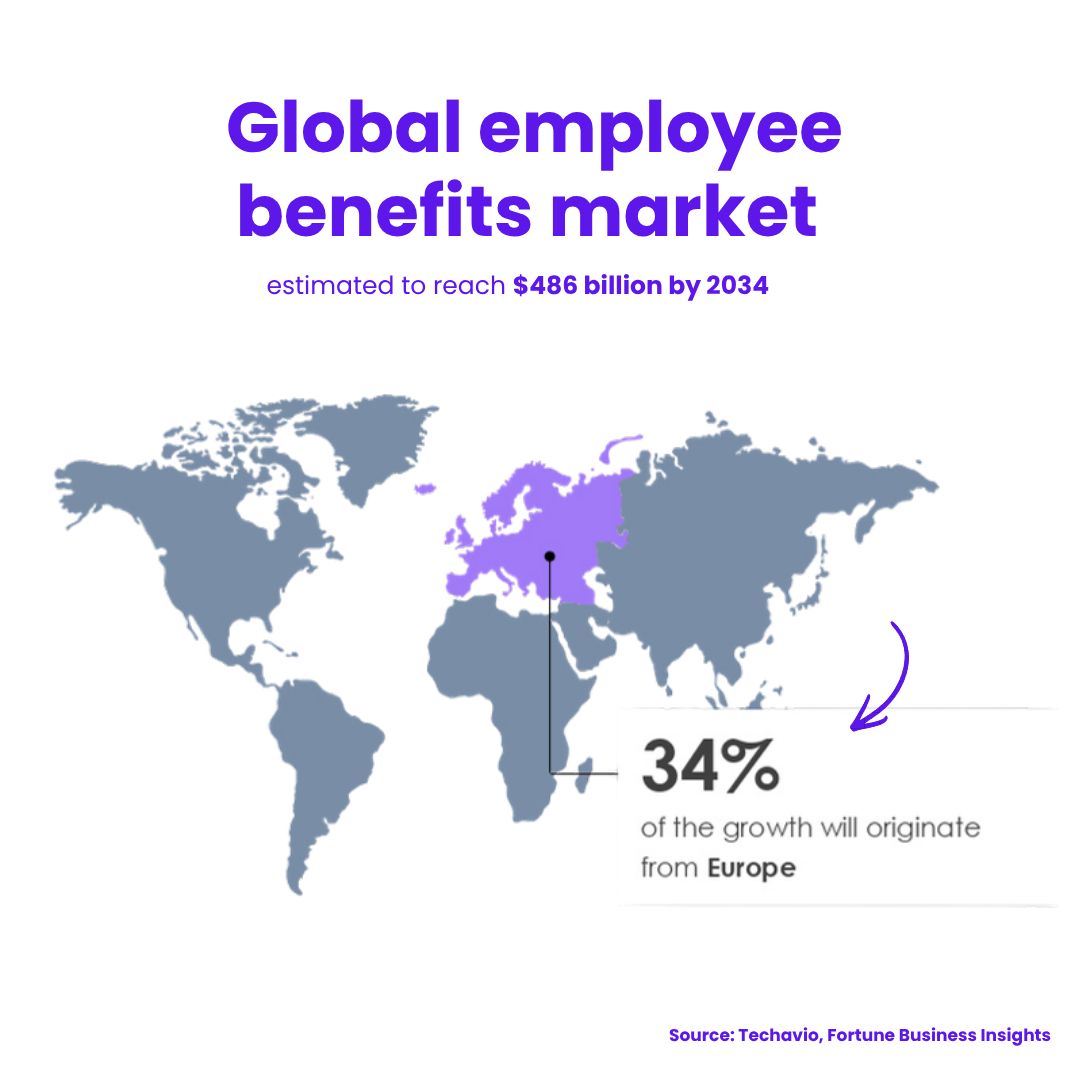
Ask an employee what they actually use, and it is rarely the ping pong table. It is the benefit that lands in their pocket every month 💪 𝗘𝗺𝗽𝗹𝗼𝘆𝗲𝗲 𝗯𝗲𝗻𝗲𝗳𝗶𝘁𝘀 𝗰𝗮𝗻 𝗯𝗲 𝗼𝗻𝗲 𝗼𝗳 𝘁𝗵𝗲 𝗹𝗮𝗿𝗴𝗲𝘀𝘁 𝗽𝗿𝗲𝗽𝗮𝗶𝗱 𝘃𝗲𝗿𝘁𝗶𝗰𝗮𝗹𝘀 𝗶𝗻 𝗘𝘂𝗿𝗼𝗽𝗲. The market is worth more than $77 billion a year in Europe alone, part of a $232 billion global market And it is nowhere near saturated. → 102.6M employees across the five largest EU schemes are eligible for tax-free benefits. → In Germany alone, 42.3M people qualify for the €50 per month tax-free Sachbezug. → Only about half of employers actually use it every month. So this is not a demand problem. Employees want money that stretches further, especially against rising prices. That €600 a year of tax-free purchasing power matters more now than it did five years ago. The friction is....every market runs its own scheme. A Sachbezug in Germany, a titre-restaurant in France, an ecochèque in Belgium. Same idea, a different rulebook in each country, and real admin to run it properly. That is where the 𝗼𝗽𝗽𝗼𝗿𝘁𝘂𝗻𝗶𝘁𝘆 is hiding. What we are doing at finperks is allowing HR SaaS platforms to offer tax-free rewards (often prepaid/gift cards) natively in their platform. Employees claim the benefit in the tool they already open every month, with no separate app and no extra login. The compliance runs in the background, scheme by scheme, so the platform never carries the legal or admin load. And rather than paying a standalone provider on top of the gift card margin, the platform earns that margin itself 🙂 Where do you think the biggest unlock is, on the employer side, the employee side, or in the infrastructure?
- LINKEDIN · IMAGESince 20 Jul 2026
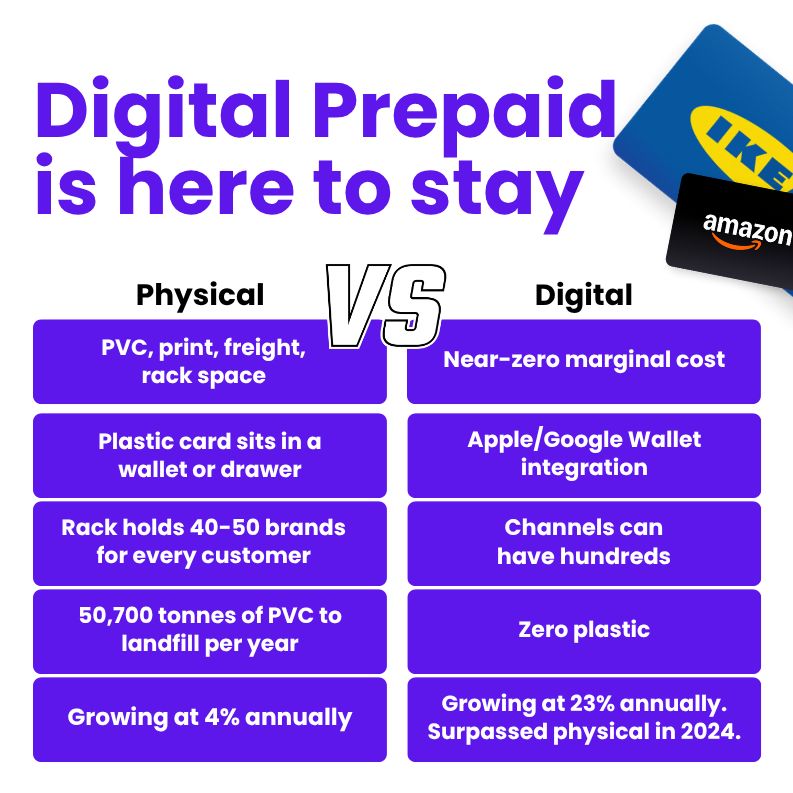
Physical gift cards cost to print before freight, rack fees, and restocking hit the total 🙋♂️ Digital marginal cost per additional issuance: near zero. 0️⃣ That is not the interesting part. Here is why digital gift card distribution wins on structural dimensions: → Server-side activation kills fraud at the root. Fraudsters targeting physical cards exploit one vulnerability: exposed PIN codes sitting on retail racks. Server-side activation means the code does not exist until the moment of purchase. → Apple Wallet integration turns a gift card into a payment rail. A stored-value instrument that lives on the home screen and auto-refreshes its balance is not a gift card anymore. It is a tap-to-pay instrument the brand controls directly. → A supermarket rack holds 40 to 50 brands for every customer. A fintech shelf powered by transaction data surfaces hundreds, and shows the 3 relevant to your actual spending behaviour. → 50,700 tonnes of PVC from physical gift cards go into landfill every year. Every CFO with a net-zero target still has a gift card programme built on plastic. → Digital gift cards surpassed physical in 2024. They now represent 57% of all gift card sales and are growing at 23% annually. Brands still optimising for the rack are running the wrong race. What are your thoughts? If you're interested in adding digital perks to your app, let's talk: https://lnkd.in/eqz3N_Gf Sources: Juniper Research, Earth 911, Mordor Intelligence, and our personal experience building finperks the last year 💪
- LINKEDIN · VIDEOSince 20 Jul 2026
Building my second company finperks right now. The first transaction just hit different. This was a while ago, but I still live on that high 🙂 The first time money moves through infrastructure you built from scratch, it lands differently. Here's what we're solving: Fintechs kept trying to add gift card rewards to their apps and hit the same wall every time: → Minimum 3–5 supplier contracts before you can go live → Brand approvals that take weeks per partner → A different VAT framework for every market you enter → No shared infrastructure, every integration rebuilt from zero The problem was never the gift card itself. The problem was that the distribution layer between Brands and Digital Channels was never built for scale 💪 One integration. Brands go live across multiple digital channels without rebuilding the pipe each time. We just ask for their approval when we have a new client/partner and they need to tell us yes or no. Tap, tap and gift card redeemed inside a payment app. Done. The gift card market is a $300+ billion category. Most of the infrastructure still runs like it's 2005. That's the gap we're filling 💪
- LINKEDIN · IMAGESince 20 Jul 2026
I talked gift cards with the fashion giant, Zalando 🛒 Dr. Moritz Zoellner is the mastermind behind it. Active across 25 European countries with 62 million active customers and €12.3 billion in revenue in 2025, no other fashion platform in Europe comes close. Zalando's loyalty programme alone reached 16.8 million members. We talked gift cards for an hour. When I, as a distributor, ask partners what matters most, the answer is usually some version of the same mix: reach and not having to manage ten different integrations. 🟣 Not just volume, but the right channels. Banks, HR platforms, insurance companies, payment providers etc. Consumers who are already in a spending mindset. Brands want high-trusted channels where people manage their money. Logging in to check their balance, review their payslip, or manage their account, where a relevant brand offer lands as useful, not intrusive. 🟣 Operational simplicity. The traditional model requires brands to negotiate separately with every gift card distributor, in every market, for every new channel. finperks inverts that. We have the channels, in the pipeline across 30 markets in Europe, with partners already reaching millions of consumers in DACH, Italy, etc. We just need your approval to put you as a brand there. And the Consumer experience follows. On our partner apps, users see 6% platform-subsidized payment at Zalando before they buy a prepaid/gift card. It's an extra something the client offers, while the Brand loses nothing. We, at finperks, want to become the first distributor that support partners in expanding to 30+ markets, putting them in global high-trust, high-growth channels. Always great to meet up with you and chat about the real stuff 🚀 Are you a brand wanting to expand your reach with gift cards in high-growth, unconventional channels? We have something for you 🚀 Let's talk: https://lnkd.in/eqz3N_Gf
- LINKEDIN · VIDEOSince 9 Jul 2026
We sat down with Zalando to understand how they think about gift cards. And of course, why they're working with finperks, a start-up supplier, to amplify their reach 💪 Dr. Moritz Zoellner put it clearly: "From Zalando's perspective the gift card has several purposes. Rewarding our loyal customer base, reactivating customers, which is one of the key things for the next years, and new customer acquisition." So the question becomes: how do you reach all three audiences without building distribution from scratch for each one? Moritz's answer points straight at the gap finperks fills: "What finperks offers is access to new, high-value distribution channels that are typically hard to tap into directly, like banking apps and corporate benefit platforms." What stood out in the conversation: ✔️ Gift cards reach customers who do not convert through standard checkout. The shopper sitting inside a banking or benefits app, not browsing the store, who buys a Zalando card and spends it later. ✔️ Loyalty, reactivation, and acquisition served from a single integration. A loyal customer on our partner app buys one to treat themselves, a lapsed customer comes back for a cashback offer, and a new buyer discovers Zalando inside an app they already use. ✔️ A loaded card is committed money. That turns a single top-up into several trips to the store over the following weeks. Self-use is also growing and virtual prepaid payments in Apple/Google Wallets. On top of that, European channels are key, with Robert Gentz saying, "Our ambition is margin expansion in Europe...." quoting geographic expansion into new countries. Zalando can't distribute gift cards across 28 European markets through one partner usually. Different settlement and compliance standards per market. We collapse this chain into one with an API. Grateful for the conversation, and for the chance to learn from a team operating at this level. Thank you for your trust and sitting with us ! Are you a brand wanting to expand your reach with gift cards in high-growth, unconventional channels? We have something for you 🚀 Full case study in the comments 👇
6 of 39 adsSign up to see every finperks ad, filter by format and date, and get alerts on new ones.
See all 39 adsWatch the companies you care about.
Filter every ad by industry, country, format and network, and get alerts when a company you watch starts running new ads.