LinkedIn thought leader ad examples
404 thought leader ads are live on LinkedIn right now, from 337 companies. Browse real ones, filtered by industry.
- Greenday FinanceRecorded 21 Sept 2026
Are you an EPC with a high-potential project stuck waiting for the right financing partner? I’m here to accelerate your progress. We pay a premium for projects ready to close before year-end — with approved permits, construction underway, or already completed. Spec highlights: • Target: ~$2M • System size: 600–750 kW • Substantial completion, COD, or in service in 2025 GDF provides responsive capital, custom terms, and dedicated collaboration, ensuring you get what you need to complete, commission, and celebrate this year. If you’re ready to partner with a team that believes in your success, reach out to GDF today.
- Greenday FinanceRecorded 21 Sept 2026
A lot can happen in 20 days, but nothing quite like this. Last week, our team pulled off something worth celebrating: closing a $10.9 million, 3.33 MW solar deal in under 20 days. Our Baltimore-area project in Pennsylvania officially closed on December 8th, after kicking off diligence on November 11th (excluding Thanksgiving week). But the real story isn’t the timeline, it’s the teamwork. This deal happened because every person involved showed up with discipline, urgency, and alignment. We ran daily calls. daily responsibility reports. firm deadlines. And across every workstream, our internal team executed with precision while our partner matched that energy step for step. That level of coordination is rare, and it’s why this one feels like a true team victory. Huge congratulations to Fortez Group LLC for being an exceptional seller and partner. When preparation, communication, and accountability all hit at the same time… 20 days is more than enough. Now we’re ready for the next challenge. We’re currently reviewing: • 1–2 projects • ~$7M per project • 2.5–3.5 MW system sizes • Already under construction • COD or Placed in Service in 2025 If that sounds like something you’re working on, let’s talk: https://lnkd.in/g2jrHhfB
- SphereSince 11 Jun 2026
There’s a common question that comes up in almost every demo call we have at Sphere: “How do you make sure your AI is getting our tax right?” The simple answer is: our AI research model isn't the same as your regular ChatGPT/Claude search. Tools like ChatGPT and Claude weren't built to reason over constantly changing tax law - they’re typically trained on a snapshot of the internet. Tax law is a living and breathing beast. It’s jurisdiction-specific and full of edge cases that don't make it into training data. So when you ask Gemini a tax question, you often get a confident answer that was maybe true, somewhere, at one point in time. Here’s how TRAM (our AI-native tax research system) is different: → It continuously ingests primary source legislation, guidance, bulletins, and rulings directly from tax authorities - not the internet generally (so it’s not learning from what some random guy said on Reddit 4 years ago) → It uses fine-tuned reasoning models trained specifically for multi-step legal and tax reasoning → Every determination it makes comes with citations back to the actual source material → Before anything goes live into our tax engine, a Sphere tax expert reviews and approves it We’re not replacing humans, we're just making tax research faster, more reliable and scalable. TRAM does the heavy lifting of finding, reading, and reasoning over the law, then our experts spend minutes, not days/weeks reviewing each determination. I use Claude every day - for work research, planning my SF weekend getaways, finding recipes and more. General LLMs are great at many things but high-stakes tax research isn't one of them. [TRAM info in comments]
- RyftSince 29 Jul 2026
Recently made the switch to ŌURA and I'm loving it ✨💍 For a while I wore a Whoop and it was great. But I kind of felt like I had to choose between wearing something functional or something that felt like me. I'm a gold jewellery girl, so Oura doesn't look like a gadget on my wrist, it feels like part of my everyday style. At the same time, I can still track the things I care about to stay on-top of my goals - like my sleep, steps and workouts. I think the best changes are the ones that fit into your lifestyle without you even thinking about them, which is how Oura feels for me so far 💕
- RyftSince 13 Aug 2026
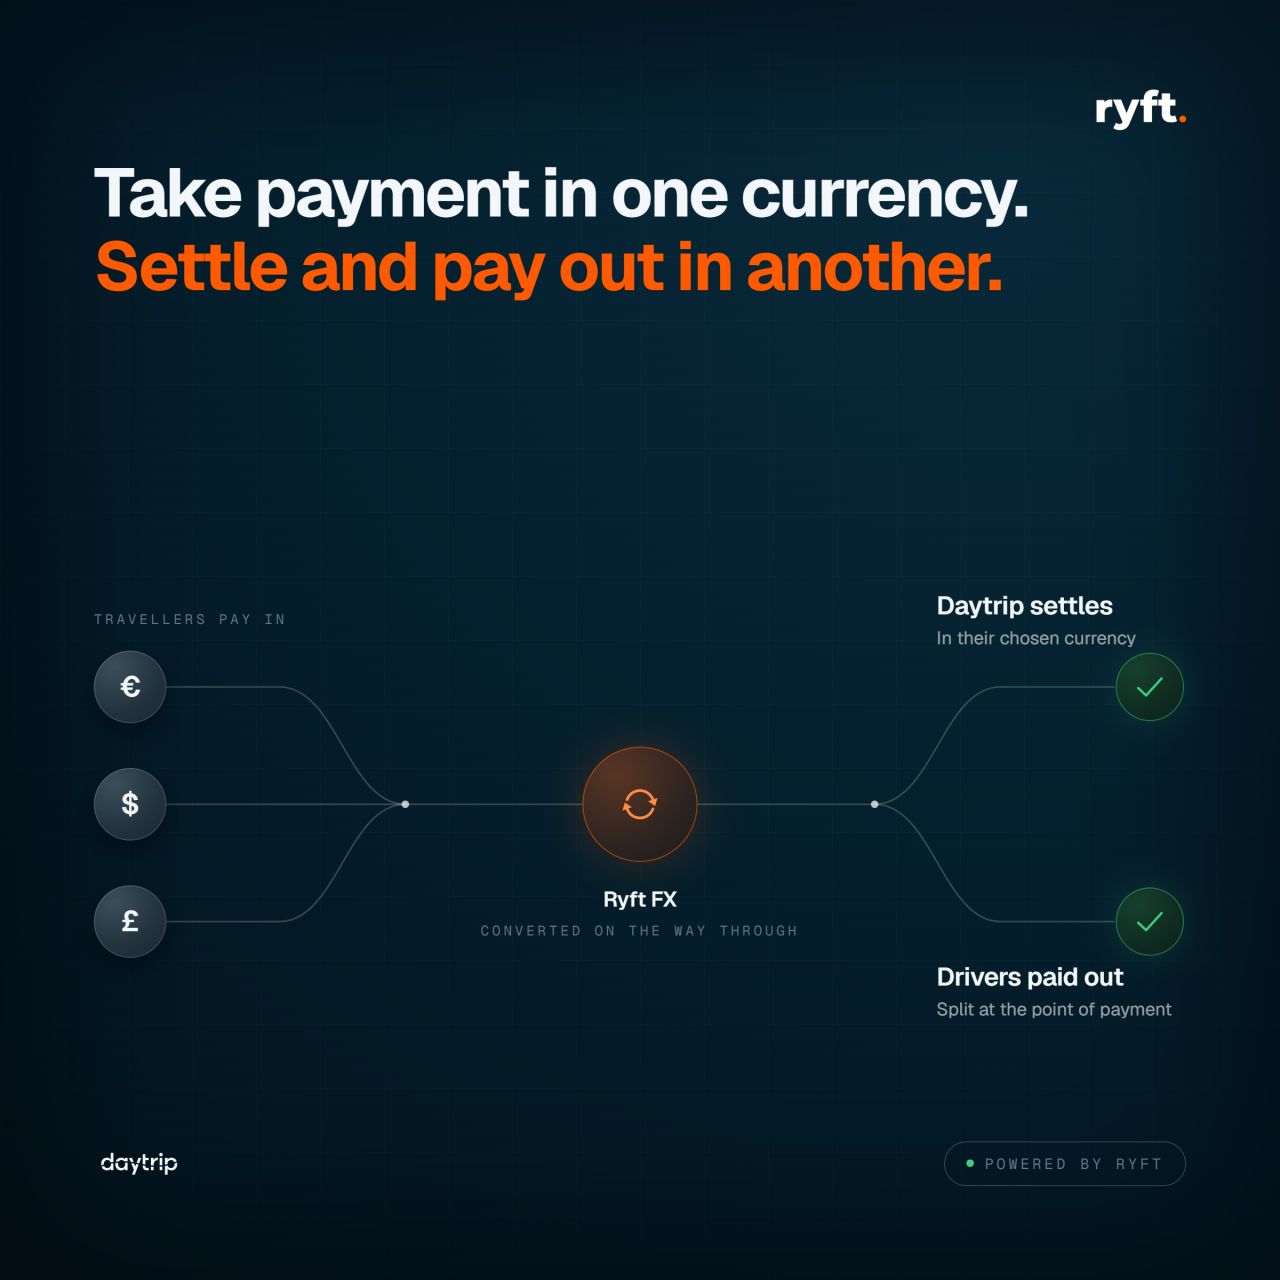
Some things just work better face to face, roadmap planning included. This one happened to come with a trip to Prague ✈️ Earlier this year I flew out to Daytrip's head office to dig into their action plan, no half hour call was going to cut it for this one. Fast forward to now, and they're one of the first clients to go live with Ryft FX. In simple terms, this means accepting and settling payments in different currencies, so a business can sell in euros, dollars or pounds without needing separate providers or manually converting everything back. Genuinely proud to see it come together, and it's a good reminder of what happens when you grow collaboratively as partners 🧡
- SphereSince 24 Aug 2026
While interviewing at Sphere for TRAM Lead role, I asked the question: "What's the gap between how the product is marketed and what it actually does?" The answer I got was that there wasn't any. Sure. Every product team says that. So I spent my entire first week doing what any reasonable new joiner would do: quietly interrogating every corner of the product to find the gap. But I found... nothing. The product is, annoyingly, exactly what we say it is – internally and externally. Which, if you've worked in tech marketing for more than five minutes, you know it doesn't happen very often. TRAM is the product I lead - and no, it's not an actual tram. No overhead cables, no metal tracks, no city streets involved. Just tax tech. Sorry to disappoint the public transit enthusiasts. What does TRAM do exactly? It monitors tax changes and does the research for you, pulling from tens of thousands of legal sources across the globe - all verified, not vibes-based. We still keep a human in the loop before anything touches the tax engine, because "fully autonomous AI tax decisions" is a sentence that should scare everyone. This is also why you won't catch us sprinkling "AI" onto every button and page title like glitter. We built the real thing from day one. It doesn't need a marketing touch-up. TRAM can actually conduct research across hundreds of product sub-categories, capturing virtually every tax-relevant variation globally. Our recent record is 348 distinct sub-categories for a single product. Manually, that's at least a multi-month project + a constant maintenance. With TRAM it took us one week – from the concept to go-live. We're not trying to brag. ...okay, we're a little bit bragging. The future's here. Stay tuned for what's next. Or ping me to hear more!
- LucySince 25 Aug 2026
"𝐀𝐜𝐜𝐨𝐮𝐧𝐭𝐚𝐧𝐭𝐬, 𝐞𝐯𝐞𝐧 𝐞𝐞𝐧 𝐞𝐞𝐫𝐥𝐢𝐣𝐤𝐞 𝐯𝐫𝐚𝐚𝐠. 👇" Heb jij het gevoel dat jouw klanten vandaag écht 100% up-and-running zijn voor Peppol? Of overschatten we dat soms? Wij vroegen het niet aan softwareleveranciers of accountants, maar aan de ondernemers zelf. De resultaten bevestigen een aantal zaken... maar zetten ook enkele aannames op losse schroeven. Ik heb de opvallendste inzichten samengevat in onze nieuwste blog. 💬 Ik ben vooral benieuwd naar jouw ervaring: 𝐖𝐞𝐥𝐤𝐞 𝐮𝐢𝐭𝐝𝐚𝐠𝐢𝐧𝐠 𝐳𝐢𝐞 𝐣𝐢𝐣 𝐯𝐚𝐧𝐝𝐚𝐚𝐠 𝐡𝐞𝐭 𝐯𝐚𝐚𝐤𝐬𝐭 𝐛𝐢𝐣 𝐤𝐥𝐚𝐧𝐭𝐞𝐧 𝐚𝐥𝐬 𝐡𝐞𝐭 𝐨𝐯𝐞𝐫 𝐏𝐞𝐩𝐩𝐨𝐥 𝐨𝐟 𝐞-𝐟𝐚𝐜𝐭𝐮𝐫𝐚𝐭𝐢𝐞 𝐠𝐚𝐚𝐭? Ik lees graag mee in de comments. #erevolutie #accountancy #Peppol #efacturatie #digitalisering #ondernemen
- LucySince 25 Aug 2026
“𝐖𝐞 𝐡𝐞𝐛𝐛𝐞𝐧 𝐦𝐨𝐦𝐞𝐧𝐭𝐞𝐞𝐥 𝐠𝐞𝐞𝐧 𝐭𝐢𝐣𝐝/𝐫𝐮𝐢𝐦𝐭𝐞 𝐨𝐦 𝐧𝐚𝐚𝐫 𝐧𝐢𝐞𝐮𝐰𝐞 𝐨𝐩𝐥𝐨𝐬𝐬𝐢𝐧𝐠𝐞𝐧 𝐭𝐞 𝐤𝐢𝐣𝐤𝐞𝐧.” Een zin die ik de voorbije maanden meer dan eens heb gehoord, en volledig begrijp. De Peppol-deadline ligt al even achter ons. De meeste kantoren hebben ondertussen een oplossing gekozen, hun klanten aangesloten en zijn eindelijk een beetje gewend aan de nieuwe manier van werken. En dan komt er iemand met de vraag: “Heb je Lucy al eens bekeken?” 😅 Softwaremoeheid is real. En daarom is zomaar opnieuw switchen, of elke nieuwe Peppol-oplossing onderzoeken waar je klanten mee afkomen, ook helemaal niet de bedoeling. Je huidige setup werkt. Maar 𝐢𝐬 𝐝𝐢𝐭 𝐰𝐞𝐥 𝐝𝐞 𝐛𝐞𝐬𝐭𝐞 𝐨𝐩𝐥𝐨𝐬𝐬𝐢𝐧𝐠 𝐯𝐨𝐨𝐫 𝐞𝐥𝐤𝐞 𝐤𝐥𝐚𝐧𝐭 én voor jezelf? Loop je nog steeds tegen dezelfde wrijvingspunten aan? En wat als je vandaag een nieuwe klant moet aansluiten? Daarover schreef ik een nieuwe blog: wanneer is switchen écht de moeite waard, en wanneer laat je beter alles zoals het is? 💬 𝐌𝐢𝐣𝐧 𝐯𝐫𝐚𝐚𝐠 𝐚𝐚𝐧 𝐣𝐨𝐮: 𝐡𝐞𝐫𝐤𝐞𝐧 𝐣𝐞 𝐝𝐢𝐞 𝐬𝐨𝐟𝐭𝐰𝐚𝐫𝐞𝐦𝐨𝐞𝐡𝐞𝐢𝐝 𝐛𝐢𝐣 𝐣𝐞𝐳𝐞𝐥𝐟 𝐨𝐟 𝐣𝐞 𝐤𝐥𝐚𝐧𝐭𝐞𝐧? Lees de blog hier 👇 👉 https://lnkd.in/exeYqBqA #Peppol #accountancy #efacturatie #software #digitalisering #Lucy
- EaglSince 14 Sept 2026
Pick your clothes up off the floor before you set the robot vacuum loose. Same goes for your finances. Fix the data before you automate it. Eagl product series - video N°3: Data Quality.
- EaglSince 15 Sept 2026
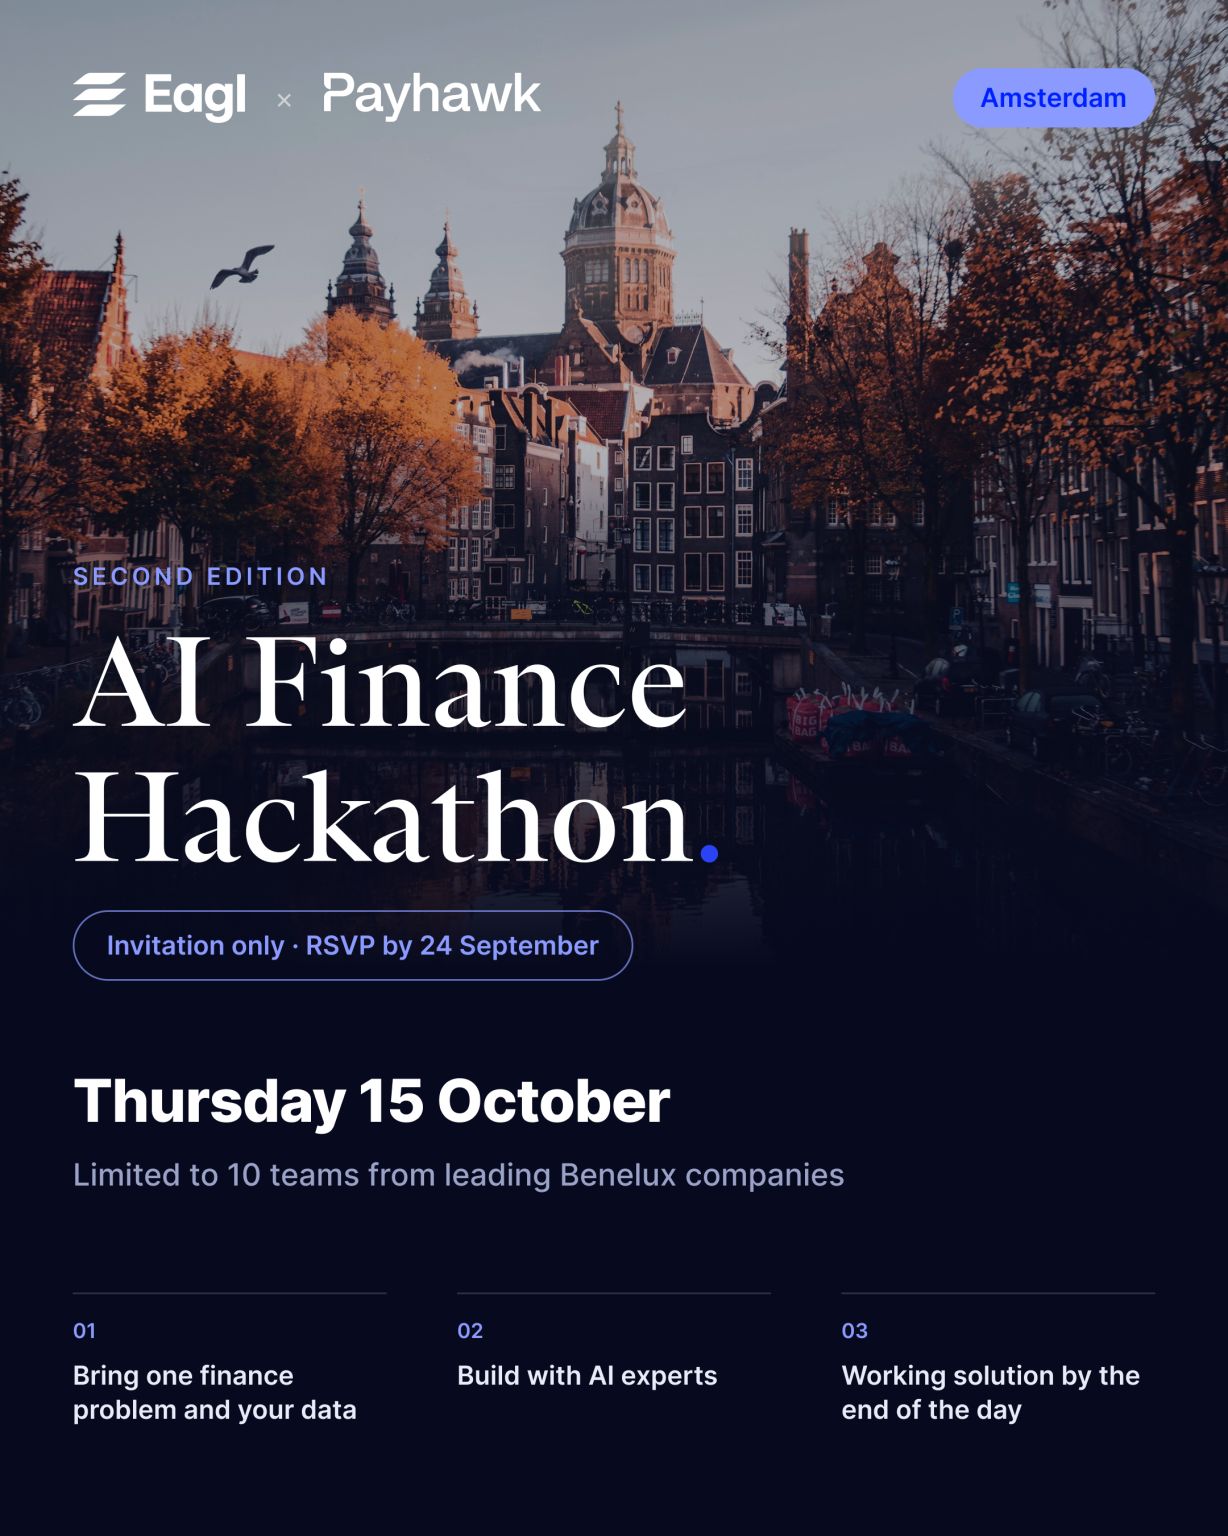
After Ghent in May, we’re bringing the AI Finance Hackathon to Amsterdam. 15 October, together with Payhawk. The format hasn’t changed: you bring one real problem from your finance operation and your own data. You build all day with AI experts at your table. At 5 PM, you demo whatever works, in front of everyone. RSVP closes on 24 September. 10 teams only. Link in the comments. Looking forward to seeing some of you there! 🇳🇱
- SapienRecorded 20 Sept 2026
Every day, millions of people see the world through glass made by Carlex Glass America, LLC With more than 10 million automotive glass units sold annually, Carlex supplies the automakers and replacement networks that keep the world moving. At its Nashville plant, raw materials become finished windshields in one integrated operation, bringing together manufacturing expertise, advanced technology, and extraordinary scale. Now, Carlex brings that same ambition to how it runs the business, in partnership with Sapien. Together, we’ve enabled Carlex to correct a $12M EBITDA attribution, uncover a ~$1.5M annualized profit opportunity in 20 minutes, and turn a customer-service insight into hundreds of thousands of $ in new orders in less than 24 hours—just to name a few wins. What began with one finance workflow has grown into a partnership spanning finance, analytics, sales, customer service, inventory, pricing, operations, and more. As Sapien learns more of Carlex's business, new workflows are running within minutes and unprecedented analytical depth is now directly in the hands of the people making decisions across the company. Carlex’s leadership has helped drive that progress, pairing deep knowledge of its business with the ambition to keep improving it. As CEO Ramzi Hermiz put it: “From my seat as the CEO, Sapien is part of my team, part of my organization.” Thank you to Ramzi Hermiz, Alexander Rotolo, Ryan Loper, Alex Cohn, Jason Waltz, Carlo Harneit, Joshua Morcos, and the broader Carlex team for your trust and partnership, we're excited to share the story from the perspective of the amazing people leading it! Carlex helps millions of people see the road ahead. We’re proud to bring that same clarity to the decisions driving its business forward.
- ClairRecorded 20 Sept 2026
US consumer debt has increased 32% since 2019, rising 6% faster than inflation! Today, there's over $18 trillion dollars in debt held by US consumers. While credit is a necessary tool for people to buy cars, houses and pay for education, we're seeing a fundamental shift from long-term debt (like student loans) to everyday, revolving debt. For a typical hourly worker, short-term debt (credit cards, BNPL) is up 270% since 2019. Why? Because for most Americans, income arrives after expenses. They are forced to use debt as a liquidity bridge for everyday items. This timing problem is solvable with a non-interest and defaults-to-free credit solution connected to the employer. On-demand pay solves this gap by giving workers access to their earned wages as soon as they finish the hours they work. In my new video, I break down this trend and how we're building a responsible alternative at Clair that helps workers use their own money earned instead of piling on new debt.
- FynancialRecorded 20 Sept 2026
"The possibilities are endless." I break down EXACTLY what that means below, and why I'm excited to share the stage with Anna T Walters, CRPC®, and Jason Greenfield at Sanctuary Wealth OASIS 2025. If I were an advisor who wanted to ruin my book of business, here is what I would do. Ignore feedback, avoid client communication at all costs, and make my client's life more complicated. The best advisors flip this. A few stories how: Anna and the Auric Capital Partners Team did something that is SO OBVIOUS, but in my opinion, widely ignored across this industry. They surveyed their clients. They literally asked them what they could do to continue to deliver the best possible service and experience. It was clear their client thought the 'front door' could improve. Their current custodian client portal was falling short. Fast forward to now - they listened, put the work in, and invited these SAME clients to their new portal. Through their app, they asked for feedback and now have built multiple experiences for various clients and prospects. The Lesson - all business problems can be solved by talking to your clients/customers. Jason Greenfield and the Crescent Harbor Private Wealth Team wanted to put their brand on their clients' phones, reduce logins, increase client engagement, and much more. Fast forward to now - they launched their app to all clients, and during the process, proactively reached out via app to gather client feedback and ways they could improve the experience. A short conversation with a retiree about her app experience led to more AUM being managed. The Lesson - Want to grow your business? Have more conversations. THE TAKEAWAY RIAs across the country offer personalized investment management and financial planning, but current technology limits these firms from offering that level of personalization to their client' experience. Fynancial is fortunate to power this experience, but it takes great teams/advisors to make it all happen. See you both in AZ soon 😎 https://lnkd.in/ehfZ5Hfi 👈 Book A Demo Here
- FynancialRecorded 20 Sept 2026
Speed to Action - September Release Is 🤌 It's amazing how fast tasks get done when you can simply get your client's attention. A quick sneak peek at a few features I know our clients are excited about: 1) Mail Merger - Personalization just got easier 2) Secure File - "just go to the app for everything" Mail Merger - Post, Action Items, Reminders, Messages - it's never been easier to get your client's attention and personalize the experience. "Hi (first name) - looking forward to catching up as summer winds down. Feel free to use the link below to schedule our quarterly meeting." Send that to a specific segment of your client base using tags, leverage push notifications, and watch your calendar book immediately. Secure File Your clients are on their phones, and their most important documents should be there too. "A new document has been added to (folder name)." I can't express the power of push notifications from your own app enough. When you can make your client's financial lives more simple and less stressful - you win. Let me know what you think, and DM me or click to access our demo app to experience this for yourselves! https://lnkd.in/ehfZ5Hfi 👈 Book A Demo Here Fynancial
- ClairRecorded 20 Sept 2026
Our product had a flaw: New users would log in on their first day of work, often their most financially stressful moment, and see a $0 available balance. This failed them when they needed us most. We became obsessed with solving this. Our data science team dug in and found a powerful insight: employees enrolled at Clair in their first 20 days of tenure are 30% more likely to get a paycheck than those with a longer tenure. This insight allowed us to build "Day One Dollars," a responsible way to underwrite new employees. We've now helped thousands of workers bridge the gap to their first paycheck. In this video, I explain how this data-driven approach is key to building a truly responsive financial system.
- FuelfinanceRecorded 20 Sept 2026
Big day. For me, for our team, and for every founder who’s lost sleep over the numbers. Fuelfinance is introducing AI CFO. Every founder faces the same pain: You have to decide fast, but you don’t always have the right numbers at your fingertips. That’s when founder’s anxiety kicks in — and mistakes get costly. So we built Fuel AI CFO to end the guesswork and anxiety. From now everyone can be a CFO, or at least financial analyst. I'll be your anti-trend voice saying this: Our AI CFO will NOT replace a human CFO. Boom! Empowering human CFO to be faster, smarter and more efficient — yes. Help everyone in the team be a financial analyst without bothering or making hundreds of requests to the financial team — yes. If you’re hoping for a magic button that runs your whole finance team... sorry. Not happening. Not now, maybe not yet. But here’s how it works: AI CFO is built right into the Fuel FP&A platform as a chat and trained exactly on your data. Not some imaginary, irrelevant numbers. And it’s all about accuracy, not just speed. Instead of guessing, you get: → Run “what if” scenarios on every key decision in seconds. No more waiting a week to know what happens if expenses spike, or if a major customer pays late. → Pull any analysis you need, build a dashboard or report and add it to your finance system in seconds by asking in chat. → Get anomalies alerts to see where you have discrepancies between different data sources. Get recommendations on how to fix them But the thing I’m proudest of — the feature that no one else does: Fuel AI CFO displays a data quality score banner right above every answer. You’ll always know whether it’s a 100% reliable insight based on solid data, a directional finding, or something that needs more data for accurate estimation or prediction. We don’t promise 1-click setup. We promise the right numbers. We’re opening access in waves. Spots are limited for the first release. Join the waitlist for early access: https://lnkd.in/gx95mJzt
- FuelfinanceRecorded 20 Sept 2026
How will business finances look in two years? This is how I see it… Recently Jason M. Lemkin made a bold prediction: CRMs will become the backend, and agents will be the main interface. You won’t even touch the sales platform directly. You’ll just talk to an agent, and it’ll get things done. Finance is next. Actually, it’s overdue. In two years, here’s where we’ll be: 🟢 AI agents will be main interface. Every company will have AI agents sitting on top of their ERP and FP&A systems. The old infrastructure with the messy spreadsheets, the stitched-together accounting tools will be hidden underneath. The agent will be the front door. You’ll just ask for what you need: How did our margins compare to last quarter? What’s the safest way to improve profitability? Benchmark us against last year’s top performers? 🟢 Finance team’s capacity won’t be bottlenecks anymore. Data won’t be trapped in one department or buried in some analyst’s drive. Suddenly, every founder, every team lead, every board member can act like they have their own personal CFO on call, 24/7. 🟢 No special training. Just clear answers, in plain language, right when you need them. Of course, we’re not there yet. Ask any CFO: AI loves to hallucinate, and clean data is still a battle. Common agents need rules, standards, and expert training otherwise, you get faster bad decisions, not better ones. But we’re building for this future at Fuel. We’ve just introduced Fuel AI CFO that is reliable, accurate, and actually helpful, so founders, and teams can finally get finance out of the back office and into the real-time conversations that drive the business. Fuel AI CFO already do → Instant what-if modeling to evaluate pricing, hiring, and cash-flow impacts. → On-demand dashboards and reports. → Automated board-ready reports. → Real-time anomaly detectiona → Real-time benchmarking → Data quality check score Get early access in the comments. The future of finance isn’t static reports, or yet another dashboard you barely use. The future is where everyone can be a financial analyst talking just plain English. Founder, CFOs, your thoughts?
- fincrm GmbHSince 5 Jan 2026
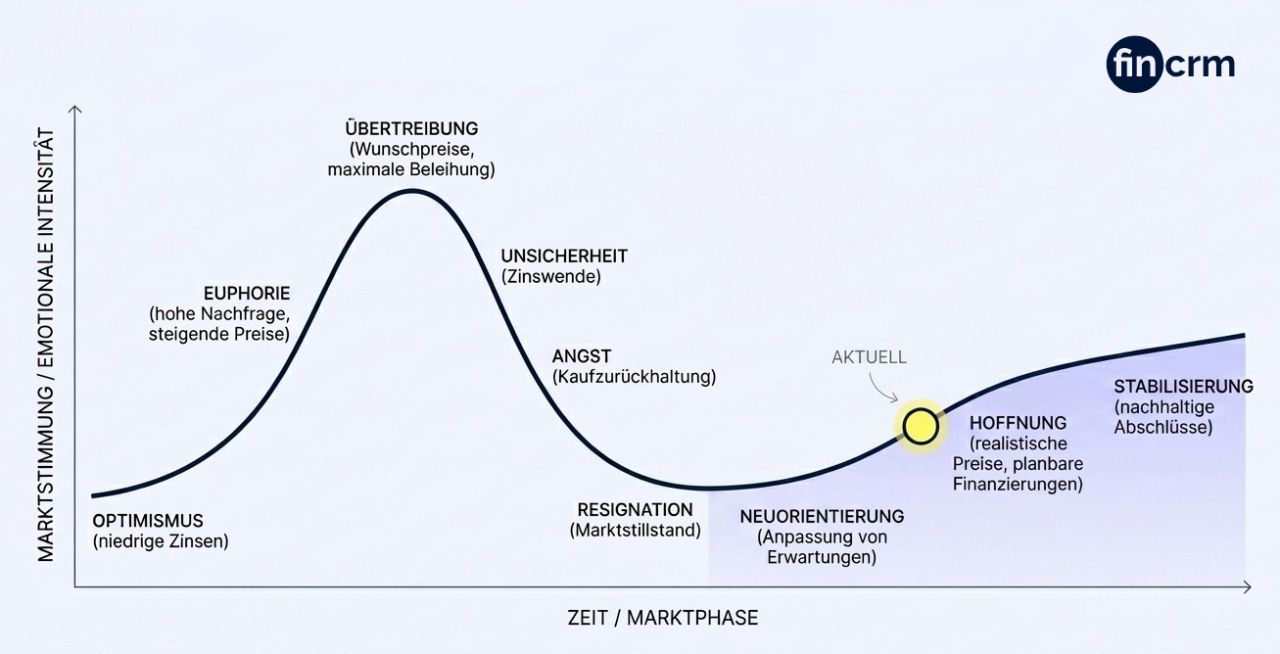
📈 Alle reden nur über Zinsen 📈 Und nicht über Probleme, die wir wirklich beeinflussen können. 2026 wird kein Jahr, in dem der Baufi-Markt „von allein“ wieder anspringt. Wenn wir nichts ändern, bleibt´s bei den Prognosen: Viel Arbeit, moderate Abschlüsse, viel Reibung, wenig Tempo. Leichtes Wachstum. Aber nicht, weil die Menschen keine Lust auf #Eigentum haben. Sondern, weil #Erwartungen, #Umfeld und #Prozesse nicht mehr richtig zusammenpassen. 👉 Wenn wir 2026 mehr wollen, müssen wir das ändern, was wir wirklich beeinflussen können: 1️⃣ Käufer: 👉 Realistische Ansprüche Reihenhaus, Bestand und sanierungsbedürftige Objekte in guter Lage statt freistehendem Einfamilienhaus. 👉 Konsum vs. Vermögen 3x Urlaub im Jahr + Zweitwagen sind direkt nach Kauf oft eben nicht mehr drin. 👉 Frühzeitige Finanzierungsberatung. Saubere Unterlagen und realistische Haushaltsrechnung sind Pflicht 👉 Weniger „Traum“, mehr „Plan“ 2️⃣ Verkäufer: 👉 Die Zeiten von Wunschpreises sind endgültig vorbei. Preise müssen Zinsen, Zustand & Energieeffizienz berücksichtigen. 👉 "Aber vor 2 Jahren..." ist kein Argument mehr. 3️⃣ Immobilien Makler: 👉 Vom Türöffner zum echten Begleiter 👉 Exposé + ImmoScout-Account reichen 2026 nicht mehr 👉 Langfristige Reputation schlägt schnellen Abschluss Realistische Preise, Qualifizierung der Interessenten + echte Betreuung 👉 Zusammenarbeit mit Finanzierungsvermittlern Daten- und Unterlagenqualität entscheiden über Abschlussgeschwindigkeit 4️⃣ Finanzierungsvermittler: 👉 "Nicht so einfach" ist das neue "normal" Hausaufgaben machen: Plattformlogik, Bankfibeln, Fördermittel, Szenarien-, Haushalts- und Lebensphasenplanung... 👉 Automatisierung & Digitalisierung entscheiden. Zeit für die professionelle Beratung der Kunden. 👉 Regionale Partnerschaften mit Maklern & Banken Vertrauensvolle, langfristige Partnerschaften statt teurer, anonymer Baufi von der Stange 👉 Antragsqualität wird zum Wettbewerbsfaktor Vollständige Unterlagen, plausible Daten, saubere Struktur. 5️⃣ Banken: 👉 Einfache, transparente Produkte & mehr Digitalisierung Für schnelle, digitale & eindeutige Entscheidungen 👉 Eigen- und Plattformgeschäft schließen sich nicht aus Sie ergänzen sich: starker Eigenvertrieb + skalierbares Vermittlergeschäft 👉 Fast-Lane für kontinuierlich gute Antragsqualität 6️⃣ Politik: Rahmenbedingungen schaffen 👉 Grunderwerbsteuer runter/weg Mindestens für die 1. selbstgenutzte Immobilie 👉 Ist es noch angemessen, dass ein Registereintrag ~2k kostet? 👉 Planbare, verlässliche & zielgerichtete Förderprogramme (KFW + Länder) Für Familien, mittlere Einkommen, energetische Sanierung
- fincrm GmbHSince 6 Jan 2026
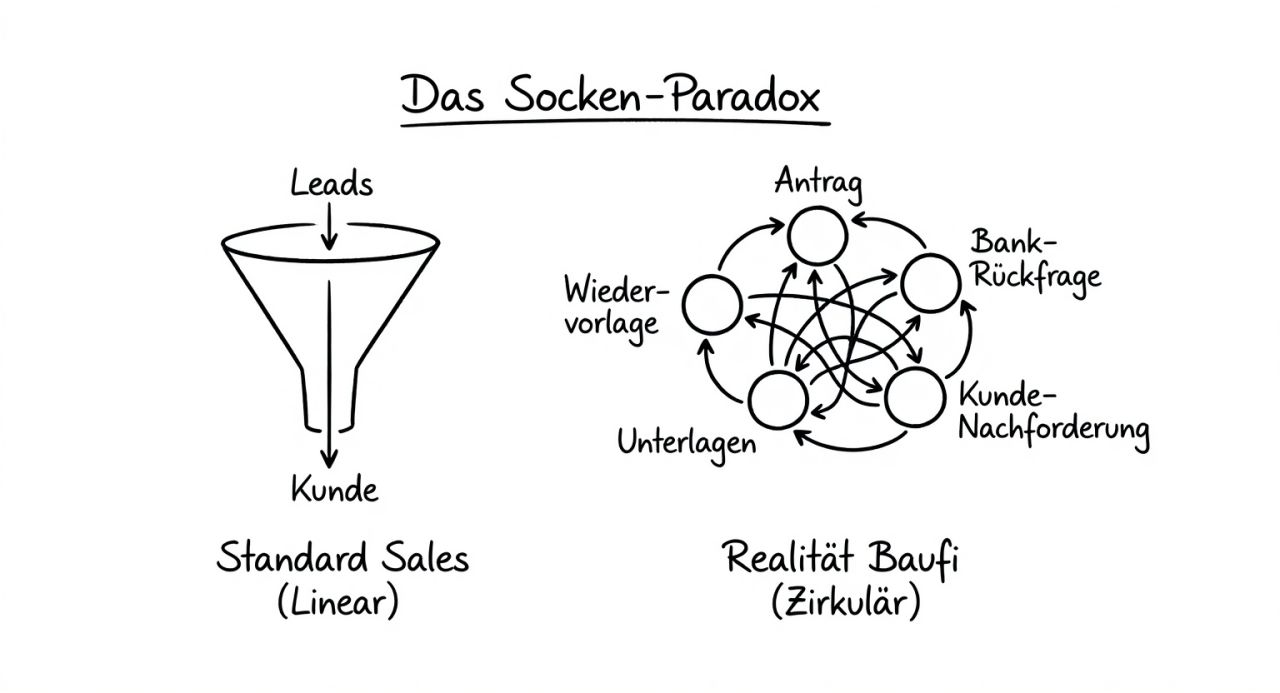
Ein CRM für Socken-Verkäufer funktioniert nicht für Baufinanzierungen. HubSpot, Pipedrive und Co. sind großartige Tools. Wenn man Socken, Standard-Produkte oder einfache Dienstleistungen verkauft. Warum? Weil diese Tools auf einem linearen Trichter (Funnel) basieren: Lead rein ➔ Angebot ➔ Abschluss ➔ Won/Lost. Die Realität in der Baufinanzierung ist aber nicht linear. Sie ist ein Kreislauf: Kunde reicht ein ➔ Unterlagen fehlen ➔ Nachforderung ➔ Bank fragt nach ➔ Zins ändert sich ➔ Finanzierung muss umgebaut werden ➔ Zurück auf Start. Wer versucht, dieses "Ping-Pong" in einen starren Sales-Funnel zu pressen, baut sich kein System, sondern ein Gefängnis aus Workarounds und benutzerdefinierten Feldern. Ihr verliert den Überblick, weil das Tool für einen Prozess gebaut wurde, den ihr gar nicht habt. Spezialisierung schlägt Generalisierung. Ihr braucht keinen Trichter. Ihr braucht ein Cockpit, das Rückfragen, Nachforderungs-Schleifen und Bank-Prozesse nativ versteht. Nutzt ihr noch "Socken-Software" oder schon Branchen-Tools? #Baufinanzierung #CRM #Prozesse #fincrm #Spezialisierung
- FinampSince 25 Mar 2026
A lot of founders compare BaaS and EMI as if they were two versions of the same choice. In practice, they solve different problems. An EMI is a regulatory footing. A BaaS setup is a launch model. That distinction matters because most founders are not really deciding between two labels. They are deciding how much of the regulated stack to own now, how quickly they need to launch, and how much operational burden they are ready to carry in the first 12–24 months. The attraction of BaaS is obvious – it gets you into a live regulated perimeter faster and lets the team focus on the product layer: onboarding, transaction flows, support handling, admin visibility, and the operational detail users actually feel. The attraction of EMI is different – it gives more direct control over the regulated e-money layer and reduces long-term dependence on a sponsor. But it also brings earlier responsibility for safeguarding, reporting, governance, and control discipline. This is where the comparison often goes wrong. Teams assume EMI means independence. Or they assume BaaS means outsourced compliance. However, neither is quite true. Even with a sponsor-led route, the product still has to behave in a way the partner can defend. Clear transaction states, complaint workflows, permissions, monitoring, and evidence trails still matter. And with EMI, those same operational realities do not disappear just because the regulatory status is yours. So the founder question is usually much simpler than the debate makes it sound: Do you need regulatory ownership now? Or do you need launch speed without building the wrong burden too early? That is usually where the real decision becomes clear. 👉Book a Call with Finamp: https://lnkd.in/eqXZuzSS Full breakdown here 👇https://lnkd.in/eC_3aEBU #Fintech #Neobank #BaaS #EMI #FintechMVP #ProductStrategy #DigitalBanking #Payments
- FinampSince 1 Apr 2026
BaaS can speed up your launch and quietly weaken your control at the same time. That risk often starts showing up during implementation. The logic feels straightforward: use a BaaS partner, avoid building regulated infrastructure from scratch, move faster, focus on the product users actually see. In many cases, that is still the right move. But it comes with a dependency many teams underestimate. Then the integration starts revealing the real operating model. The sandbox is more limited than expected. There is no proper staging environment. A provider-side issue takes days or weeks to resolve. Your team still owns the customer experience, but no longer controls the resolution speed. This is usually how BaaS risk appears in practice. Not as one dramatic outage, but as dependency concentration. Your product depends on someone else’s API maturity, release discipline, support quality, incident response, and access to production truth. One common trap is sandbox confidence. The demo works. Internal stakeholders see a clean journey. The team assumes production is mostly an execution exercise. Production rarely behaves that neatly. If the sandbox cannot reflect the full payment journey, and the provider does not offer proper staging, the integration usually becomes more expensive because too much risk is discovered late. The strongest defence is the product layer above the provider layer. Your internal transaction lifecycle should stay stable even when the provider is slow to respond. Your support team should be able to reconstruct outcomes without waiting for someone else’s queue. Your operations model should survive provider-side issues without turning every incident into a roadmap event. That is usually the difference between a BaaS-led product and a BaaS-dependent product. 👉Book a Call: https://lnkd.in/eqXZuzSS Read more on BaaS hidden risks👇: https://lnkd.in/dH2PMp32 #Fintech #Neobank #BaaS #FintechMVP #ProductStrategy #Payments #OperationalResilience #DigitalBanking
- FLOASince 6 May 2026
👍 Excellent échange avec Gilles Leclerc pour La Tribune sur la révolution en marche des facilités de paiement et les enseignements du baromètre FLOA x Kantar.
- fiskalySince 10 Jun 2026
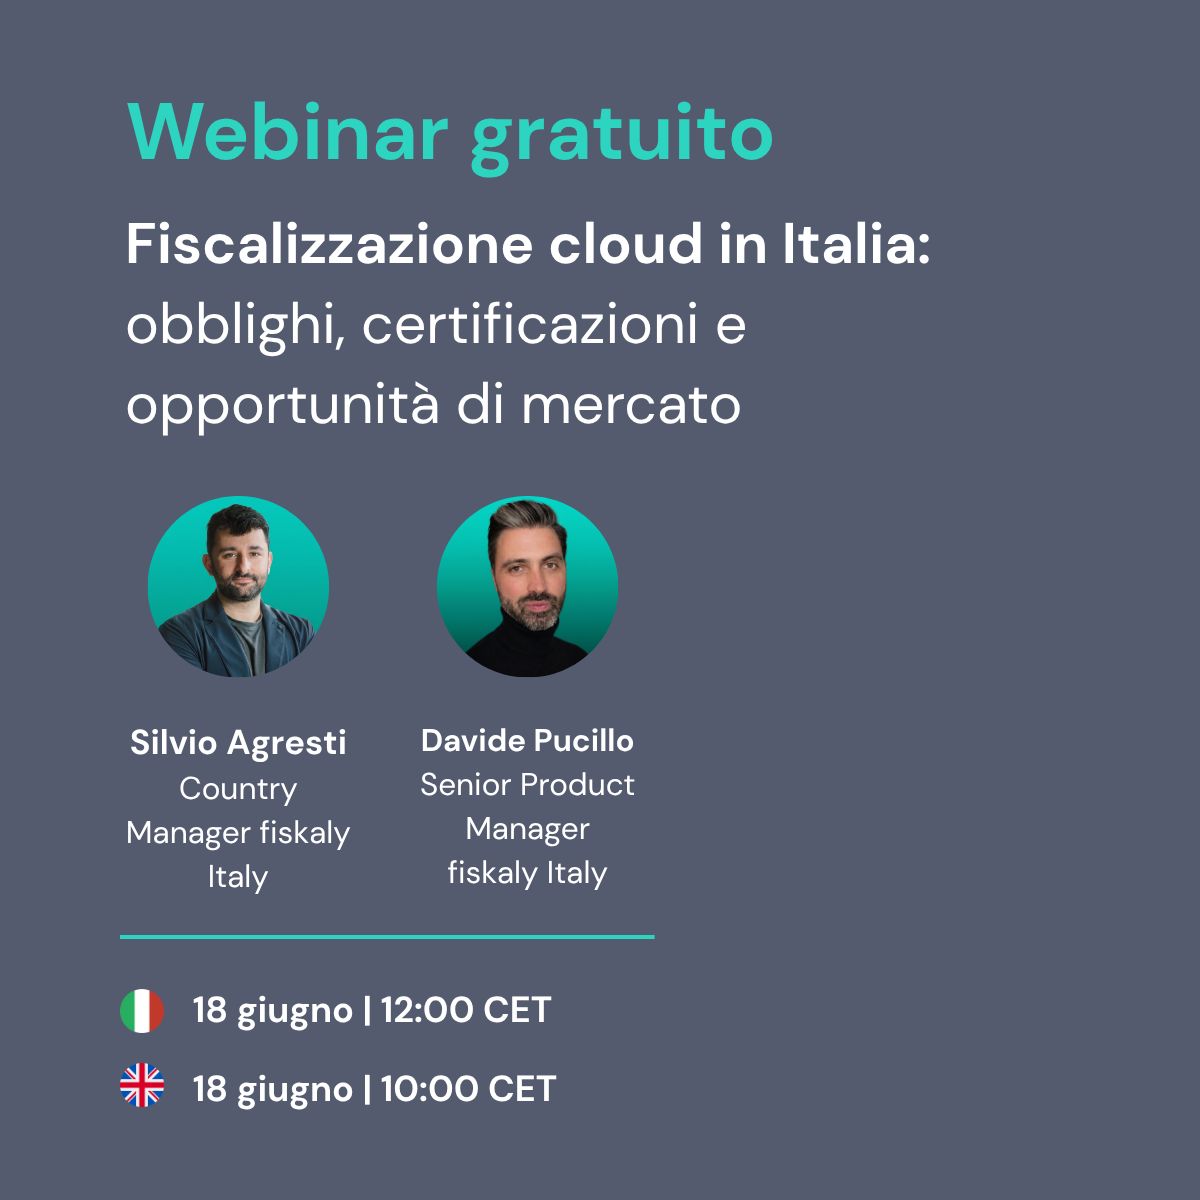
Nel recente incontro promosso da AssoSoftware con Agenzia delle Entrate e Sogei, a cui ho partecipato, è stato confermato che nel 2027, accanto al rinnovo dei registratori telematici in scadenza si affiancherà la soluzione software certificata come alternativa sostitutiva. fiskaly è già tra i player selezionati per la Pilot Phase della certificazione con la sua soluzione in cloud SIGN IT. Il 18 giugno Silvio Agresti, Country Manager Italy e Davide Pucillo, Senior Product Manager Italy, conducono un webinar gratuito su cosa significa questa transizione per ogni software house, fornitore di POS e operatore retail in Italia. Prenota il tuo posto, è gratuito 👉 https://shorturl.at/DRwAL
- finperksSince 9 Jul 2026
We sat down with Zalando to understand how they think about gift cards. And of course, why they're working with finperks, a start-up supplier, to amplify their reach 💪 Dr. Moritz Zoellner put it clearly: "From Zalando's perspective the gift card has several purposes. Rewarding our loyal customer base, reactivating customers, which is one of the key things for the next years, and new customer acquisition." So the question becomes: how do you reach all three audiences without building distribution from scratch for each one? Moritz's answer points straight at the gap finperks fills: "What finperks offers is access to new, high-value distribution channels that are typically hard to tap into directly, like banking apps and corporate benefit platforms." What stood out in the conversation: ✔️ Gift cards reach customers who do not convert through standard checkout. The shopper sitting inside a banking or benefits app, not browsing the store, who buys a Zalando card and spends it later. ✔️ Loyalty, reactivation, and acquisition served from a single integration. A loyal customer on our partner app buys one to treat themselves, a lapsed customer comes back for a cashback offer, and a new buyer discovers Zalando inside an app they already use. ✔️ A loaded card is committed money. That turns a single top-up into several trips to the store over the following weeks. Self-use is also growing and virtual prepaid payments in Apple/Google Wallets. On top of that, European channels are key, with Robert Gentz saying, "Our ambition is margin expansion in Europe...." quoting geographic expansion into new countries. Zalando can't distribute gift cards across 28 European markets through one partner usually. Different settlement and compliance standards per market. We collapse this chain into one with an API. Grateful for the conversation, and for the chance to learn from a team operating at this level. Thank you for your trust and sitting with us ! Are you a brand wanting to expand your reach with gift cards in high-growth, unconventional channels? We have something for you 🚀 Full case study in the comments 👇
Other LinkedIn formats
Watch the companies you care about.
Filter every ad by industry, country, format and network, and get alerts when a company you watch starts running new ads.