Not on air · 3 of 3 networks checked

LoVasco ads
- lovascogroup.com
- Financial Services
- US
- 27 employees
LoVasco’s ads on LinkedIn, Meta and Google, recorded by adsrunning. Browse the latest here for free. Sign up free to see all 91. Watch LoVasco on any plan to get each new one in your feed.
Watchlist included in every plan
What LoVasco runs
- Single image · LinkedIn
- 6
| Network | Status | Live ads | Nov 2025LinkedIn activity · 52 weeksNov 2026 | Checked | Next step |
|---|---|---|---|---|---|
| None recorded | 0 | Checked 7 Nov 2026 | See all 91 ads → | ||
| Meta | None recorded | 0 | No active ads recorded on the Meta Ad Library | Checked 23 Oct 2026 | Collect them with the API → |
| None recorded | 0 | No ads found on the Google Ads Transparency Center | Checked 2 Nov 2026 | Collect them with the API → |
LoVasco has no live LinkedIn ads. Its Facebook page had no active ads on 23 Oct 2026, and we recorded no Google ads on 2 Nov 2026.
Latest ads
- LINKEDIN · IMAGERecorded 25 Sept 2026
We all know this feeling: you hand an employee a benefit guide… and watch their eyes glaze over. The truth is, employees do want to understand their benefits—they just need us to communicate in a way that feels approachable, relevant, and easy to digest. And more and more HR and communications teams I speak with are no longer willing to let this naturally take course. It’s time to get proactive, creative, and immersive. These aren’t just tweaks around the edges. We are watching companies take huge leaps forward…and those that do are reaping the rewards. In my newest article, I break down 11 ways HR teams can communicate more effectively, from mobile-first tools to personalized statements to peer-to-peer storytelling. Here’s an example: 9: Provide Personalized "Hidden Paycheck” Statements Help employees understand that their total compensation includes much more than their paycheck. Reveal the “hidden paycheck” by providing personalized statements that not only put a dollar value to key benefits but provide a breakdown of what the company pays for the given benefit versus what the employee pays. This transparency helps employees appreciate the financial investment the company makes in their overall well-being. This often gets overlooked and underappreciated if not communicated clearly and consistently. Don’t assume that everyone fully understands how the company is contributing to their total compensation and welfare. Meaningful shifts can make a huge difference in helping people feel valued and supported. Would love to hear what’s working for your team. My experiences are detailed below. What are yours? https://lnkd.in/gGSJCEKT
- LINKEDIN · IMAGERecorded 25 Sept 2026
Benefits communication has a direct impact on retention, satisfaction, and benefits utilization…that much has been proven again and again. Unfortunately, many employees feel overwhelmed by dense materials or aren’t sure where to find the information they need. Catherine Smith, LoVasco’s Managing Director of Communications, suggests this about to change for many employers. In her latest contribution to LoVasco’s Insights, she highlights practical strategies HR leaders can use to create clearer, more engaging benefits education, including multi-channel communication, manager toolkits, visual resources, and more. Here’s one that really gained traction last year, and promises to be a focus in 2026 for many employers: 8. Use Multiple Communication Formats to Suit Different Learning Styles Recognize that employees learn differently which means you need to cater to a multitude of communications preferences. Some prefer videos, while others retain information better through the written word. Offer benefits information in various forms and formats, including videos, written guides, and interactive tools, in order to accommodate these different learning preferences. One size rarely fits all. Strong communication leads to stronger teams. Stronger teams means better business outcomes. See all 11 of Catherine’s top trends in the article below. https://lnkd.in/gNrFhAWJ
- LINKEDIN · IMAGERecorded 25 Sept 2026
If you sponsor or administer a company retirement plan, you are more than a facilitator—you are a fiduciary. And with that designation comes significant legal and financial responsibility. Many plan sponsors are surprised to learn that fiduciary liability is personal, not just corporate. If you exercise any discretion over the plan, whether in selecting investments, choosing service providers, or overseeing plan operations, you can be held personally accountable under ERISA. While this reality may sound daunting, it doesn’t need to keep you up at night. With a disciplined governance process, clear documentation, and, when appropriate, the support of outside experts, you can manage these responsibilities confidently and mitigate your risks. Failure to implement these steps can expose fiduciaries to serious consequences. The risks range from nuisance-level penalties to major disruptions: ⚠️ Audits and Investigations ⚠️ Lawsuits: ⛔️Plan Disqualification In the most severe cases, a plan can lose its tax-qualified status, with devastating consequences for both the company and employees. The good news is that regulators often allow voluntary correction of mistakes before imposing penalties. But this leniency assumes fiduciaries are monitoring their plans, identifying issues, and taking proactive steps to correct them. 👉 Being a fiduciary is not about perfection; it’s about prudence. ERISA’s emphasis on process over outcome means that by building a disciplined governance framework, documenting decisions, and seeking outside expertise when necessary, you can fulfill your obligations and protect both your employees’ retirement savings and your own liability. Recommended course of action: ✅ Ask your retirement plan consultant what fiduciary duties under ERISA really entail (including the Prudent Man and Exclusive Benefit Rules). ✅ Learn why documentation and governance are critical safeguards…and what you need to document to avoid negative consequences. ✅ Check to make sure you’re safeguarded from the most common oversights that expose plan sponsors to unnecessary risk. The risks of neglect are too great, but the solutions are straightforward. An ounce of prevention truly is worth a pound of cure.
- LINKEDIN · IMAGERecorded 25 Sept 2026
As we get closer to year-end, I’ve been spending more time with plan sponsors reviewing how their retirement plans are performing—not just from a compliance standpoint, but in terms of engagement, readiness, and alignment with organizational goals. A thoughtful review now can uncover a lot: whether your plan is meeting its intended objectives, where employees may be struggling, and what opportunities you may have before January 1 to strengthen your design. In my latest LoVasco Insights article, I walk through several areas that employers should be evaluating before the window closes, including: • Automatic enrollment & escalation – Still one of the most impactful ways to drive participation and improve retirement readiness. • Eligibility for part-time employees – A growing compliance focus under SECURE 1.0 and 2.0, and an opportunity to broaden access in a meaningful way. • Employer contributions – From Safe Harbor design to student loan matching to profit-sharing, year-end is the ideal time to rethink contribution strategy. • In-plan Roth conversions – A valuable option for employees, but one that requires education and careful communication. Beyond plan design, I also highlight why communication and education matter just as much as the technical changes — and how targeted messaging can help employees actually understand and value the benefit you’re providing. If you haven’t yet stepped back to evaluate your plan before the new year, now is the right time to do it. Deadlines arrive quickly, and missing them can mean waiting another full year to make important improvements. I’d love for you to take a look at the full article and share your thoughts: 👉 Read the full piece on the LoVasco Insights blog
- LINKEDIN · IMAGERecorded 25 Sept 2026
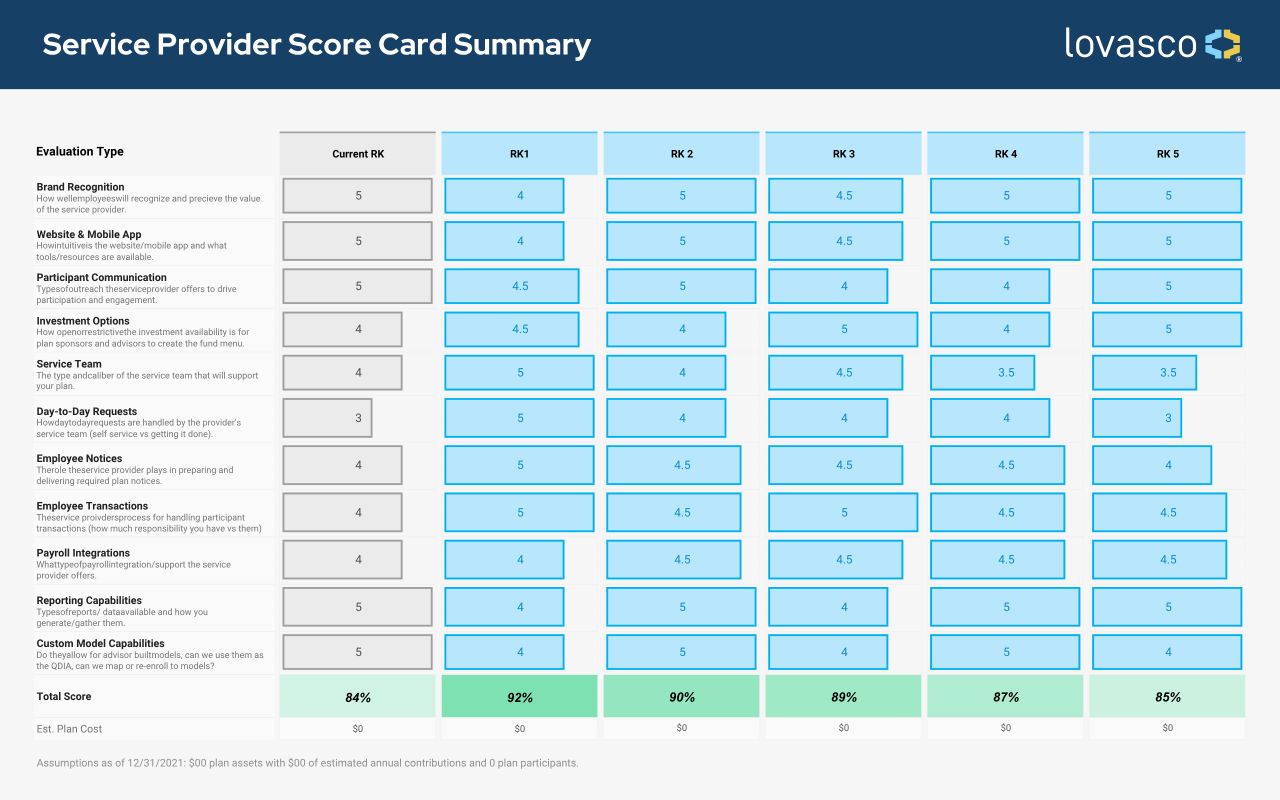
When’s the last time you took a close look at the service your retirement plan providers deliver? Not just fees. Not just investment performance. But the actual experience your organization and employees receive day to day. In my latest article for the LoVasco Insights blog, I break down why benchmarking every one to three years is a best practice…and why the most valuable insights often come from factors that don’t show up on a fee schedule. A few of the areas worth evaluating include: • Service team responsiveness – Are issues resolved quickly and proactively? • Website & mobile experience – Is it intuitive for participants? • Participant communication – Are your people getting clear, timely guidance? • Payroll integration & reporting – How seamless is the administrative side? • Investment platform flexibility – Are you limited…or empowered? At LoVasco, we use a structured, independent benchmarking process to help employers evaluate both the quantitative and qualitative value of their current providers. Sometimes the data validates that you’re with the right partner. Other times, it highlights real opportunities for improvement. (Below is a simplified visual representation of the type of matrix we walk clients through, which you can view more clearly in the article linked to below.) Either way, the goal is the same: stronger service, better outcomes for employees, and a documented fiduciary process you can stand behind. If you’d like to dig deeper, you can read the full article here: https://lnkd.in/dW9TtvCV
- LINKEDIN · IMAGERecorded 25 Sept 2026
As we get closer to a new plan year, I’ve been talking with more plan sponsors about one recurring theme: how to build a retirement plan that engages employees, stays compliant, and reduces friction for HR and leadership. In my latest article for LoVasco, I break down three strategies that consistently help organizations improve participation and strengthen their fiduciary process: 1️⃣ Safe Harbor contributions A straightforward way to avoid ADP/ACP testing issues while offering employees an immediately vested, competitive benefit. 2️⃣ Qualified Default Investment Alternatives (QDIAs) A smarter default investment approach that gives employees a diversified starting point — and gives sponsors important fiduciary protection. 3️⃣ Automatic enrollment A simple behavioral nudge that dramatically increases participation and helps employees get on track without having to take the first step themselves. Each plays a different role, but together they can: • strengthen compliance • improve participant outcomes • reduce administrative headaches • and create a smoother, more predictable plan experience If you’re evaluating your plan design for 2025 (or simply want to understand where your biggest opportunities lie), I’d love for you to take a look: 👉 Read the full article on the LoVasco Insights blog https://lnkd.in/graYD7fM
6 of 91 adsSign up to see every LoVasco ad, filter by format and date, and get alerts on new ones.
See all 91 adsQuestions about LoVasco’s ads
Is LoVasco running LinkedIn ads?
We recorded no live LinkedIn ads for LoVasco on 10 Nov 2026.
How many LinkedIn ads has LoVasco run?
LinkedIn’s ad library lists 90 ads for LoVasco. We recorded 91 LinkedIn ads for LoVasco, first recorded on 25 Sept 2026 and last recorded on 25 Sept 2026.
Does LoVasco advertise on Facebook and Instagram?
LoVasco’s Facebook page had no active ads in Meta’s Ad Library, last recorded on 23 Oct 2026.
Does LoVasco run Google ads?
We recorded no Google ads for the domain lovascogroup.com on 2 Nov 2026.
Which ad formats does LoVasco use?
The 6 LinkedIn ads on this page include 6 image ads.
Watch the companies you care about.
Filter every ad by industry, country, format and network, and get alerts when a company you watch starts running new ads.