3 new LinkedIn creatives in 30 days · 3 of 3 networks checked

Delta Financial Group ads
- deltafinancialgroup.com.au
- Financial Services
- AU
- 5 employees
Delta Financial Group’s ads on LinkedIn, Meta and Google, recorded by adsrunning. Browse the latest here for free. Sign up free to see all 65. Watch Delta Financial Group on any plan to get each new one in your feed.
Watchlist included in every plan
What Delta Financial Group runs
- Single image · LinkedIn
- 6
- Google ads on 27 Oct 2026
- 8
| Network | Status | Ads | Nov 2025LinkedIn activity · 52 weeksNov 2026 | Checked | Next step |
|---|---|---|---|---|---|
| New in 30 days | 3 of 40 creatives | Checked 8 Nov 2026 | See all 65 ads → | ||
| Meta | None recorded | 0 | No active ads recorded on the Meta Ad Library | Checked 27 Oct 2026 | Collect them with the API → |
| Recently | 8 | Ads on the Google Ads Transparency Center | Checked 27 Oct 2026 | Collect them with the API → |
Delta Financial Group has 3 new LinkedIn creatives in the last 30 days. Its Facebook page had no active ads on 27 Oct 2026, and we recorded 8 Google ads on 27 Oct 2026.
Latest ads
- LINKEDIN · IMAGERecorded 23 Oct 2026
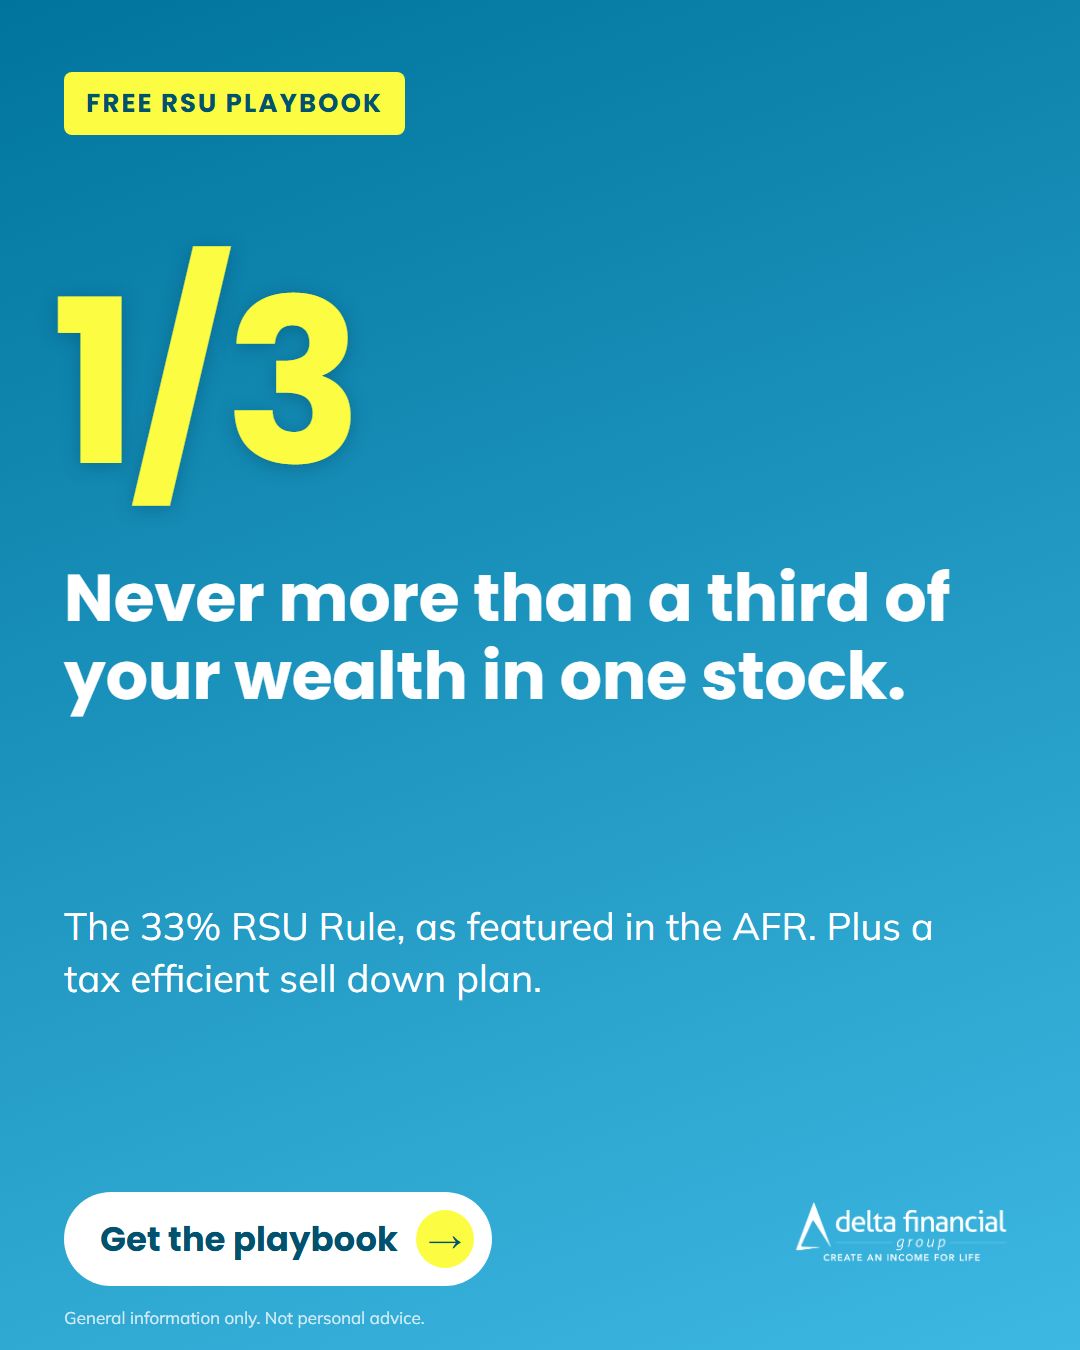
If one stock is more than a third of your wealth, you're not invested. You're concentrated. RSUs vest every quarter. Most tech execs never sell. One bad year for the stock and years of work go with it. My free RSU Playbook shows how to fix it without a big tax bill. Learn: → The 33% RSU Rule, as featured in the Australian Financial Review → A tax efficient sell down plan → What the July 2027 CGT change means for you Click below to download.
- LINKEDIN · IMAGERecorded 23 Oct 2026
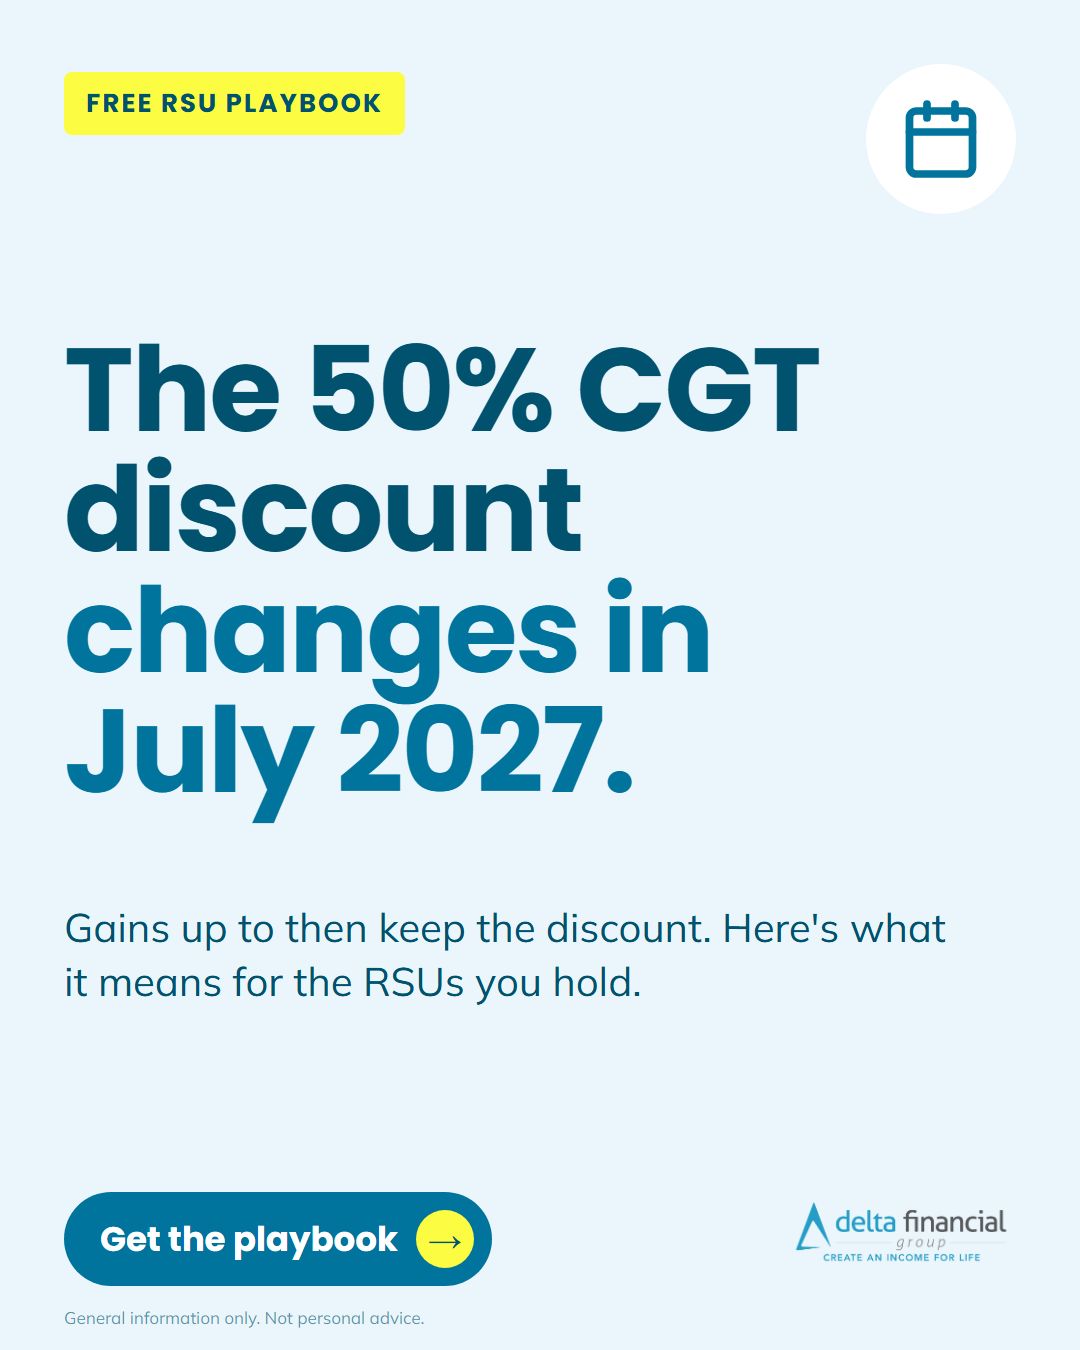
The 50% CGT discount changes on 1 July 2027. Gains up to then keep the 50% discount, even if you sell later. Growth after that is taxed differently: CPI indexation and a 30% minimum tax on real gains. If you hold vested RSUs, your long term plan just changed. I've put the rules and the moves into one free resource. The RSU Playbook for tech execs. Learn: → What the 2027 CGT change means for shares you already hold → Why your employer withholds nothing at vest → My 33% RSU Rule, as featured in the Australian Financial Review Click below to download.
- LINKEDIN · IMAGERecorded 23 Oct 2026
If you've been reading my posts, this is the next step. An Early Retirement Clarity Call. 15 minutes. No cost. We'll look at: 1. Where you are today 2. The monthly income you want in retirement 3. Whether your super, home equity and RSUs can get you there You'll leave knowing your next step. I take on 4 new clients a month. Book a time that suits you.
- LINKEDIN · IMAGERecorded 8 Oct 2026
I am 48. Here is what I would tell myself at 30 about money. I was in London at 30. Trading futures. Earning well. Saving almost nothing. I thought I had time. I did not understand what time actually costs. Here is the letter. Start your super contributions now. Not when you feel settled. Now. Every year you delay costs more than the year before. At 30 the Rule of 72 is your greatest asset. At 48 it is a reminder of what you did not do. Do not hold all your wealth in one employer or stock. I know you believe in the company. That is not the point. Concentration risk is real. Diversify from day one. Buy property sooner than you think you can. You will be surprised by what you can service. The equity you build in your 30s is what funds freedom in your 50s. Stop treating income as wealth. Income is not wealth. Structure is wealth. Every $100K you earn without a structure is $100K that works for someone else. And one more thing. The anxiety you feel about money is not because you do not earn enough. It is because you have no plan. A plan fixes that faster than a pay rise ever will. I wish someone had told me this at 30. That is why I tell it to you now.
- LINKEDIN · IMAGERecorded 8 Oct 2026
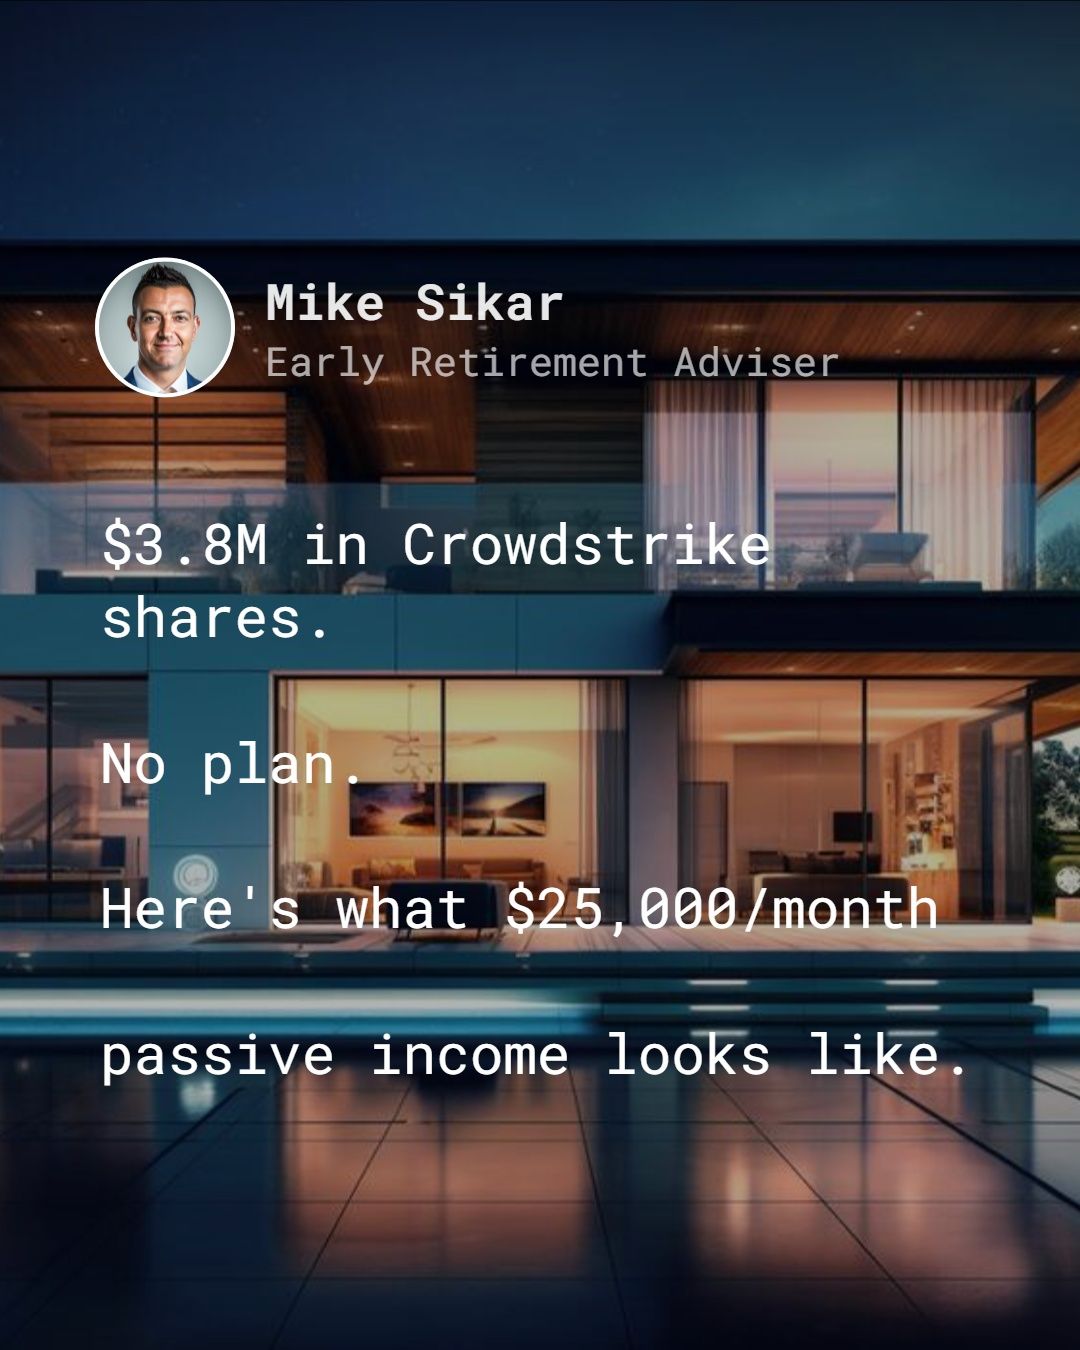
A CrowdStrike VP came to me with $3.8M in shares and no plan. Here's what we built. He had $3.8M in shares. A $5M house with zero debt. And what I call a lazy balance sheet. High net worth on paper. Zero tax deductions in reality. That's the trap most senior tech executives fall into. They build wealth. They pay off the mortgage early. They feel like they're winning. Then they realise they're sitting on millions with no tax efficiency, no leverage, and no plan to convert it into retirement income. This CrowdStrike VP was exactly there. Mid 40s. Household income well over $700K. $3M in vested shares. $800K in unvested shares he couldn't touch yet. A $5M property with no mortgage. And a question that kept him awake. "𝗔𝗹𝗹 𝗺𝘆 𝘄𝗲𝗮𝗹𝘁𝗵 𝗶𝘀 𝗶𝗻 𝟭 𝘀𝘁𝗼𝗰𝗸, 𝘄𝗵𝗮𝘁 𝘀𝗵𝗼𝘂𝗹𝗱 𝗜 𝗱𝗼 𝘁𝗼 𝗱𝗶𝘃𝗲𝗿𝘀𝗶𝗳𝘆?" Here's what we diagnosed. His balance sheet looked strong. But it was lazy. All assets sitting idle. No tax deductions. No leverage. No structure converting wealth into income. Here's what we built. 𝗦𝘁𝗲𝗽 𝗼𝗻𝗲: 𝗦𝗲𝘁 𝘂𝗽 𝗮 $𝟭𝗠 𝗶𝗻𝘃𝗲𝘀𝘁𝗺𝗲𝗻𝘁 𝗹𝗼𝗮𝗻. He had $1M in equity sitting available. No need to pay anything down first. The bank lends up to 80% of home value without LMI. He already had the equity available. We simply structured it as a separate investment loan. Tax-deductible interest on that loan. 𝗦𝘁𝗲𝗽 𝘁𝘄𝗼: 𝗦𝗼𝗹𝗱 𝗱𝗼𝘄𝗻 $𝟮𝗠 𝗼𝗳 𝘀𝗵𝗮𝗿𝗲𝘀. Not panic selling. Strategic sequencing across years to manage tax. That $2M funded a complete renovation of the family home. Transformed a lazy asset into a family experience. 𝗦𝘁𝗲𝗽 𝘁𝗵𝗿𝗲𝗲: 𝗧𝗵𝗲 𝗶𝗻𝘁𝗲𝗿𝗴𝗲𝗻𝗲𝗿𝗮𝘁𝗶𝗼𝗻𝗮𝗹 𝗺𝗼𝘃𝗲. This is where it got interesting. By selling tech shares and reinvesting the proceeds into high-end Sydney residential real estate, he's guaranteeing intergenerational wealth. When a property crosses the $7M threshold, it doubles every 10 years at 7% capital growth. So $7M becomes $14M, then $28M, then $56M. That's not just his retirement sorted. That's his kids' futures secured. We structured $500K in today's dollars as a property deposit for each of his children when they turn 25. The modelled outcome. $25,000 per month in retirement income. A renovated home his family actually enjoys. And a wealth structure that flows to the next generation. That's not just a financial plan. That's a legacy. If your wealth is sitting idle in a single stock with no structure, let's fix that. Send me a message.
- LINKEDIN · IMAGERecorded 8 Oct 2026
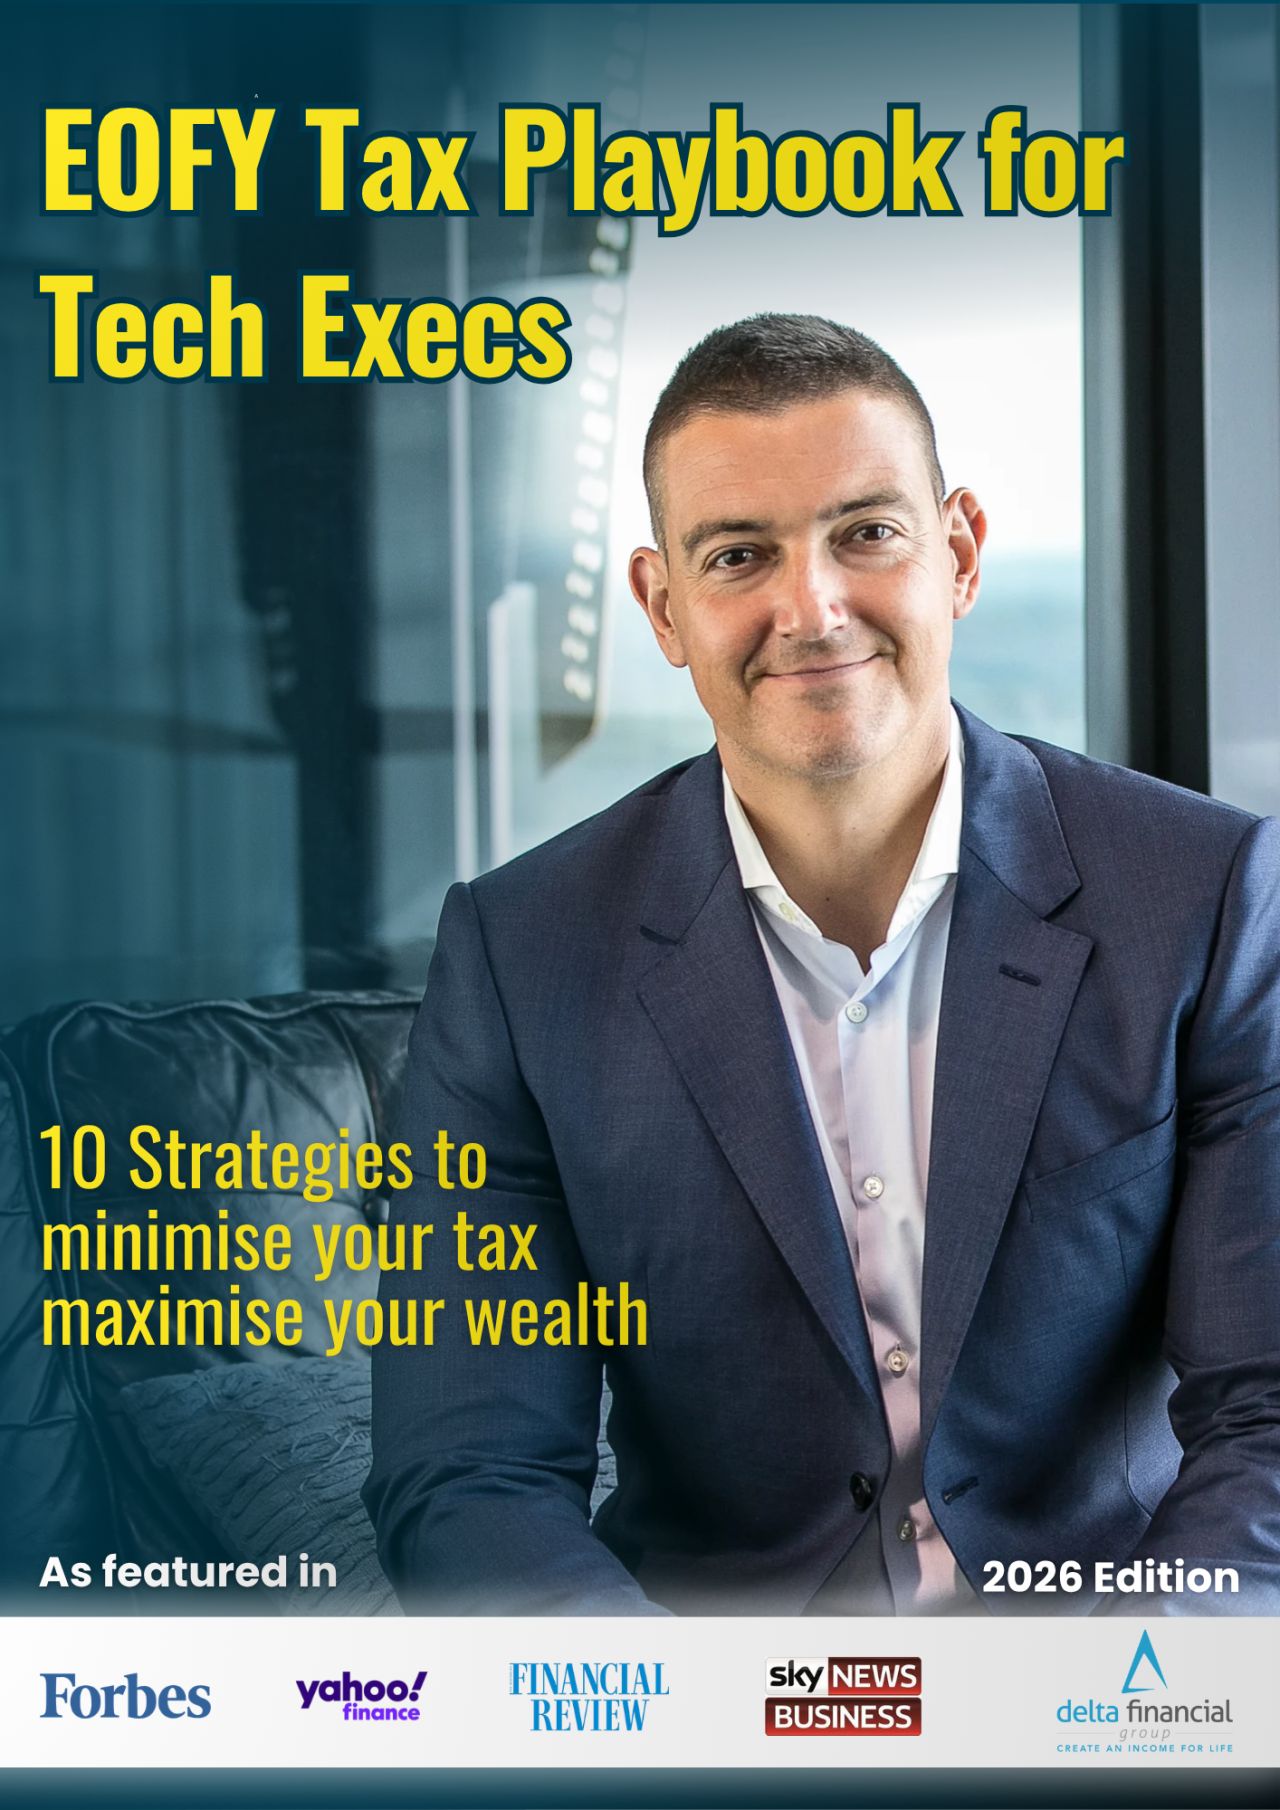
The EOFY tax playbook for tech executives. Ten strategies to minimise your tax and maximise your wealth before June 30. I have built 300+ early retirement plans for tech executives. Every June, the same question comes up. "Am I actually using this financial year well?" For a tech executive at a US global tech firm, that question has a real dollar answer. If you earn $300K to $1M with RSUs on top, EOFY is not just admin. It is the biggest tax strategy window of the year. A few well-timed moves before June 30 can save you $20K to $50K in tax. They can also move your retirement forward by two to three years. Most of these moves cost nothing. You just need to know what to do. And do it before June 30. Here is what is inside the playbook. 1. RSU Sell-Down Timing: Time your vesting and sales right. Keep more of what you earned. 2. Tax-Loss Harvesting: Sell losing positions before June 30. Use the loss to offset your RSU gains. 3. Super Contributions The deadline is June 20. Not June 30. If you have not done this yet, that is three days away. 4. Contribution Splitting With Your Spouse: Put up to 85% of contributions into your spouse's account. Lower your tax. Balance your super. 5. Downsizer Contributions: Sold a home? Aged 55 or older? You can put up to $300,000 of the proceeds into super. 6. Commencing a Pension and the Transfer Balance Cap: Time your pension start date right. Protect up to $2.1M in a tax-free environment. 7. CGT Discount Windows Hold assets for 12 months to get the 50% CGT discount. Check which positions are close to that mark right now. 8. Debt Recycling Strategy: Turn your home loan into a tax deduction. The most underused move for tech executives with a mortgage. 9. Prepaid Interest Deductions: Pay 12 months of investment loan interest before June 30. Pull the deduction into this financial year. 10. Early Retirement Planning: Where do you actually stand? The most valuable 60 minutes you can spend before July. Plus an EOFY Action Checklist. After 300+ retirement plans, this is the list I would give any tech executive right now. June 30 is 13 days away. These strategies cost nothing to do. They just need to happen before the window closes. We help Tech Execs retire early on $10K to $20K per month. This playbook is step one. Comment "EOFY" below. I will send it to you directly.
6 of 65 adsSign up to see every Delta Financial Group ad, filter by format and date, and get alerts on new ones.
See all 65 adsQuestions about Delta Financial Group’s ads
Does Delta Financial Group have new LinkedIn ads?
Yes. We found 3 new LinkedIn creatives for Delta Financial Group in the 30 days to 10 Nov 2026.
How many LinkedIn ads has Delta Financial Group run?
LinkedIn’s ad library lists 72 ads for Delta Financial Group. We recorded 65 LinkedIn ads for Delta Financial Group, first recorded on 15 Sept 2026 and last recorded on 23 Oct 2026.
Does Delta Financial Group advertise on Facebook and Instagram?
Delta Financial Group’s Facebook page had no active ads in Meta’s Ad Library, last recorded on 27 Oct 2026.
Does Delta Financial Group run Google ads?
Yes. We recorded 8 Google ads for the domain deltafinancialgroup.com.au on 27 Oct 2026.
Which ad formats does Delta Financial Group use?
The 6 LinkedIn ads on this page include 6 image ads.
Watch the companies you care about.
Filter every ad by industry, country, format and network, and get alerts when a company you watch starts running new ads.