On air · 1 of 3 networks
ARC Comply
- arccomply.com
- Fintech & Financial Services
- GB
- 12 employees
ARC Comply’s ads on LinkedIn, Meta and Google, recorded by adsrunning. Browse the latest here for free. Sign up free to see all 118. Watch ARC Comply with Starter to get each new one in your feed.
Watchlist with Starter · $49/mo
| Network | Status | Live ads | Nov 2025LinkedIn activity · 52 weeksOct 2026 | Checked | Next step |
|---|---|---|---|---|---|
| Running | 83 | Checked 30 Oct 2026 | See all 118 ads → | ||
| Meta | Not checked | — | |||
| None recorded | 0 | No ads found on the Google Ads Transparency Center | Checked 4 Oct 2026 | Collect them with the API → |
ARC Comply has 83 live LinkedIn ads. We recorded no Google ads on 4 Oct 2026.
Latest ads
- LINKEDIN · VIDEOSince 23 Oct 2026
One asset. Three lenders. None of them knew. Each lender sees its own pool and checks its own pool. Nobody looks across all three. That is how the same asset ends up securing more than one facility, and the video shows it happening. About $4.8bn of collateral that allegedly was not there, across three collapses in six months. These are allegations and claims in live proceedings, not findings of a court. What can realistically be verified, by whom, and at what point in a transaction? Luca Primerano, our CEO, joins Hassan Ahmad of Together Money, Jason Blick of CMS and Yoann Bredillot of Natixis Corporate & Investment Banking. Chatham House Rules. 𝗥𝗲𝗴𝗶𝘀𝘁𝗲𝗿 𝘆𝗼𝘂𝗿 𝗶𝗻𝘁𝗲𝗿𝗲𝘀𝘁 𝘁𝗼 𝗮𝘁𝘁𝗲𝗻𝗱 𝗼𝘂𝗿 𝗯𝗿𝗶𝗲𝗳𝗶𝗻𝗴 𝗼𝗻 𝗱𝗼𝘂𝗯𝗹𝗲 𝗽𝗹𝗲𝗱𝗴𝗶𝗻𝗴.𝗥𝗲𝗴𝗶𝘀𝘁𝗿𝗮𝘁𝗶𝗼𝗻 𝗰𝗹𝗼𝘀𝗲𝘀 𝗧𝗵𝘂𝗿𝘀𝗱𝗮𝘆 𝟮𝟮 𝗢𝗰𝘁𝗼𝗯𝗲𝗿. Register here - https://lnkd.in/egX94EBa
- LINKEDIN · IMAGESince 15 Oct 2026
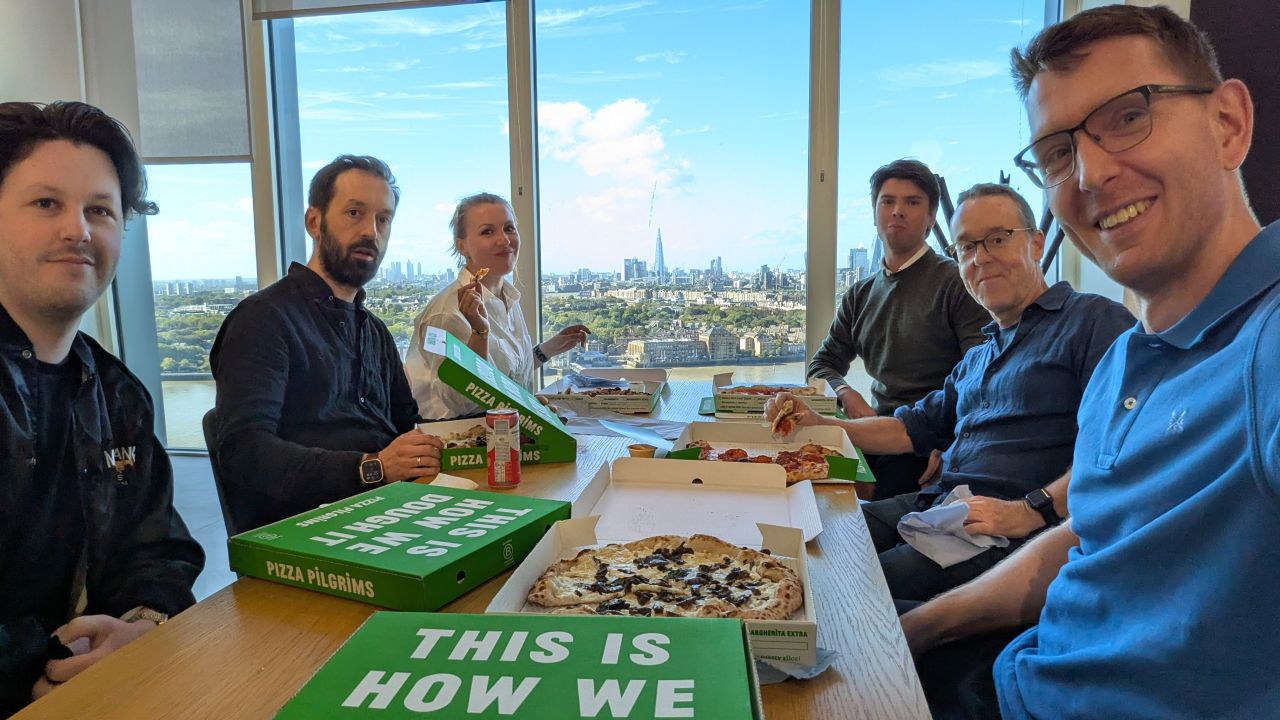
Fuelled by carbs and spirited debate. 🍕 The team spent the day planning the next 30 days of our product roadmap. A few highlights: 🔹Rethinking insurance compliance workflows with simpler, more intelligent processes built around how insurers operate. 🔹Smarter screening, fewer false positives with more precise risk detection and less manual investigation. 🔹Going beyond collateral screening with advanced cash flow anomaly detection across complex securitisation portfolios. What’s your team’s go-to fuel for a big planning day? 👇
- LINKEDIN · IMAGESince 15 Oct 2026
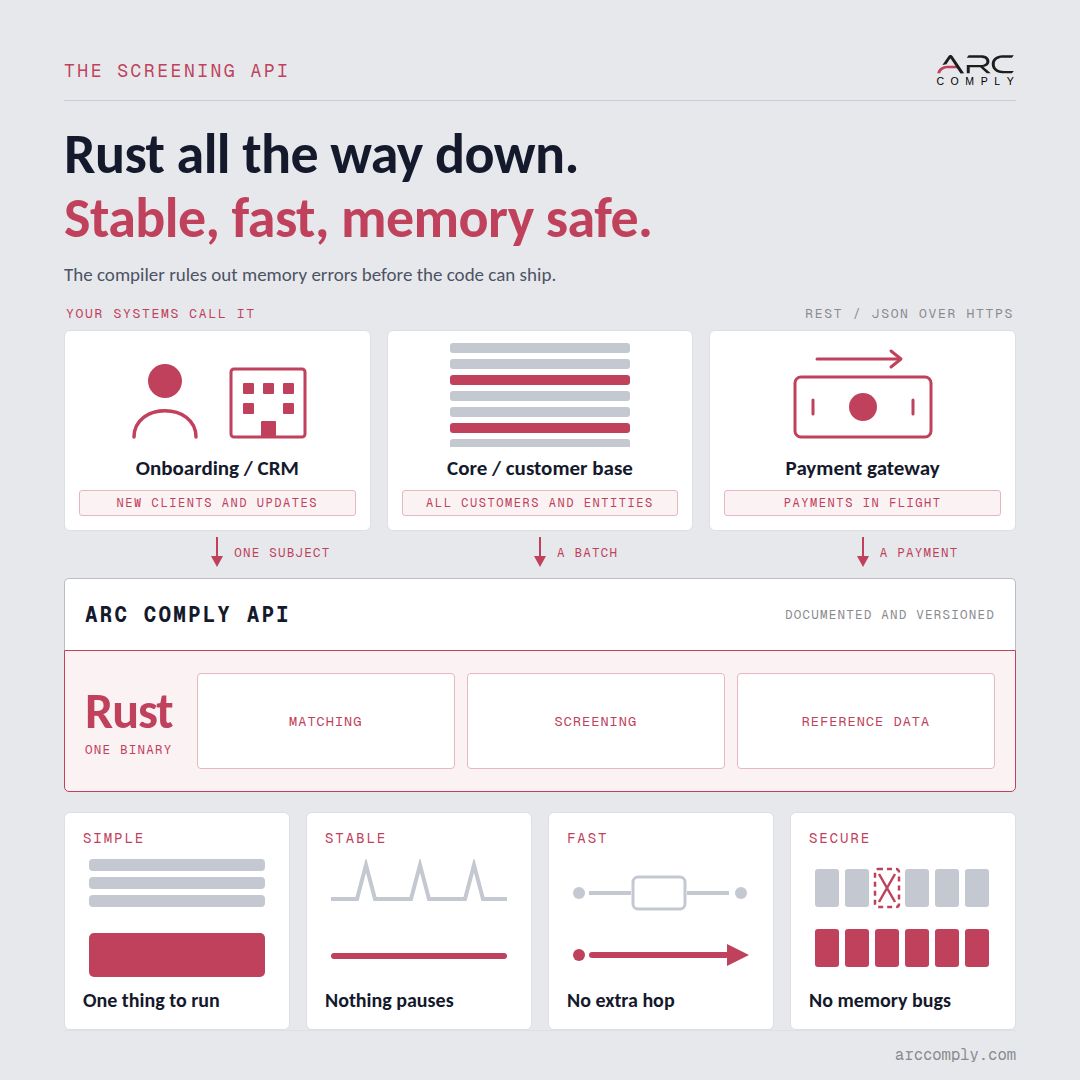
At ARC Comply we are using Rust for our backend it allows us to develop secure software that runs fast and is easy to integrate with existing workflows.
- LINKEDIN · IMAGESince 15 Oct 2026
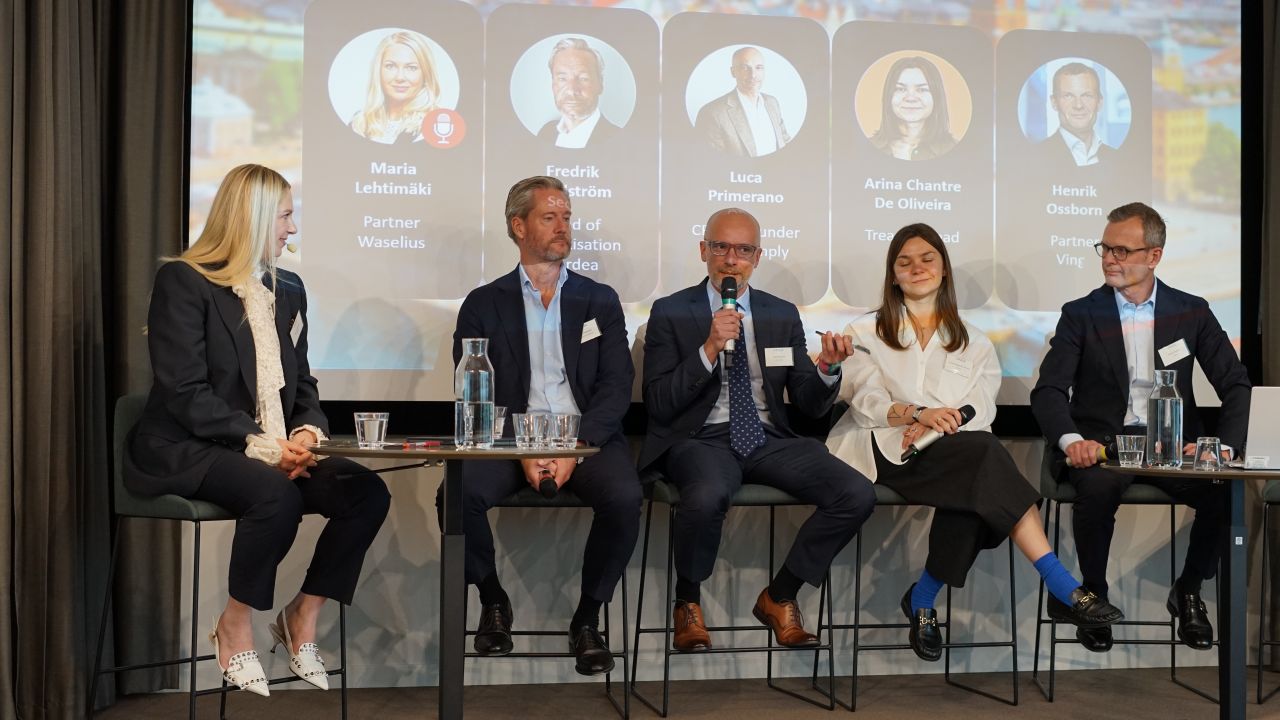
Last week in Stockholm our CEO Luca Primerano joined a panel at the Nordics Symposium, "Securitisation: Charting a New Course" organised by PCS His key message: a £1 payment can be screened in milliseconds against fraud, sanctions and money laundering. A £500 million collateral pool is still often checked by taking a sample. 1. We have it backwards. Tiny payments are screened at scale. Huge pools of collateral are still largely sampled. 2. Fraud is adversarial. Sampling works for random errors. Fraud adapts to the way you check and the problem may not even be in your data room. It may be in someone else's. 3. Fraud lives in the tail. Sampling tells you about the average asset. The dangerous anomalies are precisely the ones outside the average. 4. AI needs to explain itself. "This loan scored 87" is not enough. "This VIN also appears in another facility, and here is the evidence" is. The market should move from sampling to screening: every asset, against every other asset we can see.
- LINKEDIN · IMAGESince 15 Oct 2026
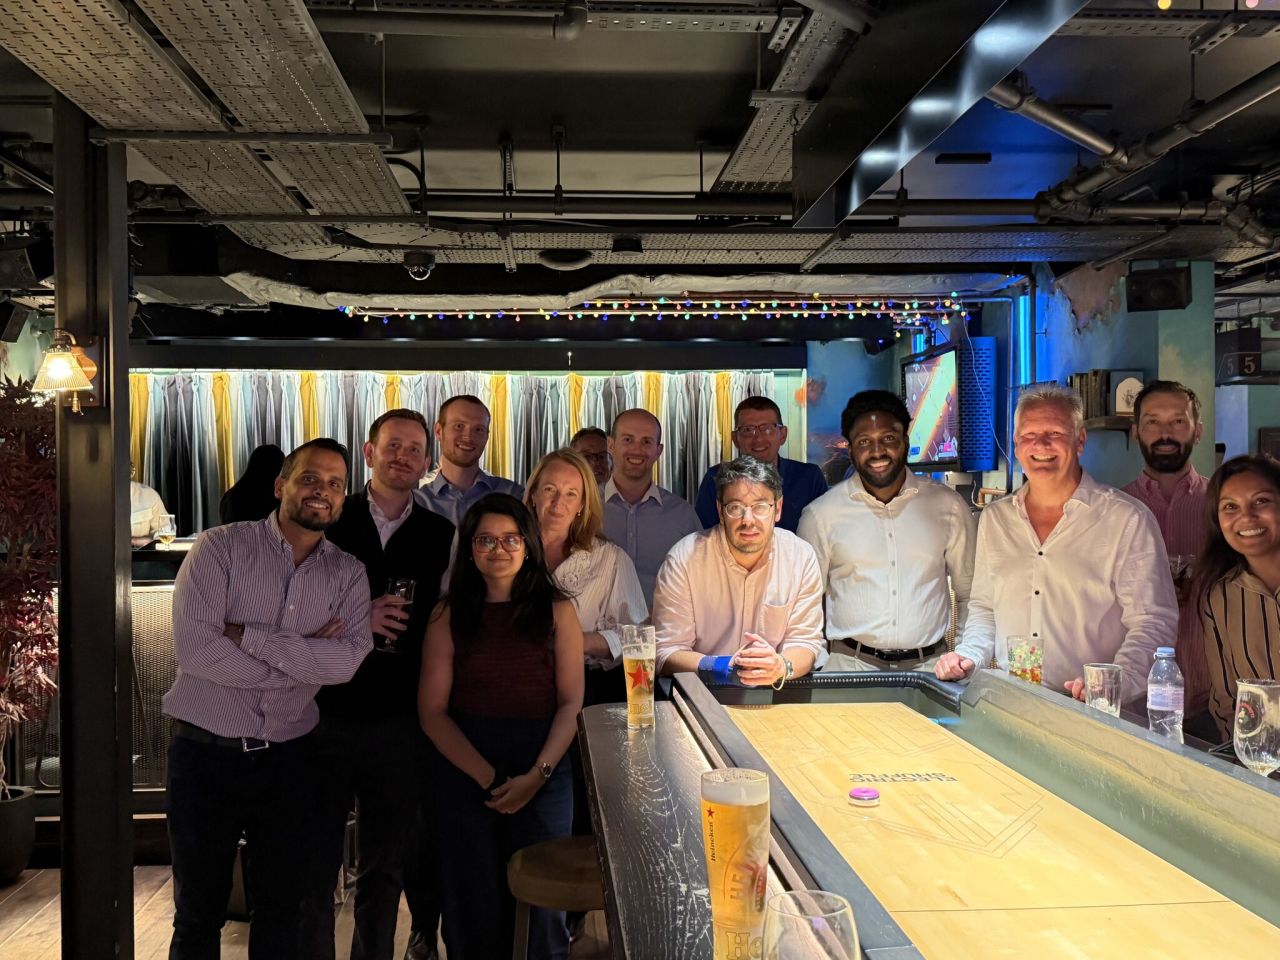
A fabulous evening of shuffleboard brought the ARC Comply team together with colleagues from across the ARC Risk Group. It may be a cliché, but spending time together away from the rock face really does make a difference, especially when teams are growing quickly. A big thank you to our Social Committee for organising the evening, and congratulations to gold medallist Riya Modi! Special mentions also go to ARC Comply’s Soagny Tsisatrana and Attila Balázs, who were among the medals. #TeamARC #TeamBuilding #Shuffleboard
- LINKEDIN · IMAGESince 12 Oct 2026
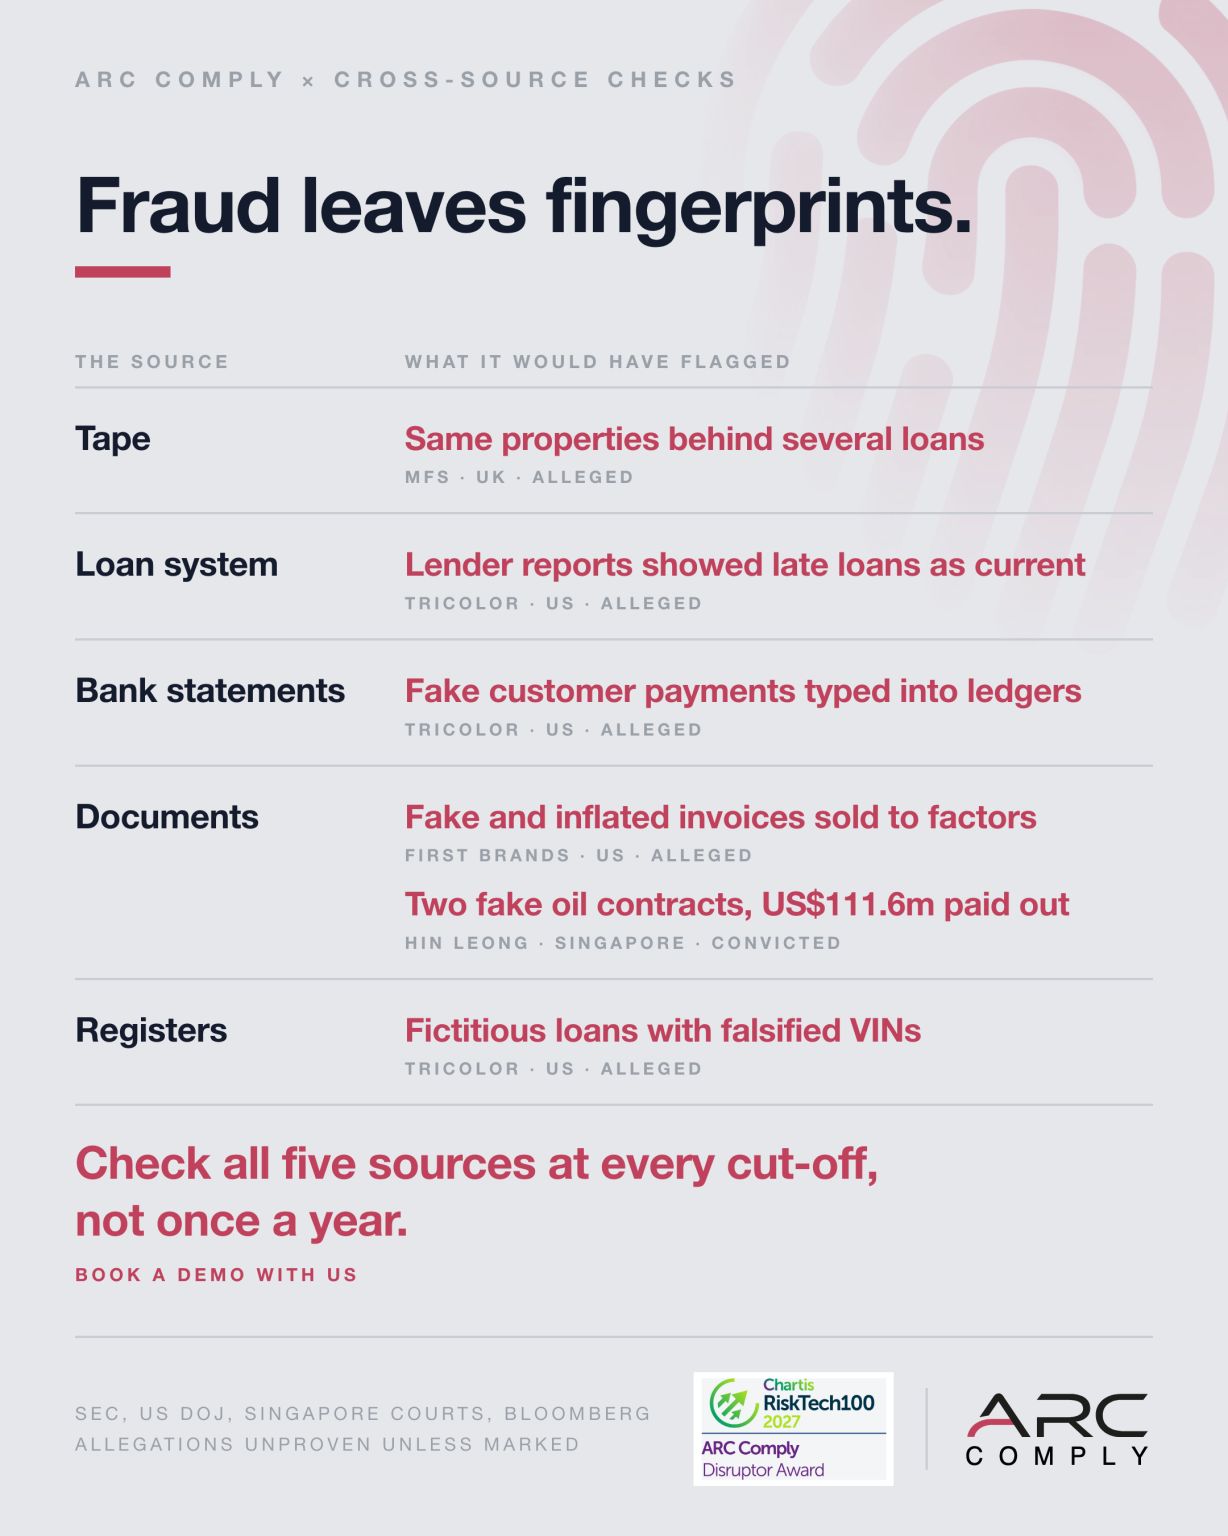
𝗙𝗿𝗮𝘂𝗱 𝗹𝗲𝗮𝘃𝗲𝘀 𝗳𝗶𝗻𝗴𝗲𝗿𝗽𝗿𝗶𝗻𝘁𝘀. Tricolor told its lenders it had about $2.2bn of collateral. Prosecutors say about $1.4bn of it was real. The gap was sitting in the data the whole time. Every collateral fraud leaves a trace, and rarely in just one place. Here are the five sources we check against each other, and the case that shows why each one matters. 𝗧𝗮𝗽𝗲. Does the same asset turn up behind more than one loan? 𝗠𝗙𝗦's own funding vehicles allege the same properties secured several loans. About £1.2bn was owed against roughly £230m of collateral. 𝗟𝗼𝗮𝗻 𝘀𝘆𝘀𝘁𝗲𝗺. Does the tape agree with the originator's own books? The 𝗧𝗿𝗶𝗰𝗼𝗹𝗼𝗿 indictment alleges staff edited delinquency dates in lender reports so late loans looked current. 𝗕𝗮𝗻𝗸 𝘀𝘁𝗮𝘁𝗲𝗺𝗲𝗻𝘁𝘀. Did the payments on the ledger ever reach the bank? Tricolor staff are also alleged to have typed fake customer payments into loan ledgers ahead of audits. 𝗗𝗼𝗰𝘂𝗺𝗲𝗻𝘁𝘀. Do the papers agree with the tape and with each other? US prosecutors allege 𝗙𝗶𝗿𝘀𝘁 𝗕𝗿𝗮𝗻𝗱𝘀 sold factors fake and inflated invoices. In Singapore, 𝗛𝗶𝗻 𝗟𝗲𝗼𝗻𝗴's founder is serving 13.5 years after two fabricated oil sale contracts got a major bank to pay out US$111.6m. 𝗥𝗲𝗴𝗶𝘀𝘁𝗲𝗿𝘀. Is the collateral real, and does it match the tape and the loan system? The SEC alleges Tricolor created fictitious loans by falsifying VINs. Hin Leong is a conviction. The rest are allegations and have not been proven. Check all five sources at every cut-off, not once a year. Book a demo by contacting Sean Bowerman #AssetBackedFinance #PrivateCredit #Securitisation #FraudPrevention
6 of 118 adsSign up to see every ARC Comply ad, filter by format and date, and get alerts on new ones.
See all 118 adsWatch the companies you care about.
Filter every ad by industry, country, format and network, and get alerts when a company you watch starts running new ads.