Not on air · 2 of 3 networks checked
Algorithmica
- algorithmica.com
- Fintech & Financial Services
- SE
- 30 employees
Algorithmica’s ads on LinkedIn, Meta and Google, recorded by adsrunning. Browse the latest here for free. Sign up free to see all 58. Watch Algorithmica with Starter to get each new one in your feed.
Watchlist with Starter · $49/mo
| Network | Status | Live ads | Nov 2025LinkedIn activity · 52 weeksOct 2026 | Checked | Next step |
|---|---|---|---|---|---|
| None recorded | 0 | Checked 30 Oct 2026 | See all 58 ads → | ||
| Meta | Not checked | — | |||
| Recently | 5 | Ads on the Google Ads Transparency Center | Checked 1 Oct 2026 | Collect them with the API → |
Algorithmica has no live LinkedIn ads. We recorded 5 Google ads on 1 Oct 2026.
Latest ads
- LINKEDIN · IMAGESince 23 Oct 2026
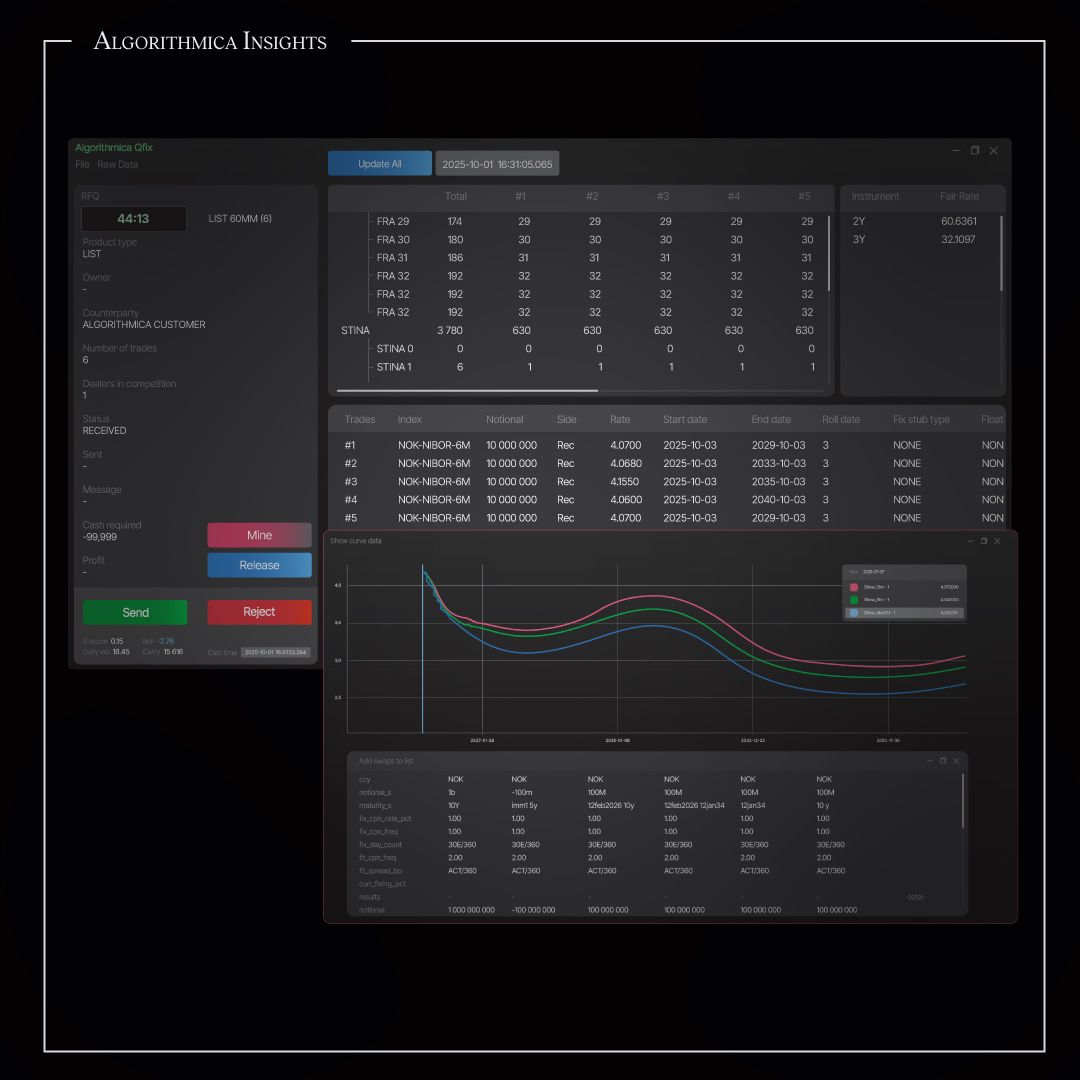
A competitive price doesn't always mean a good trade. In fixed income trading, understanding the impact of a trade on the overall portfolio is just as important as getting the price right. By integrating RFQ pricing with pre-trade risk analysis, traders can: • Assess fair value alongside portfolio risk • Identify exposures before execution • Make more informed trading decisions Discover how connecting pricing and risk in a single workflow can turn every quote into a better-informed portfolio decision.
- LINKEDIN · IMAGESince 13 Oct 2026
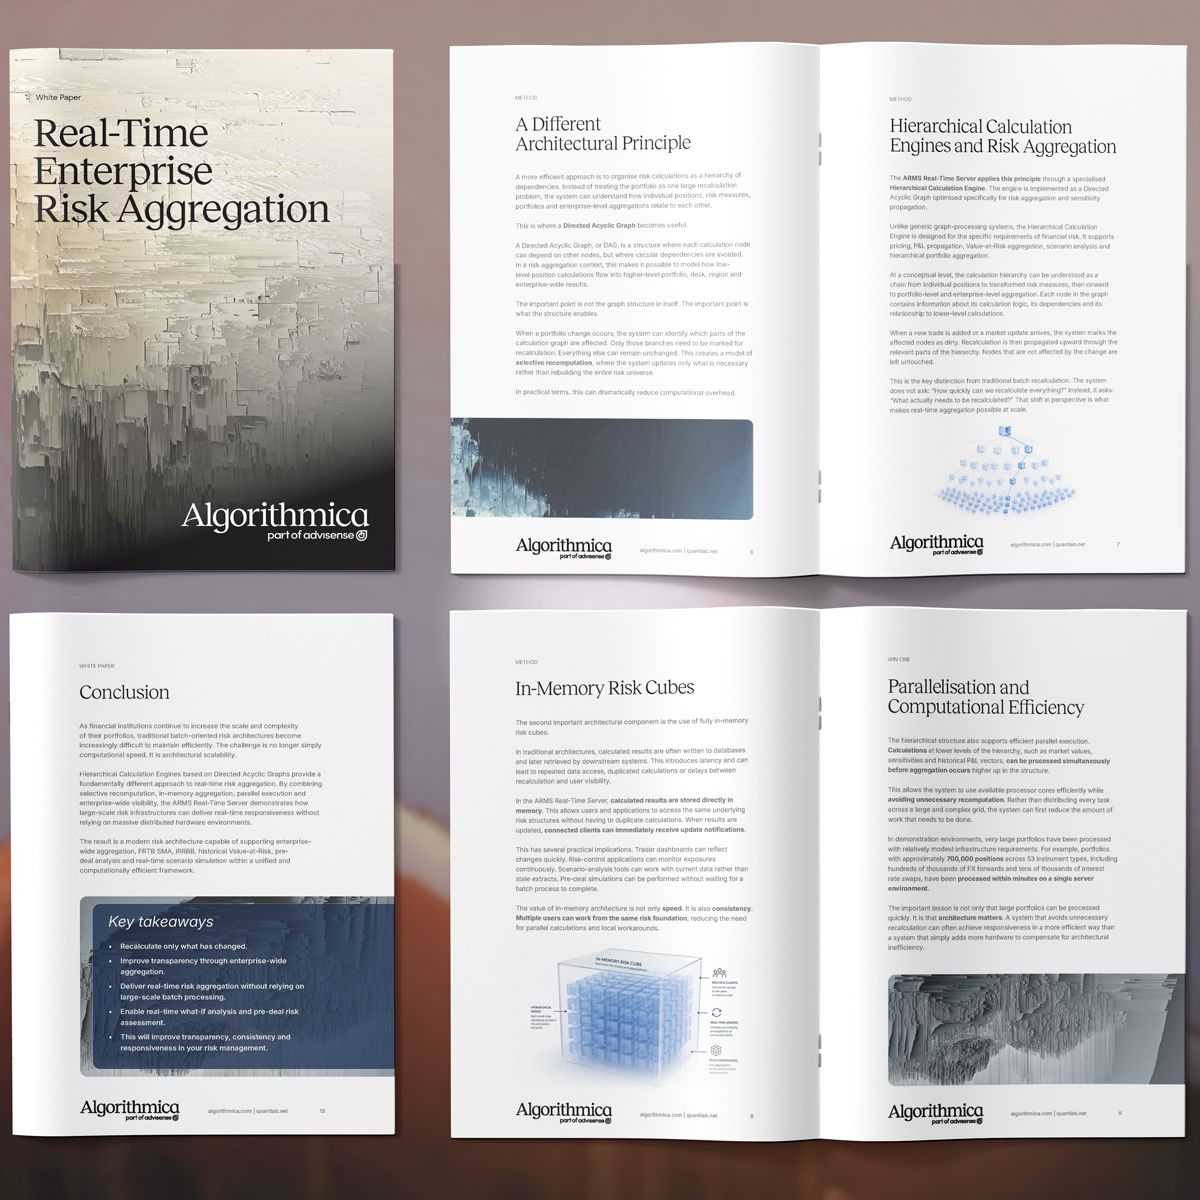
More computing power won't fix an inefficient risk architecture. When a single trade or market update triggers extensive recalculations, adding more hardware may only increase cost and complexity. What if the answer isn't more processing power, but fewer calculations? In our latest white paper, we explore how hierarchical calculation engines, in-memory risk cubes and selective recomputation can transform enterprise-wide risk aggregation. The result? Faster risk insights, greater scalability and the ability to evaluate portfolio changes while decisions are still being made. Read the white paper and discover a different approach to real-time risk.
- LINKEDIN · IMAGESince 13 Oct 2026
Risk doesn't wait until the end of the trading day. Why should your risk systems? As portfolios grow in size and complexity, traditional batch-based risk calculations can struggle to deliver the insights needed for timely decisions. Our new white paper, Real-Time Enterprise Risk Aggregation, explores how modern risk architecture can help financial institutions: • Monitor risk exposures throughout the trading day • Perform real-time what-if and pre-deal analysis • Aggregate risk consistently across trading and banking books • Reduce unnecessary calculations and infrastructure complexity Discover how real-time risk aggregation can turn risk management from a reporting function into an active decision-making tool. Download your copy today.
- LINKEDIN · IMAGESince 13 Oct 2026
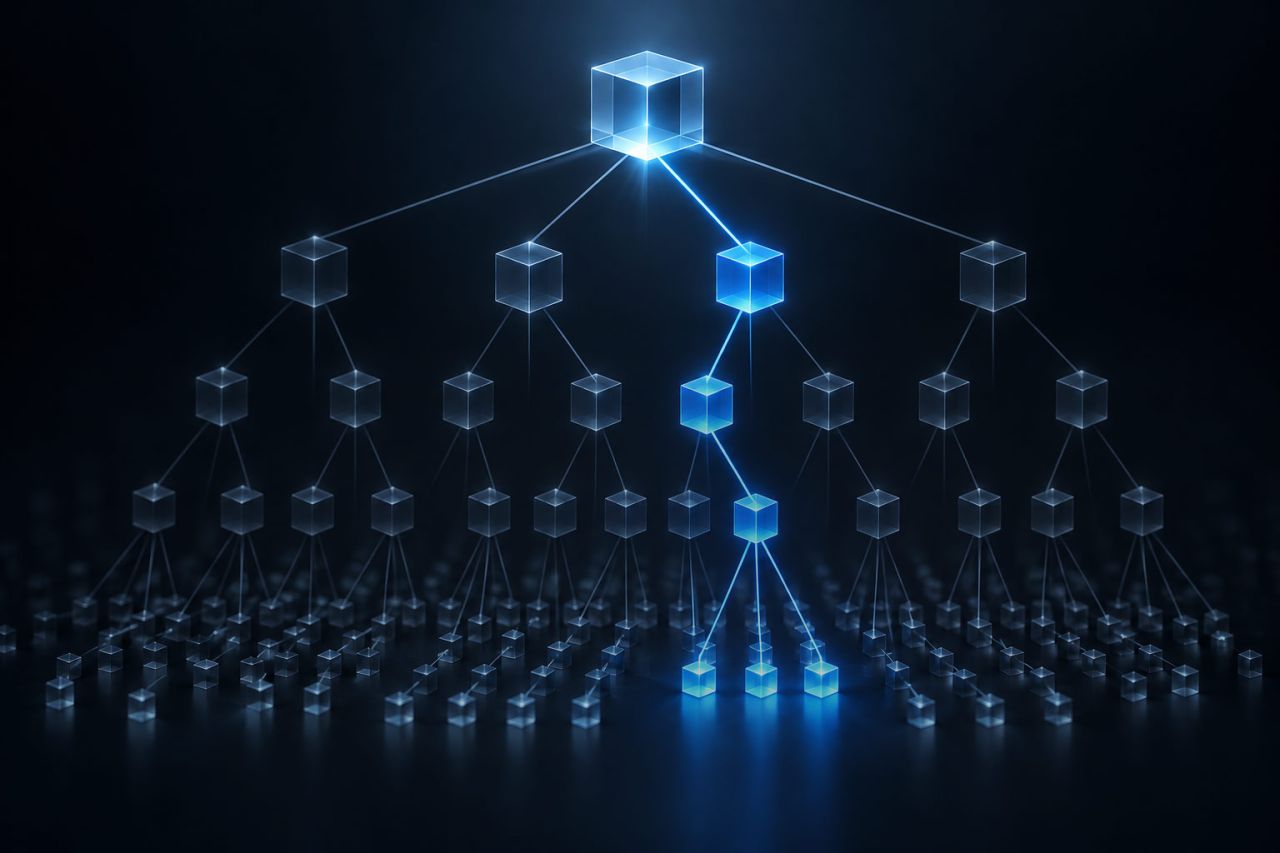
Why recalculate an entire risk portfolio when only a fraction has changed? Traditional batch-based risk systems often perform unnecessary calculations, creating delays and increasing infrastructure costs. Our latest white paper explores a different architectural approach: • Directed Acyclic Graph (DAG) calculation engines • Selective recalculation of affected risk exposures • In-memory risk aggregation • Real-time sensitivity propagation across large portfolios Download our white paper and discover how Algorithmica's real-time risk system, ARMS RiskEye, enables faster, more efficient enterprise-wide risk management.
- LINKEDIN · IMAGESince 23 Sept 2026
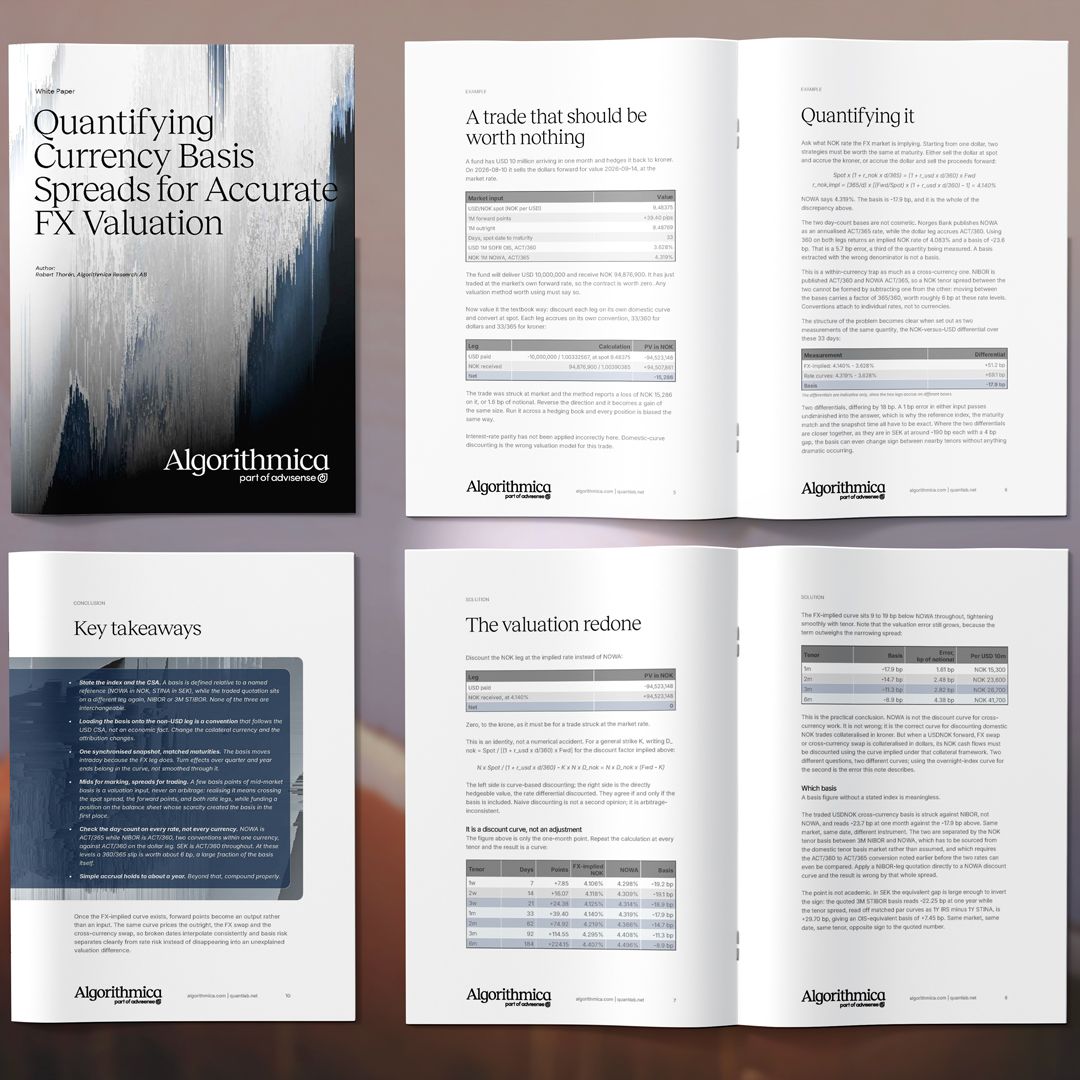
An FX forward struck at the market rate should be worth zero. So why might your valuation show a loss? The missing piece is the currency basis and the cost of the balance-sheet capacity behind the replicating trade. In our updated white paper, we explore: ✓ Why domestic interest-rate curves can give the wrong value for an FX forward ✓ How to derive an FX-implied discount rate from market prices ✓ How to build an FX-implied curve across maturities ✓ Why reference indices, day-count conventions and collateral currency matter ✓ How to reconcile the valuation with the traded forward price A worked example takes the calculation from market inputs to a consistent valuation. Download the full paper below.
- LINKEDIN · IMAGESince 21 Sept 2026
FRTB goes live in the EU on 1 January 2027. But will your capital calculations tell you what you need to know before you trade? A hedge can reduce risk AND increase your FRTB capital. That is one of the consequences of a capital charge that is fundamentally non-additive. A desk’s standalone number is not necessarily its contribution to the firm-wide total, and the capital impact of a trade depends on what happens further up the aggregation hierarchy. With only months to go before the new rules apply, the question is no longer simply whether firms can calculate FRTB capital. It is whether they can calculate it fast enough to use it in actual trading decisions. With ARMS RiskEye, a change to a position triggers recalculation along the affected paths through the aggregation hierarchy – all the way to the firm-wide FRTB number. That makes it possible to explore the capital impact of a trade or hedge while the market is still open. FRTB capital should not just be something you report. It should be something you can manage. Read more: https://lnkd.in/d5wczGHe
6 of 58 adsSign up to see every Algorithmica ad, filter by format and date, and get alerts on new ones.
See all 58 adsWatch the companies you care about.
Filter every ad by industry, country, format and network, and get alerts when a company you watch starts running new ads.