On air · 2 of 3 networks
AB Agathum
- agathum.com
- Real Estate & PropTech
- LT
- 6 employees
AB Agathum’s ads on LinkedIn, Meta and Google, recorded by adsrunning. Browse the latest here for free. Sign up free to see all 31. Watch AB Agathum with Starter to get each new one in your feed.
Watchlist with Starter · $49/mo
| Network | Status | Live ads | Nov 2025LinkedIn activity · 52 weeksOct 2026 | Checked | Next step |
|---|---|---|---|---|---|
| None recorded | 0 | Checked 29 Oct 2026 | See all 31 ads → | ||
| Meta | Running | 2 | Active ads on the Meta Ad Library, all countries | Checked 26 Oct 2026 | Collect them with the API → |
| Running | 7 | Ads on the Google Ads Transparency Center | Checked 28 Oct 2026 | Collect them with the API → |
AB Agathum has no live LinkedIn ads. Its Facebook page had 2 active ads on 26 Oct 2026, and we recorded 7 Google ads on 28 Oct 2026.
Latest ads
- LINKEDIN · IMAGESince 18 Sept 2026
The closer you get to retirement, the fewer shares and more bonds you should hold - right? It's one of the best-known rules in personal finance, and it sounds perfectly logical: as retirement approaches, you want less volatility, more stability and fewer surprises. This is exactly the principle behind lifecycle pension funds. However, in the latest VZ.lt article, Algirdas Pukis, CEO of AB Agathum, looks at research that challenges this conventional rule. If your investment horizon doesn't end on the day you retire, but stretches on for another few decades, then perhaps the biggest risk isn't the portfolio swinging up and down on screen - it's the chance of running out of money later in life. The article covers the balance between shares and bonds, the rationale behind life-cycle funds, how government bonds hold up against inflation, "Sodra" as an invisible bond-like asset, and the investor's most important task: choosing a strategy they can stick with for decades. Read more via the link ↓
- LINKEDIN · IMAGESince 11 Sept 2026
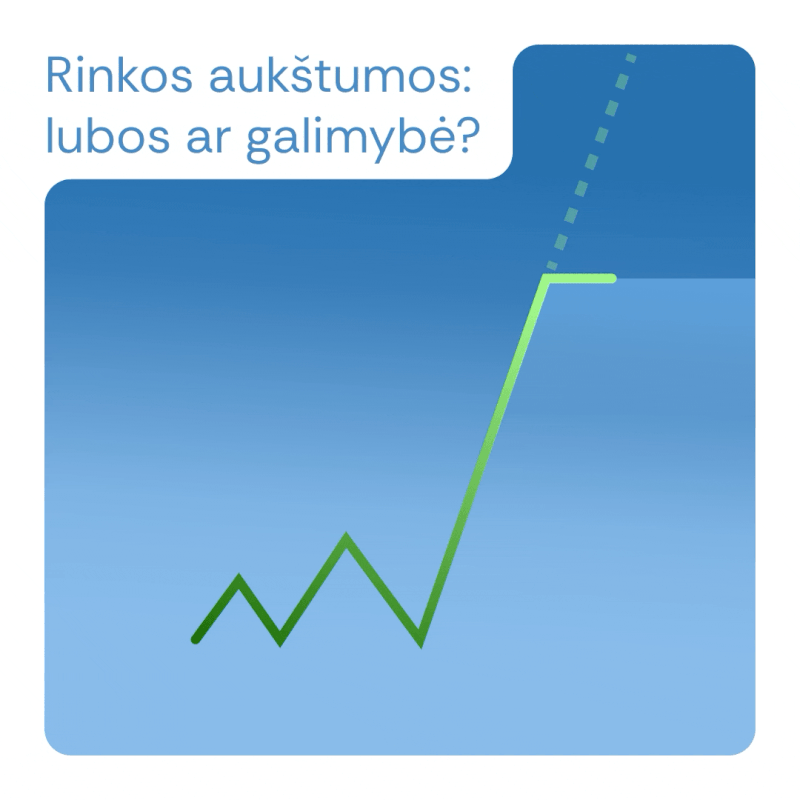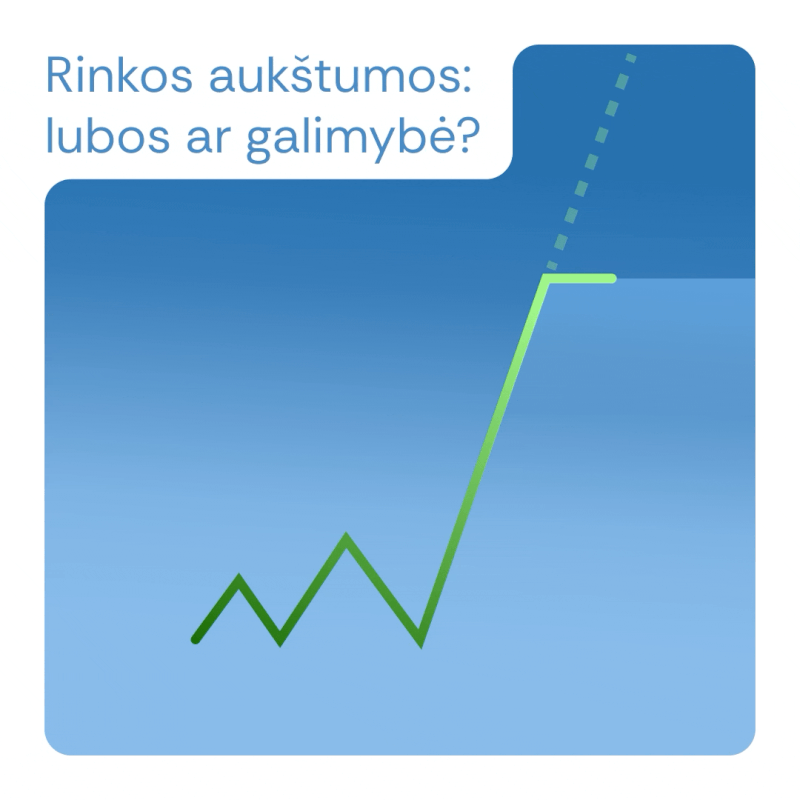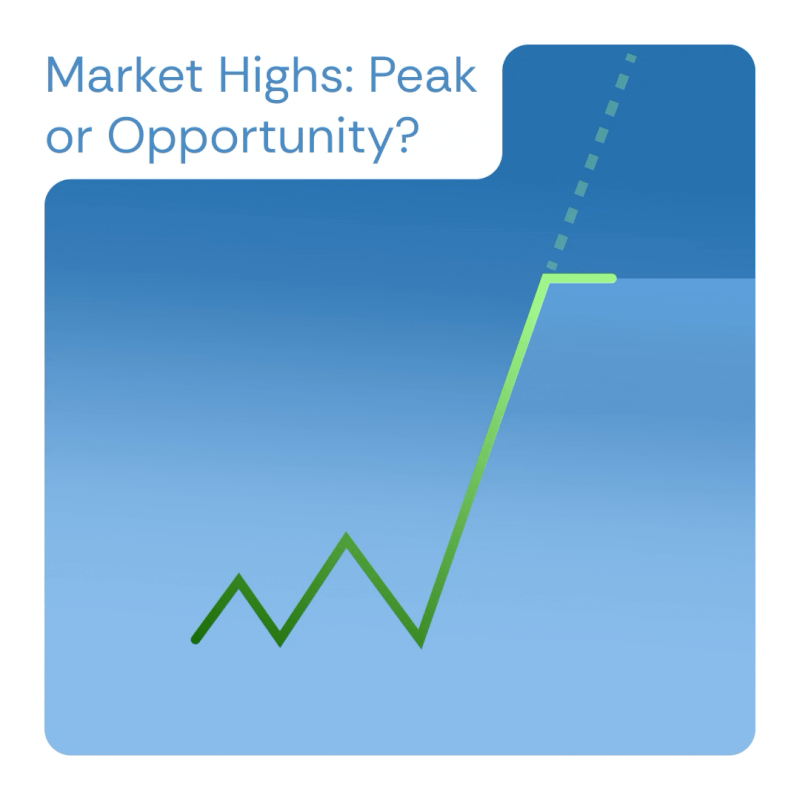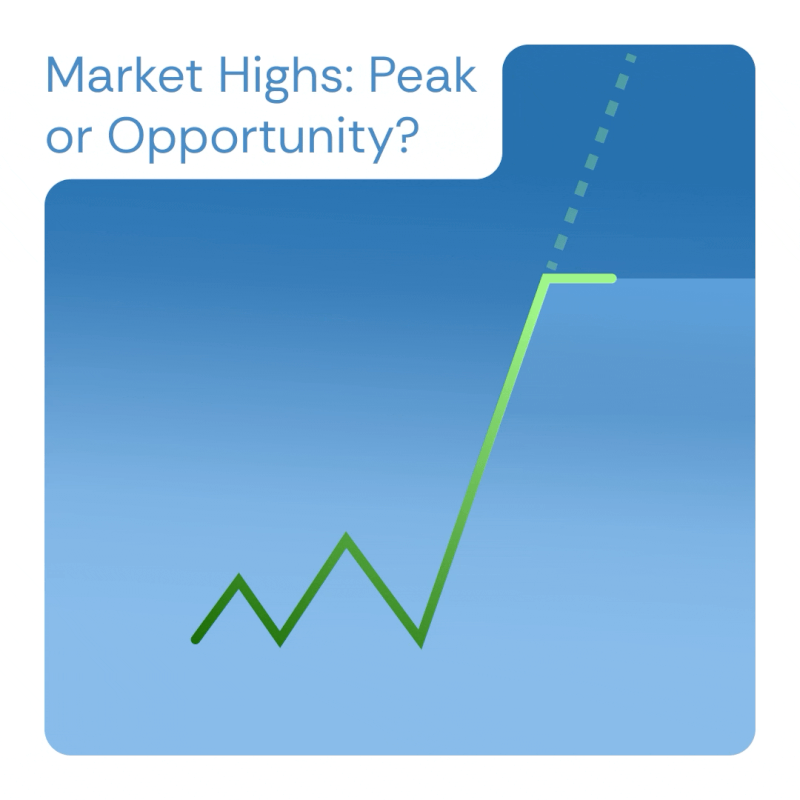
When the market hits a record high, many investors take it as a signal to stop. If shares have climbed to new heights, instinct says: "hold on, it's too expensive now - a fall must be coming." But history tells a different story. Records rarely arrive alone. A strong market can remain strong for a long time, and a new all-time high doesn't mean you're buying at the top of the cycle. Therefore, the simple fact that the market is high isn't a reason to stay out. What matters far more is your time horizon, your appetite for risk, and whether the money you're investing is genuinely intended for the long term. As numerous analyses have shown, the danger in investing isn't only overpaying, but spending years waiting for the perfect moment that never actually arrives.
- LINKEDIN · IMAGESince 3 Sept 2026
Is now the right time to invest? The question sounds prudent, but over the long term it can become one of the most expensive questions in personal finance. In waiting for clarity, for a correction, or for "a better moment", people often don't reduce their risk at all - they just swap it for a less visible one: cash sitting in an account, quietly losing its purchasing power to inflation. In the latest article on vz.lt, Algirdas Pukis, CEO of AB Agathum, analyses the numbers to see what would happen to someone who invested at the worst possible moment. The answer sits uncomfortably with our intuition: historically, even terrible timing has usually beaten sitting on the sidelines.
- LINKEDIN · IMAGESince 20 Aug 2026
When investing, buy what is cheap - a piece of advice that sounds simple and, seemingly, straightforward, doesn't it? Yet in practise, such advice means: buying assets surrounded by bad news at the time, accompanied by poor investor sentiment, a weak currency, inconvenient politics - in short, everything that the majority of market participants want to stay as far away from as possible. This is where the "behavioural tax" originates: on paper, the strategy appears clear - select cheap markets, diversify, stick to the plan and rebalance once a year. In reality, however, this requires discipline, because the cheapest markets rarely appear safe or attractive. That is why most investors not only overpay, but also avoid undervalued assets precisely when they become interesting. Value investing is not merely an exercise in numbers - it is also a test of character. The figures can show where the opportunity lies, but the decision is still made by a person who must endure an uncomfortable present for the sake of potential long-term returns.
- LINKEDIN · IMAGESince 13 Aug 2026
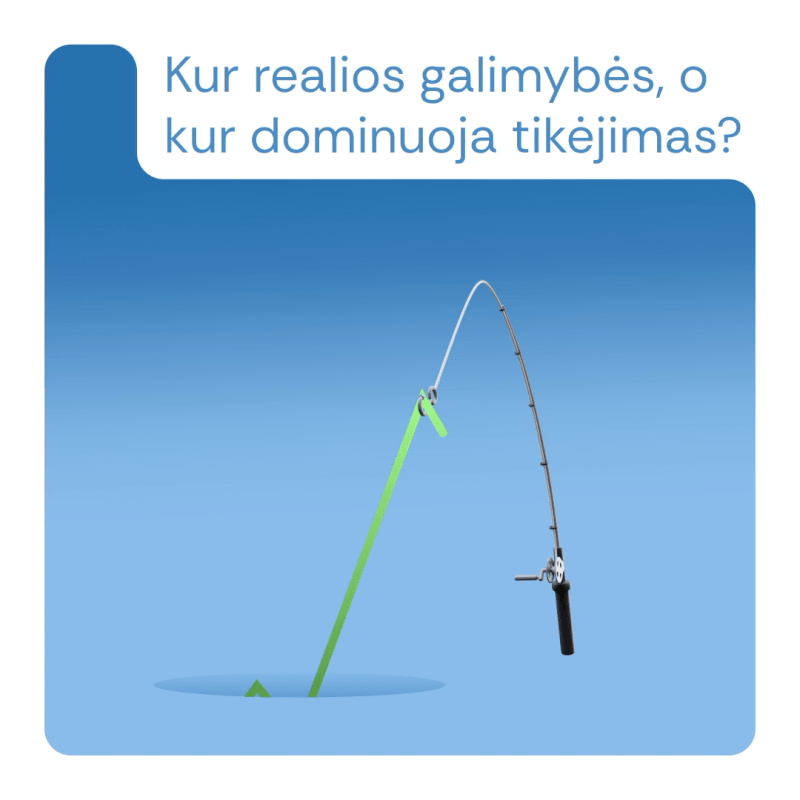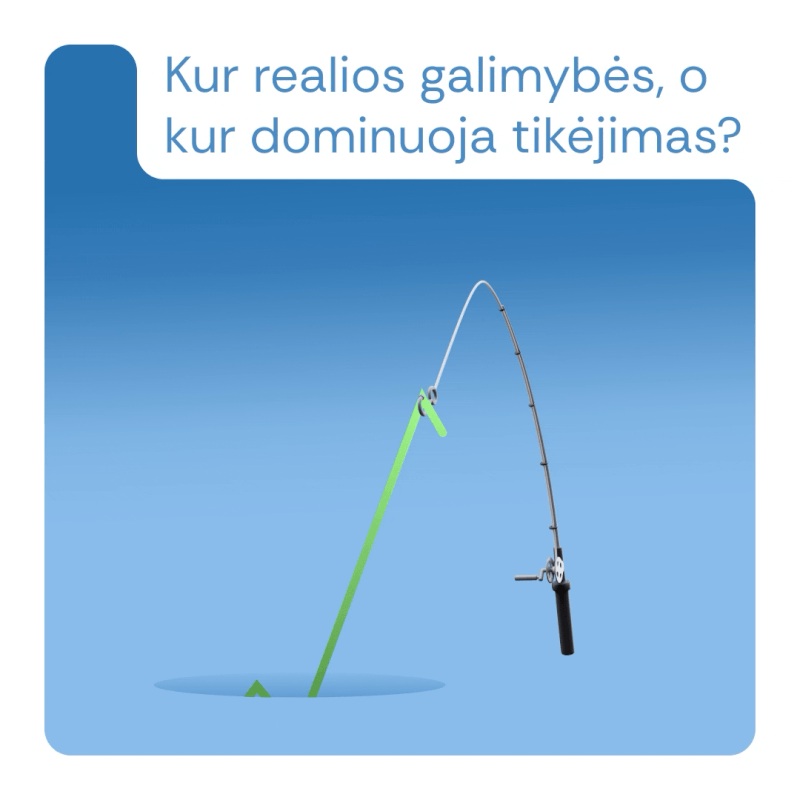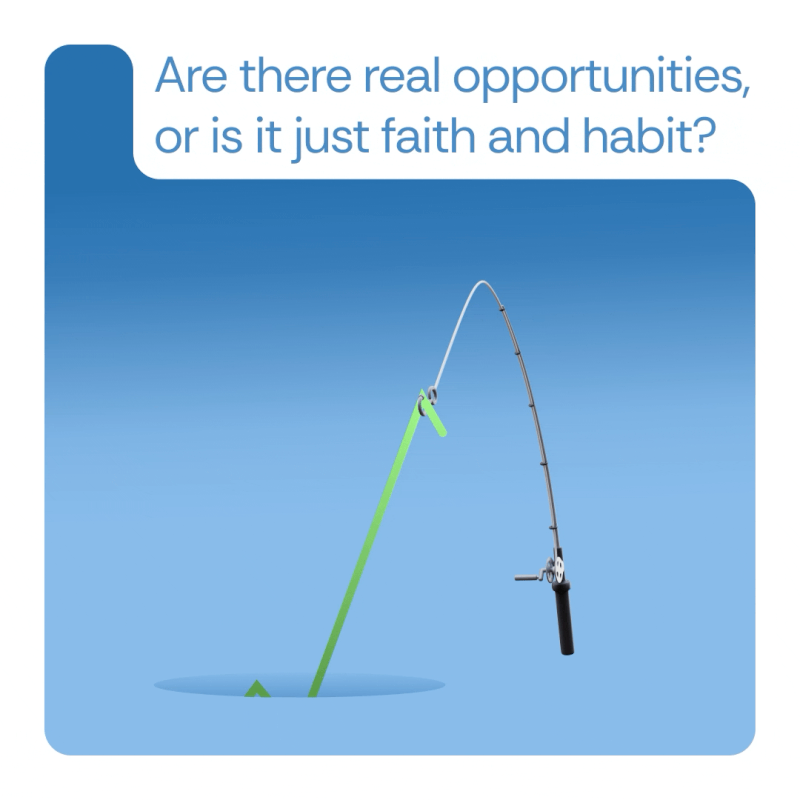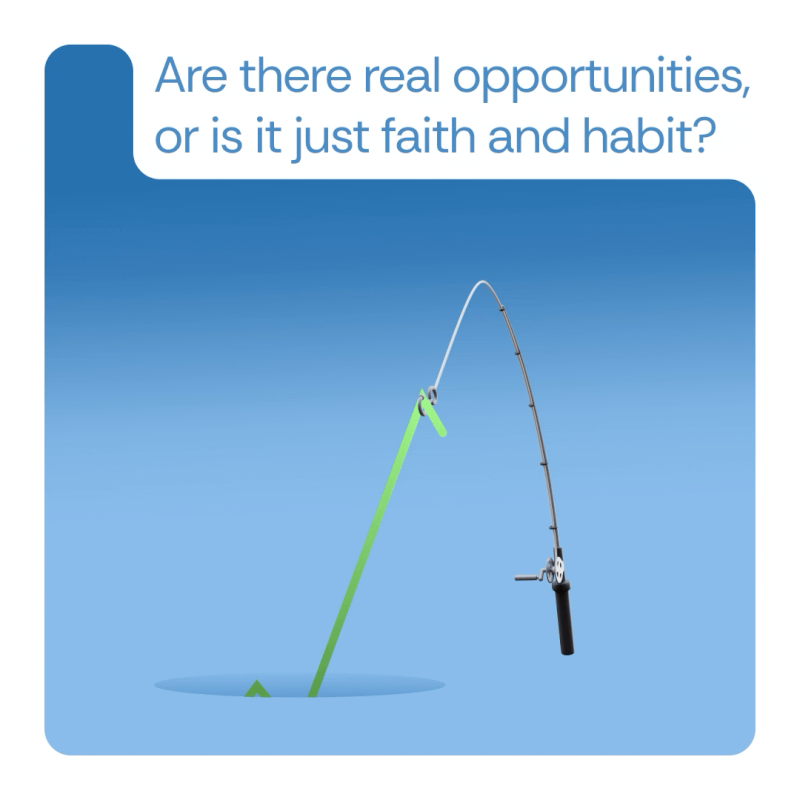
The first rule of successful fishing: fish where the fish are. In investing, this means a very simple question: where are the real opportunities today, and where do faith, habit and following the crowd dominate? Over the past decade, the most attention has gone to the US market and the major technology companies. There were reasons for this: their results made a respectable impression. However, good past returns do not yet mean that future returns will be the same, especially if a great deal of optimism is already priced in. Research based on the CAPE ratio reveals something interesting: buying the world's cheapest markets, rather than the most popular ones at the time, has historically enabled highly competitive long-term returns. Of course, this by no means suggests that we should blindly buy anything that appears cheap - cheap markets are usually so for a reason. But it is a reminder that an investor should look beyond a single country, a single index or a single prevailing narrative.
- LINKEDIN · IMAGESince 6 Aug 2026
Many investors today consider the US equity market an almost obligatory part of a portfolio. After a long successful period, the S&P 500, the "Magnificent 7" and QQQ have become not only popular but overwhelmingly dominant investment choices. In investing, however, it is always worth pausing and asking oneself: are the best opportunities really where everyone's gaze is directed? In our latest VZ.lt article, we examine the logic of global value investing: what the CAPE ratio shows, why the world's historically cheapest markets have often outperformed the most expensive ones, and why Japan's 1989 story remains an important reminder for investors even today. This is an article about a simple but challenging-to-implement principle: buying not what is popular, but what is justifiably cheap. It also explores why diversification is not only protection, but sometimes also an aggressive long-term returns strategy.
6 of 31 adsSign up to see every AB Agathum ad, filter by format and date, and get alerts on new ones.
See all 31 adsWatch the companies you care about.
Filter every ad by industry, country, format and network, and get alerts when a company you watch starts running new ads.