Not on air · 2 of 3 networks checked
Swipelux
- swipelux.com
- Software Development
- EE
- 9 employees
Swipelux’s ads on LinkedIn, Meta and Google, recorded by adsrunning. Browse the latest here for free. Sign up free to see all 56. Watch Swipelux with Starter to get each new one in your feed.
Watchlist with Starter · $49/mo
| Network | Status | Live ads | Nov 2025LinkedIn activity · 52 weeksNov 2026 | Checked | Next step |
|---|---|---|---|---|---|
| None recorded | 0 | Checked 30 Oct 2026 | See all 56 ads → | ||
| Meta | Not checked | — | |||
| None recorded | 0 | No ads found on the Google Ads Transparency Center | Checked 16 Oct 2026 | Collect them with the API → |
Swipelux has no live LinkedIn ads. We recorded no Google ads on 16 Oct 2026.
Latest ads
- LINKEDIN · VIDEOSince 30 Oct 2026
You can now open SWIFT accounts at BMO Bank N.A. in your customers' names, in 17 currencies. AUD, CAD, CHF, CZK, DKK, EUR, GBP, HKD, HUF, JPY, MXN, NOK, NZD, PLN, SEK, SGD, ZAR. In the dashboard it takes a few clicks: open a customer, go to Payment access, Open bank account, pick a currency and choose BMO Bank N.A. Through the API it's the same accounts endpoint with method swift, your currency and institution bmo. Live now on every tier. The 30-second walkthrough is below. One limit: SWIFT is still SWIFT. Timing depends on the banks along the route, so where a local rail exists, that is usually faster. Which of these 17 currencies do your customers ask for most?
- LINKEDIN · IMAGESince 29 Oct 2026
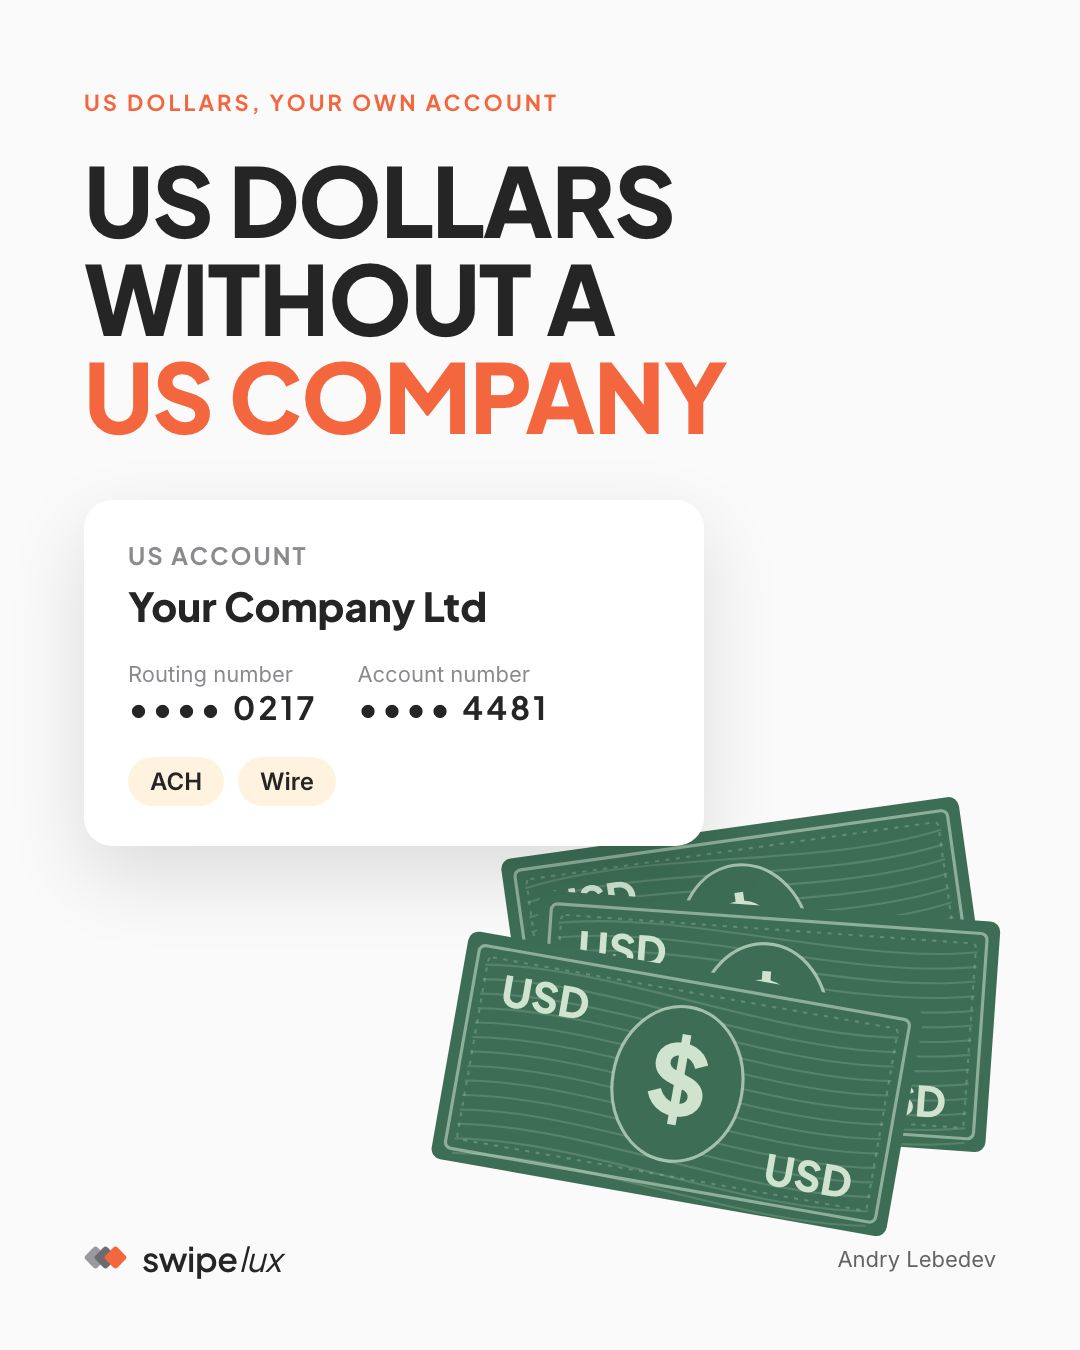
You can get paid by American clients in dollars without opening a US company. Founders outside the US ask me how more than anything else, so here it is. With Swipelux your company gets a US account in its own name, with a routing number and an account number. Your clients pay you by ACH or wire, the same way they pay any US vendor. Under the hood it is front end TradFi, back end USDC. When the money arrives, you keep it as USDC or pay it out in local currency to your bank at home. If you have US clients and no US entity, send me your flow. I will tell you if it fits. You can also book a call with me from the link on my profile.
- LINKEDIN · IMAGESince 15 Aug 2026
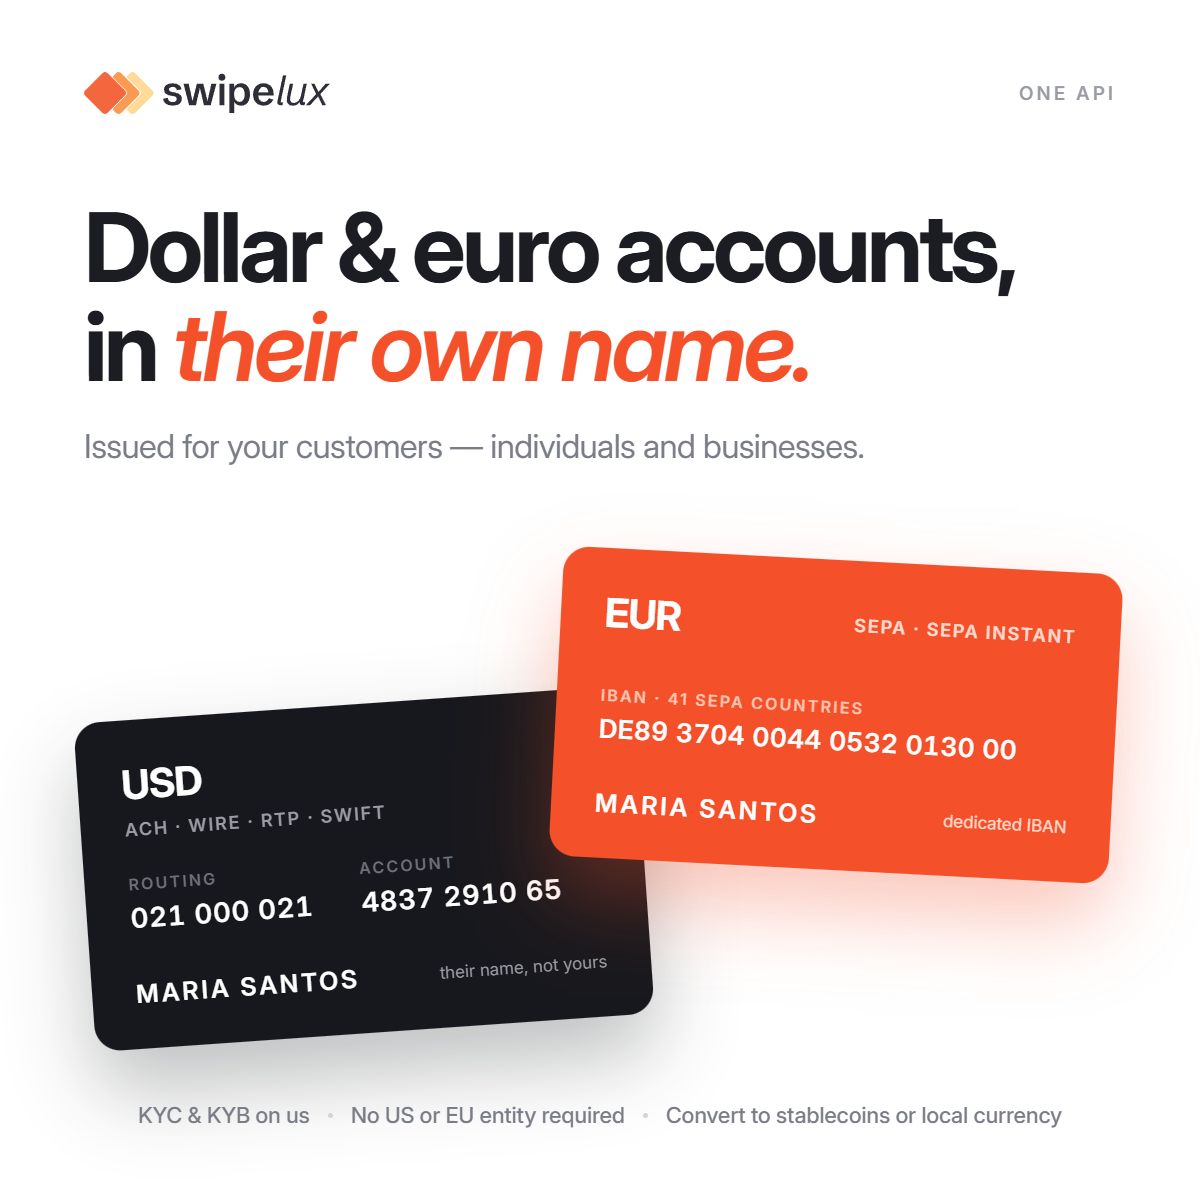
Big update for fintechs collecting and paying out in dollars and euros. Your customers can hold dollar and euro accounts in their own name, issued through one API. 🇺🇸 USD: ACH, Wire, RTP and SWIFT, with routing and account number 🇪🇺 EUR: SEPA and SEPA Instant, with a dedicated IBAN across 41 SEPA countries 🏷 Your customer's own name on the account and payment descriptors ✅ First and third-party payments, for individuals and businesses 💱 Convert to stablecoins or local currency whenever they choose No US or EU entity required on your customer's end. KYC and KYB are handled on our side, so you can launch both currencies at once instead of running two integrations and two onboarding flows. Want to see how this fits your flows? Let's hop on a call → https://lnkd.in/eq6YS4_p
- LINKEDIN · IMAGESince 13 Aug 2026
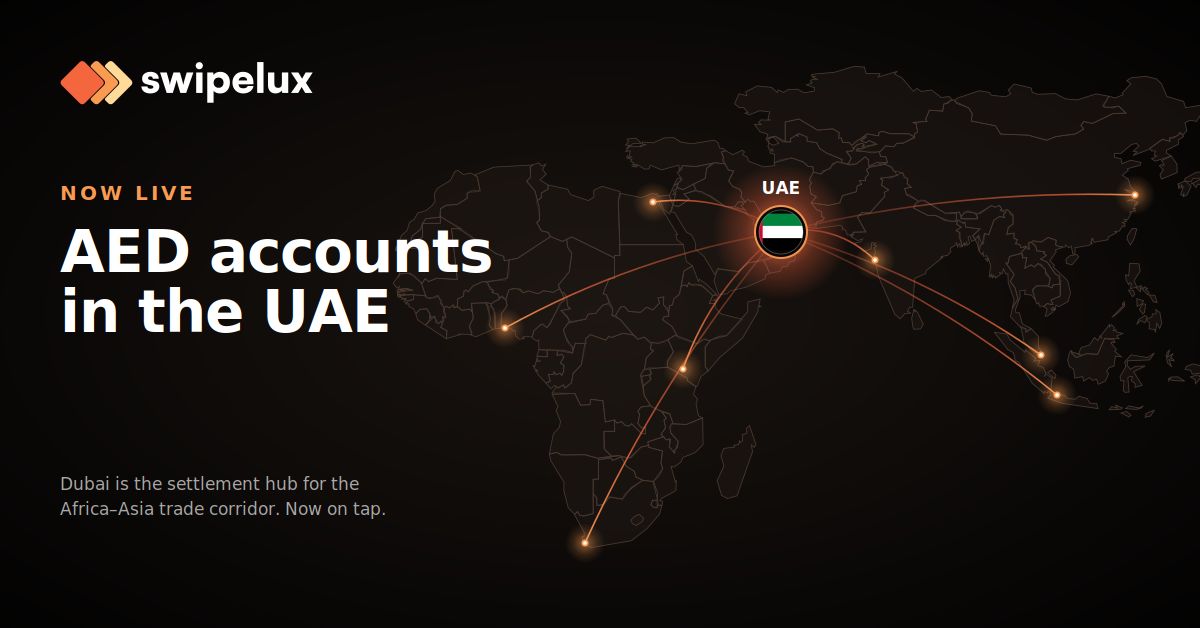
Now live on Swipelux: AED accounts in UAE. Dubai has become the settlement hub for Africa and Asia trade. Commodity deals, import/export, remittances — a huge chunk of it clears through the Emirates. The problem: opening an AED account as a foreign company means months of paperwork, in-person visits, and compliance requirements most fintechs can't meet. What we just shipped: → Named AED accounts for businesses → Local pay-in and pay-out rails → Stablecoin settlement underneath — you send USDC, recipient gets AED same day Real example: a trading company moves goods from Asia to East Africa. Their buyers pay in AED, they settle suppliers in USD and local currencies. Before, they held three banking relationships and reconciled manually. Now it's one API, automatic conversion, same-day settlement across all legs. If you're building for the Africa-Asia corridor and not routing through Dubai yet, you're leaving money on the table: https://lnkd.in/dCpNpc65
- LINKEDIN · IMAGESince 13 Aug 2026
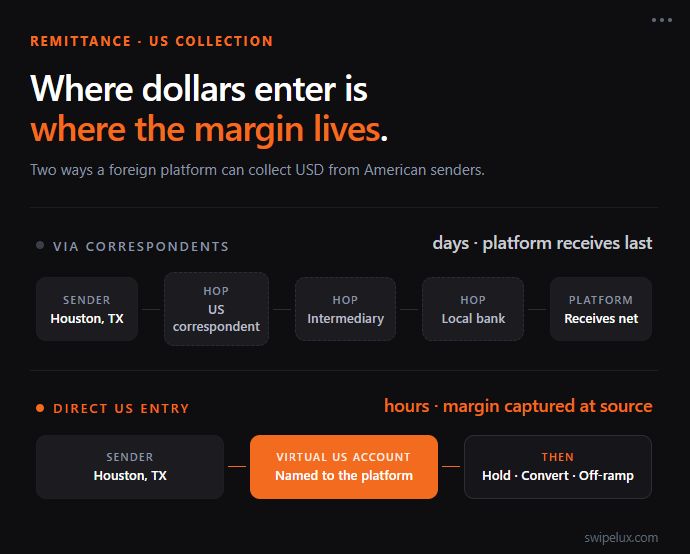
Remittance companies outside the US face the same problem: collecting dollars from American senders. Opening a US bank account as a foreign entity means months of paperwork, compliance requirements, and often a hard no from the bank. So most route through intermediaries, each taking a cut. At Swipelux, we've been building infrastructure for this exact use case. A remittance platform gets a named US account with ACH, Wire, and RTP access. No US entity required. The sender in Houston pays via ACH — instant, no fee on their end. The money lands in the platform's US account within hours. From there, the platform controls the settlement: hold in USD, convert to stablecoin, off-ramp to the destination country through local rails. The key shift is where the money enters. Instead of collecting through a correspondent chain, the platform owns the US entry point. That's margin recaptured at the source.
- LINKEDIN · IMAGESince 13 Aug 2026
US Virtual Accounts Are Live on Swipelux One of the most common requests we get from fintechs outside the US: "My customers need to receive USD from American clients, but opening a US bank account takes months and usually requires a local entity." We now offer named US accounts via API. ACH, Wire, RTP, Fedwire. The account shows your customer's name. No US entity required on their end. One example: a Singapore fintech serves SMBs invoicing American clients. Before, payments took days to reconcile. Now each SMB has their own account. Payment arrives, gets converted to SGD, settles same day. - Named accounts with routing and account number - ACH, RTP (instant up to $1M), Fedwire (same-day, no cap) - First and third-party payments - Conversion to stablecoins or local currencies Want to offer named US accounts to your customers? Let's talk → https://lnkd.in/gASsRMmV
6 of 56 adsSign up to see every Swipelux ad, filter by format and date, and get alerts on new ones.
See all 56 adsWatch the companies you care about.
Filter every ad by industry, country, format and network, and get alerts when a company you watch starts running new ads.