On air · 1 of 3 networks
Marcus Evans Group
- marcusevans.com
- IE
- 2,515 employees
Marcus Evans Group’s ads on LinkedIn, Meta and Google, recorded by adsrunning. Browse the latest here for free. Sign up free to see all 75. Watch Marcus Evans Group with Starter to get each new one in your feed.
Watchlist with Starter · $49/mo
| Network | Status | Live ads | Nov 2025LinkedIn activity · 52 weeksOct 2026 | Checked | Next step |
|---|---|---|---|---|---|
| Running | 63 | Checked 29 Oct 2026 | See all 75 ads → | ||
| Meta | Not checked | — | |||
| Not checked | — |
Marcus Evans Group has 63 live LinkedIn ads.
Latest ads
- LINKEDIN · IMAGESince 15 Oct 2026
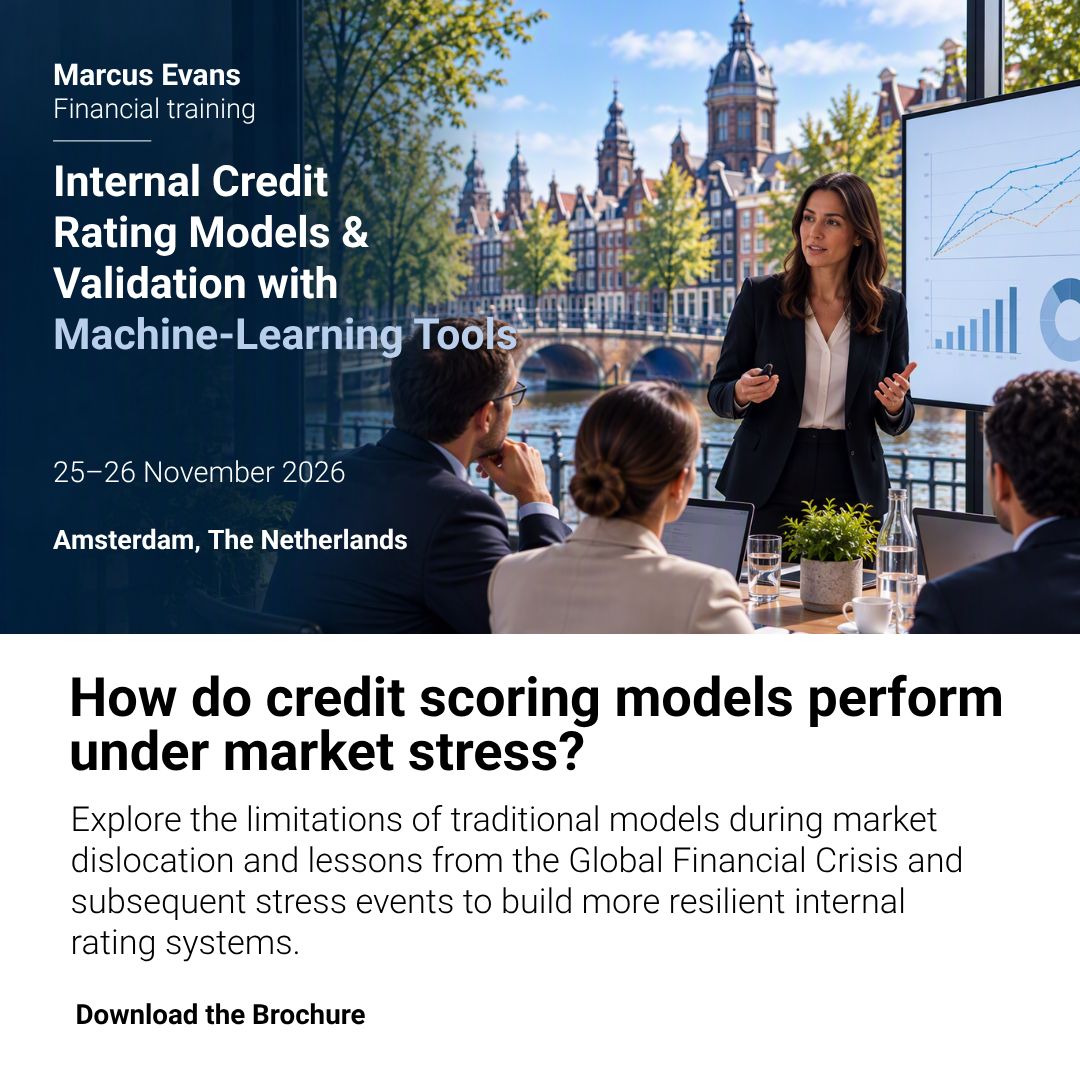
What happens to credit scoring models when markets come under pressure? When markets dislocate, traditional credit scoring models can struggle to capture rapidly changing risk. Explore the lessons from the Global Financial Crisis and subsequent stress events to understand how internal rating systems can be made more robust. Join the discussion and explore: • Where traditional credit scoring models fall short during periods of stress • What past crises can teach us about model resilience • How to strengthen internal rating systems for stressed market conditions Discover the latest approaches to building more resilient credit risk frameworks here: https://lnkd.in/duex-g_P Need more information before registering? Reach out to [email protected].
- LINKEDIN · IMAGESince 15 Oct 2026
If you work in credit risk, quantitative modelling, model development, validation or machine learning, this Marcus Evans Financial Training masterclass will give you practical insights into deploying the latest tools for internal credit rating models. Explore how leading financial institutions are implementing these changes while meeting evolving regulatory expectations. Led by expert trainer Andre Horovitz, the two-day programme features practical examples, case studies, exercises and group discussions, with content tailored to the experience and priorities of the attending group. Internal Credit Rating Models & Validation with Machine-Learning Tools Amsterdam | 25–26 November 2026 𝗘𝘅𝗽𝗹𝗼𝗿𝗲 𝘁𝗵𝗲 𝗳𝘂𝗹𝗹 𝗽𝗿𝗼𝗴𝗿𝗮𝗺𝗺𝗲: https://lnkd.in/duex-g_P 𝗙𝗼𝗿 𝗿𝗲𝗴𝗶𝘀𝘁𝗿𝗮𝘁𝗶𝗼𝗻 𝗶𝗻𝗳𝗼𝗿𝗺𝗮𝘁𝗶𝗼𝗻, please contact [email protected]
- LINKEDIN · IMAGESince 15 Oct 2026
Are your internal rating systems robust enough for volatile markets? In this interactive Marcus Evans course, you collaborate with peers from global financial institutions to test the limits of traditional models, implement ML-based enhancements, and align with the latest supervisory expectations. Gain practical tools you can deploy immediately across your portfolios. 𝗘𝘅𝗽𝗹𝗼𝗿𝗲 𝘁𝗵𝗲 𝗳𝘂𝗹𝗹 𝗽𝗿𝗼𝗴𝗿𝗮𝗺𝗺𝗲: https://lnkd.in/duex-g_P For more relevant information, please contact [email protected]
- LINKEDIN · IMAGESince 15 Oct 2026
You don’t just need compliant credit rating models—you need models that drive better decisions. In our practical, case-study driven training, you’ll work with seasoned industry experts to refine development, validation and calibration techniques and explore emerging trends in credit risk modelling. Join peers from top global banks and upgrade your toolkit. 𝗘𝘅𝗽𝗹𝗼𝗿𝗲 𝘁𝗵𝗲 𝗳𝘂𝗹𝗹 𝗽𝗿𝗼𝗴𝗿𝗮𝗺𝗺𝗲: https://lnkd.in/duex-g_P 𝗙𝗼𝗿 𝗿𝗲𝗴𝗶𝘀𝘁𝗿𝗮𝘁𝗶𝗼𝗻 𝗶𝗻𝗳𝗼𝗿𝗺𝗮𝘁𝗶𝗼𝗻, please contact [email protected]
- LINKEDIN · IMAGESince 15 Oct 2026
Bridge the gap between academic ML techniques and real-world credit risk practice. Our global financial markets trainers guide you step by step through using penalised regression, gradient boosting, random forests and neural networks to enhance internal rating systems, PD/LGD estimation and validation—either in public sessions or tailored in-house programmes. More details ⬇
- LINKEDIN · IMAGESince 15 Oct 2026
New session: Machine Learning for Private Debt Portfolio Replication How can machine learning help replicate the risk and return characteristics of private debt portfolios using liquid market instruments? The ICRMV with ML course introduces an advanced application of ML to portfolio construction, exploring how to identify optimal combinations of index funds, Treasury bonds, syndicated loans, corporate notes, swaps and vanilla options to replicate the PD distribution, returns and volatility of private loan portfolios. Explore the latest applications of machine learning in credit risk modelling, calibration, validation and portfolio construction. **Discover the course and its new session.** ⬇
6 of 75 adsSign up to see every Marcus Evans Group ad, filter by format and date, and get alerts on new ones.
See all 75 adsWatch the companies you care about.
Filter every ad by industry, country, format and network, and get alerts when a company you watch starts running new ads.